A Roth Conversion Can Cut Your Lifetime Tax Bill. Timing Matters More Than Most Retirees Realize

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Most people who think about Roth conversions focus on the wrong question. They ask whether a conversion makes sense at all, when the more consequential issues are timing and how much to convert each year. A conversion made at the right point in a retiree’s financial timeline can reduce lifetime taxes meaningfully. The same conversion, made at the wrong time or in the wrong amount, can generate costs that erase most of the benefit.
The mechanics are simple. Money moves from a traditional IRA or 401(k), where contributions were pre-tax and growth is tax-deferred, into a Roth IRA, where growth and qualified withdrawals are tax-free. The conversion is taxable in the year it happens. The underlying wager is that paying tax now, at a known rate, beats paying tax later at an unknown rate on a larger balance.
The calculus changed in 2025. The One Big Beautiful Bill Act, signed July 4, 2025, made the Tax Cuts and Jobs Act’s income tax rates permanent. Planners had long pointed to the scheduled TCJA expiration as a reason to convert sooner, and that deadline pressure has faded. The more durable argument remains: a retiree’s effective tax rate tends to climb once required minimum distributions begin, whatever Congress does with federal rates later.
Why the Window Between Retirement and RMDs Is the Opportunity
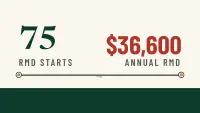
The strongest case for conversions falls in a window many retirees overlook or underuse: the years after leaving the workforce and before required minimum distributions begin. RMDs generally start at 73. For those born in 1960 or later, the start age rises to 75 under the SECURE 2.0 Act. That gap is often the most tax-efficient stretch a retiree will ever have.
During these years, paychecks have stopped and RMDs have not started. Social Security may not have begun either, so taxable income can fall to unusually low levels. That means the first several dollars converted may land in the 10% or 12% federal bracket. For 2026, the 12% bracket for married couples filing jointly covers $24,801 to $100,800 of taxable income, after the $32,200 standard deduction is subtracted. Income converted now would otherwise face whatever rates apply once RMDs start, when income is higher, harder to control, and more likely to push a retiree into IRMAA surcharge territory on Medicare premiums.
Strategists call this filling the bracket: converting enough each year to reach the top of a bracket without spilling into the next one. Spreading conversions across five or six years can meaningfully shrink the traditional IRA balance that would otherwise generate mandatory withdrawals later, which is the central goal of the exercise.
The Opportunity Cost Question
Every conversion triggers an immediate tax payment, and whether that payment is a smart move depends heavily on where the money to cover it comes from.
The most efficient setup pays the tax bill with money held outside the IRA. Suppose a retiree converts $50,000 and covers the tax from a taxable brokerage account. The full $50,000 lands in the Roth and keeps compounding tax-free. If the tax instead comes out of the converted funds, less money enters the Roth, and the long-term compounding advantage shrinks with it. Funding source is one of the more consequential details in conversion planning, and one that most people overlook.
Time horizon matters just as much. The tax is due now, while the payoff arrives gradually through tax-free growth, smaller RMDs, and Roth withdrawals that do not push other income into higher brackets in later years. Retirees in their 50s or early 60s have time for that payoff to build, so the math often favors conversion. For a retiree in their late 70s with a modest balance, the break-even point may never arrive within their lifetime.
The Mistakes That Undercut the Strategy
Converting too much in a single year is the most common error. A large conversion can lift income into a higher federal bracket, trigger IRMAA surcharges on Medicare premiums for the following two years, make more Social Security benefits taxable by raising provisional income, and push capital gains into a higher rate. These effects stack within the same tax year, so a move that looks smart on its own can become expensive.
IRMAA deserves close attention because it behaves like a cliff. For 2026, the IRMAA tiers begin at $109,000 of modified adjusted gross income for single filers and $218,000 for couples filing jointly. Crossing a threshold by even one dollar can trigger the full surcharge for both Part B and Part D for an entire year.
The standard 2026 Part B premium is $202.90 per month, up from $185.00 in 2025. At the top tier, the top 2026 IRMAA bracket starts at $500,000 for single filers and $750,000 for married couples filing jointly, and it adds the largest Part B premium of $689.90. Because IRMAA is based on your client’s MAGI from two years prior (2024 tax return for 2026 premiums), a large conversion today shows up as a higher Medicare bill two years later, long after the tax return has been filed.
State income taxes add a layer that federal-only analysis misses. In high-tax states, the effective marginal rate on a conversion runs well above the federal rate alone. A retiree planning to move to a low- or no-income-tax state faces different math than one who will stay put, so the state of residence on conversion day carries real dollar consequences.
Roth owners are never subject to RMDs during their own lifetime, which makes Roth accounts more efficient vehicles for passing wealth than traditional IRAs. Heirs who inherit a traditional IRA owe ordinary income tax on each distribution. The entire balance of an inherited retirement account must be emptied by the end of the 10th year after the year of the owner’s death for most non-spouse beneficiaries. Under the 2024 IRS final regulations, heirs may also owe annual withdrawals during those 10 years if the original owner had already reached their required beginning date. Those compressed timelines and ordinary income rates can make a Roth conversion a useful estate-planning tool.
The estate tax picture has also shifted. Effective January 1, 2026, the federal exemption for estate, gift, and GST tax increased to $15 million per individual. This amount will also be indexed for inflation beginning in 2027. For many families, the main concern is now income tax on inherited accounts rather than the estate tax itself.
Building the Right Approach
A Roth conversion is a recurring annual planning decision, not a one-time event. It depends on current and projected income, tax brackets, Medicare thresholds, Social Security timing, and the balance across account types. Each change in income, account balance, or tax law can shift the answer, so a plan built several years ago may need substantial revision.
The retirees who benefit most treat conversion as a deliberate trade. They pay a known tax now, at a rate they can partly control, in exchange for more flexibility later, smaller RMDs, and withdrawals that do not push other income into higher brackets. The retirees who get burned usually convert large lump sums without modeling the side effects, or convert in years when income is already elevated.
Working with a tax professional or financial planner to model conversion amounts year by year, against projected income, brackets, and IRMAA thresholds, is where the strategy succeeds or fails. The concept is simple. Execution is where the lifetime savings are captured.
Editor’s note: The article now reflects 2026 figures, including a $32,200 standard deduction for joint filers, a 12% bracket running from $24,801 to $100,800, and a $202.90 standard Part B premium. It also adds the $689.90 top-tier premium, the $15 million federal estate exemption, and the annual withdrawal requirements that apply to many inherited IRAs.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.