She Was Told Selling the House Would Double Her Medicare Premium. The Real Answer Turned on a Two-Year Deadline Nobody Mentioned
A widowed homeowner rejected her advisor's advice after a church friend warned her that selling her house would spike her Medicare premiums for years. Both of them had pieces of the truth, and the part that matters most depends on…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
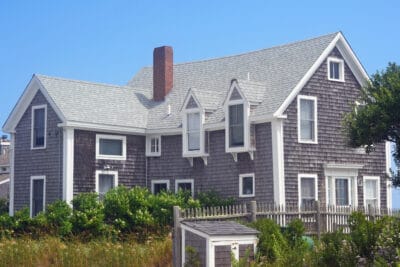
A 72-year-old widow owns a paid-off Cape Cod she and her husband bought in 1998 for $180,000. The identical house next door just sold for $780,000. Her advisor told her to cash out, move into a condo, and put the difference to work. She said no.
A friend at church had warned her that a check that size would double her Medicare premium for two straight years, and she wasn’t handing Medicare an extra $500 a month for the privilege of moving. Her friend was wrong about the shape of it, mostly. But not entirely, and the part she got right depends on a date.
What Medicare Can and Can’t See
Start with what Section 121 does. Sell your principal residence and a single filer excludes up to $250,000 of gain. A married couple filing jointly excludes up to $500,000. You need to have owned the place and lived in it for at least 24 of the last 60 months. Excluded gain never becomes income. It doesn’t reach your adjusted gross income (AGI), so it can’t reach the modified figure Medicare uses, and it can’t touch your premium. That part of the sale is genuinely invisible.
What’s left over is less hidden. Her raw gain runs about $600,000. Filing single, the $250,000 exclusion leaves roughly $350,000 on the return before any basis adjustments, and that number stacks on top of her Social Security and any IRA withdrawals. So her friend wasn’t hallucinating a risk. She was just describing the wrong size of it. Worth noting, as many members miss this, a gain recognized in a single tax year raises your premium for one year, two years down the line. Not two years running. That happens only if the income lands across two returns.
How the Lookback Works
Medicare prices your premium off a return from two years back. What you reported for 2024 set your 2026 premium. What you report for 2026 sets 2028. The figure it reads is your AGI plus any tax-exempt interest. Municipal bond income that feels tax-free counts here. And roughly 8% of Part B beneficiaries pay any surcharge at all, so if your income sits well below the first bracket and stays there after closing, none of this is your problem. A note on paperwork: excluded gain often stays off the return, but not always. If the closing generated a Form 1099-S, or if part of the gain is taxable, it can still show up on Form 8949 and Schedule D.
The Deadline That Moves $250,000
Here’s what her advisor should have led with. A surviving spouse can claim the full $500,000 exclusion if the sale closes within two years of the spouse’s death, provided the couple met the ownership and use tests when he died. Sell before the second anniversary and she shelters $500,000, leaving roughly $100,000 to report. Sell after it and she shelters $250,000, leaving roughly $350,000. Same house, same buyer, same price. The difference is which side of one date the closing lands on.
For 2026, a single filer at or below $109,000 pays the standard $202.90 Part B premium with no Part D surcharge. Joint filers are clear at or below $218,000. Cross into the first tier and Part B goes to $284.10, an $81.20 surcharge, plus $14.50 for Part D. At the top tier, $500,000 single or $750,000 joint, Part B reaches $689.90 with a $91.00 Part D surcharge added. Don’t count on an appeal to undo it. SSA-44 exists for income that dropped, and a home sale you chose isn’t a qualifying event. Her husband’s death is one. But an accepted appeal still has to include the taxable gain in her projected income, so it won’t erase what the sale created.
Before You List
Here are three steps to take before you decide to sell:
- Get your Section 121 eligibility confirmed in writing. Twenty-four of the last 60 months, as your principal residence. Second homes, rentals and recently converted rentals don’t qualify cleanly.
- If you’re widowed, find the second anniversary of your spouse’s death and work backward from it. That date, not the market, sets your exclusion.
- Add up your basis before you assume the gain. Decades of capital improvements raise it, and selling costs reduce what you realize. If a taxable slice still crosses a bracket, an installment sale can spread it across tax years.
For many longtime homeowners, the exclusion handles the whole thing. The ones who get hurt are usually those who never checked, or who missed a date they didn’t know was running. Find your numbers first. Then decide whether you actually want the condo.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.