“For People Going Into Retirement, This Is a Gift.” A 65-Year-Old With $1.5 Million Can Now Generate $74,445 a Year Before Even Thinking About Social Security
A financial strategist says retirees are sitting on an opportunity that did not exist a decade ago, and the math behind it changes how much risk a retirement portfolio actually needs to take.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Financial strategist Lance Roberts, speaking on Thoughtful Money with Adam Taggart, put it plainly: “For people going into retirement, this is a gift. I mean, I can now take $1 million in my retirement, pick up 5% a year. There’s $50,000 of my income I don’t have to worry about.”, according to Thoughtful Money with Adam Taggart
The choice retirees faced for over a decade, take equity risk or accept almost nothing on cash, is no longer the only option. Government bonds now pay enough that a meaningful piece of retirement income can come from Treasuries alone, before Social Security is layered on top.
TINA Is Done, According to Roberts
Roberts argues the “There Is No Alternative” trade, which pushed savers into stocks because cash and bonds paid nothing, has reversed. Roberts said, “The Tina trade is now over because the alternative is I can just sit in cash money markets right now and get over 3%.” He added that he can “buy Treasuries in the 5 to 7 year duration, pick up 4.5%.”
On the institutional side, pension funds and insurance companies typically target roughly 7% annual returns, according to Thoughtful Money with Adam Taggart. Roberts noted: “Now I can go buy Treasury bonds at 5%. I’ve got to make 2% out of my equity side, according to Thoughtful Money with Adam Taggart. So all of a sudden I can vastly reduce my risk curve on the equity side.” The same logic applies to individual retirees.
Where Yields Actually Sit Right Now
Roberts is describing an unusual moment, not a routine one. The benchmark 10-year Treasury yield was 4.94% on September 17, 2026, which sits at the 97.6th percentile of its trailing-year range. Over that same trailing year, the high was 5.01% on September 16, 2026, the low was 3.97% on February 27, 2026, and the average was 4.3%, according to Thoughtful Money with Adam Taggart.
The 10-year is also up 0.23 from a month ago. The rate Roberts calls a gift is essentially at the top of what the past year has offered.
Our Illustration: $1.5 Million at Today’s Long Yield
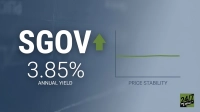
Here is our own updated version of Roberts’s example, scaled to a larger sum and using a live market reading rather than his round number. Our editor read a benchmark 10-year Treasury yield of 4.963% from CNBC’s live US10Y Tradeweb quote at 9:30 AM Eastern on September 21, 2026. Applied to a hypothetical $1,500,000 principal, that produces $74,445 in annual income.
Treasury yields move throughout each trading day and over time. The 4.963% figure is a snapshot, not a fixed or guaranteed forward rate for any reader. A Treasury sold before maturity can also be worth more or less than the price paid for it.
Why This Reframes Retirement Income
The income in our illustration comes from government-backed bonds alone, before any Social Security benefit is added.
Treasury interest is taxable at the federal level but exempt from state and local income tax. For a retiree in a high-tax state, that exemption meaningfully improves the after-tax take from Treasury coupons relative to CDs or corporate bonds of similar yield.
The larger appeal Roberts describes is qualitative. Meeting a chunk of an income target with government bonds, generally lower risk than equities, means less of the plan depends on stock market returns. The equity side can then take less risk to hit the overall goal, exactly the point he made about the institutional 7% target, according to Thoughtful Money with Adam Taggart.
What Retirees Can Actually Do With This
- Price the income target first. Write down the annual dollar figure your plan needs from savings, then work backward at today’s Treasury yields to see how much bonds alone can carry.
- Separate cash, short bills, and intermediate Treasuries. Roberts split cash money markets at over 3% from 5 to 7 year Treasuries at 4.5% for a reason: each plays a different role.
- Factor in the state tax angle. If you live in a state with income tax, remember Treasury interest is exempt from state and local income tax when comparing yields across instruments.
- Decide what job the equity portion has. If bonds now do more of the income work, the stock allocation can be sized to what is actually needed beyond that, rather than stretched to fill a gap cash and bonds used to leave.
Today, retirees have a real alternative to equity risk. Whether current rates hold is a separate question. Right now, this is what the market is paying.
Contact [email protected] for any questions or corrections.
AJ spent 10 years writing about financial markets at The Motley Fool. His coverage centers on technology stocks and the broader macroeconomic trends, from interest rates to geopolitics, that shape where markets are headed next. AJ is drawn to the stories where big-picture economics and individual companies collide.