Her Doctor Prescribed Aricept “Just in Case” After a Bad Memory Test. The Medigap Underwriter Read the Prescription as Dementia
One prescription fill her doctor wrote as a precaution quietly flagged her Medigap application as a dementia case, even though no diagnosis existed. What an underwriting algorithm sees in your pharmacy record can override everything you write on the health…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

A 70-year-old woman decides to leave her Medicare Advantage plan, applies for Medigap before making the switch, and gets turned down. She has no dementia diagnosis. She answered every question on the application truthfully. What sank her was a single pharmacy fill her own doctor wrote “just in case” after a bad memory-screen result.
This scenario matters only for a narrow group: those applying for Medigap outside the one-time federal open-enrollment window or a guaranteed-issue right. Inside that window, health history is irrelevant. Outside it, in most states, an automated prescription record can end the application before a person reads it.
How a “Just in Case” Trial Could End an Application
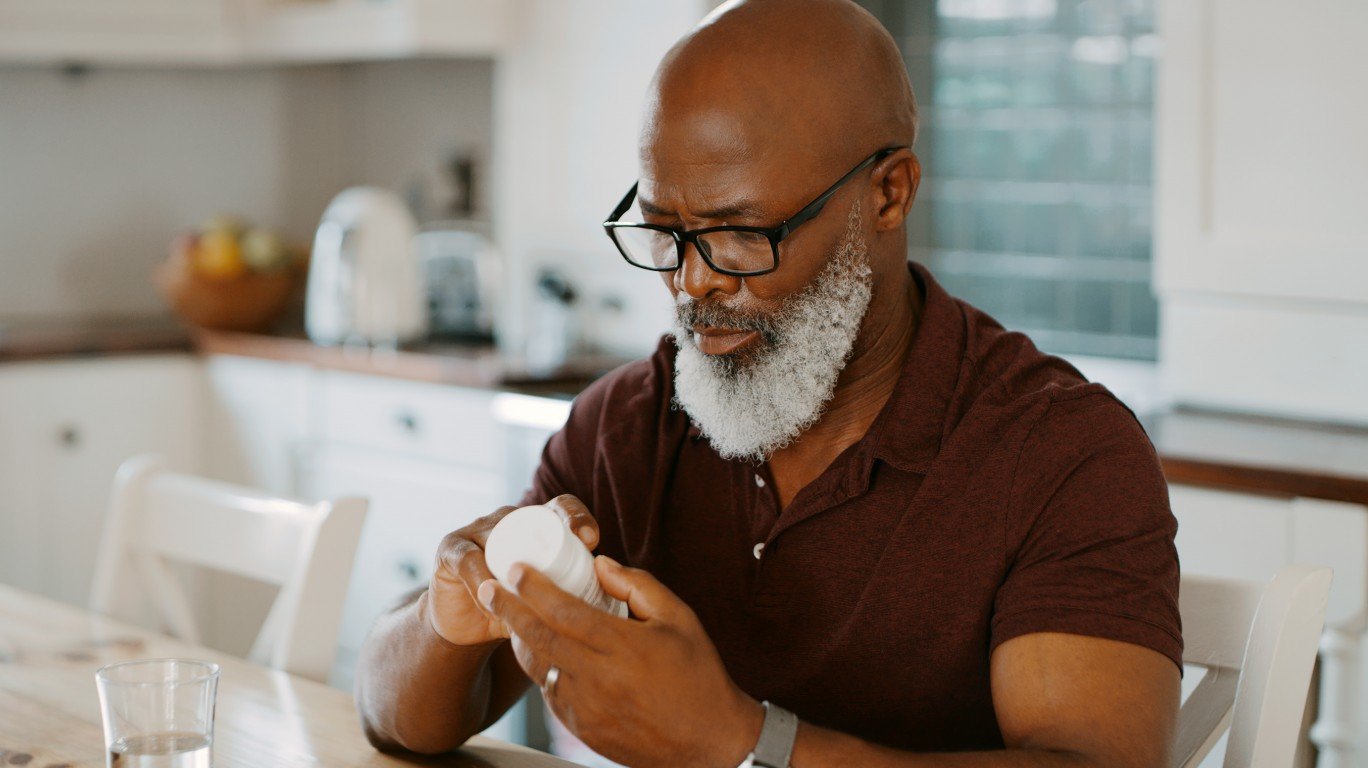
Her physician saw one disappointing cognitive screening and prescribed donepezil, sold under the brand name Aricept. She filled it once, felt side effects, and stopped. Months later, on a Medigap application, she checked “no” next to dementia, because no clinician had ever diagnosed her with it.
The underwriter did not need her answer. Donepezil is FDA-approved to treat dementia of the Alzheimer’s type, and that specificity is exactly what an automated underwriting engine looks for. Physicians do prescribe cholinesterase inhibitors off-label for mild cognitive impairment, but the pharmacy record shows only the drug, not the reason.
Published carrier materials treat the drug as shorthand for the condition. UnitedHealthcare/AARP enrollment materials map Aricept and generic donepezil to “Alzheimer’s disease or dementia” and treat an applicant as ineligible when a clinician prescribed medication for those conditions within the relevant lookback period. Mutual of Omaha’s underwriting guide similarly lists donepezil among medications associated with uninsurable conditions. These are carrier-specific rules, not a universal Medigap standard, but the two carriers involved sell a large share of individual Medigap policies.
Why the Health Question Does Not Protect Her
Underwritten Medigap applications almost always include authorization to pull a prescription-history report. The leading vendor, Milliman IntelliScript, collects fill data from pharmacies, insurers, and pharmacy-benefit managers once the applicant green-lights the request, and its product materials say customers can see fills quickly. Ask for your IntelliScript report if you have applied before. If this is your first time, review your pharmacy claims instead.
So a truthful “no” to the dementia question does not make the donepezil fill disappear. A prescription written but never filled generally would not create a pharmacy claim, though it can still show up through medical records. Even one prescription fill can trigger a decline or a need for medical records, depending on the provider.
Who This Actually Concerns
The federal Medigap Open Enrollment Period runs for six months, starting the first month a beneficiary has Medicare Part B and is 65 or older. Inside that window, carriers cannot deny coverage or price it up because of health history. Certain guaranteed-issue triggers, such as a Medicare Advantage plan leaving the service area or a trial-right return within the first year, work the same way.
State protections go further in some regions. Connecticut and New York command ongoing guaranteed issue. Massachusetts asks for an annual guaranteed-issue period, but many of its insurers support continuous enrollment. The state of Maine requires each insurer to offer at least one month each year when anyone can buy Plan A. Other states include narrower switching flexibility, and most applicants outside these parameters could still face an uphill battle: medical underwriting.
What to Do Before the Application Goes In
Do not stop a medically appropriate prescription to clean up an insurance file. That trade is bad medicine and rarely helps the application anyway, because the historical fill still shows.
Three actions matter before submitting:
- Ask the prescribing physician to document the actual clinical reason. If the trial was for mild cognitive impairment, an abnormal screening score, or another indication, get that in the chart in plain language. It will not erase the pharmacy record, but it gives a broker or appeals reviewer something to attach.
- Pull the IntelliScript consumer report and read it. Applicants can request their own file and dispute wrong patient, drug, or fill data. Fixing an error before a carrier sees it is easier than reversing a decline.
- Use a broker who compares carrier underwriting guides before any formal application. One carrier’s automatic decline can be another carrier’s request for records or a rated offer. A formal decline stays on file and can complicate the next attempt, so the first submission should go to the carrier most likely to accept.
And never cancel existing coverage, Medicare Advantage or otherwise, until the new Medigap policy has been issued and accepted in writing. Her doctor saw a bad memory test and reached for caution. The pharmacy record preserved only the drug name and she needed time to sort it out.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.