Inherit an IRA From a Parent? You Have 10 Years to Empty It and a 25% Penalty if You Miss a Withdrawal
Most adult children who inherit a parent's IRA have no idea a decade-long countdown started the moment the account owner died, and the IRS built a stiff penalty into the clock for anyone who misses a step.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Your father dies in 2026 and leaves you his $500,000 traditional IRA. You do nothing. On December 31, 2036, the IRS assesses a 25% excise tax on the balance you should have withdrawn, plus ordinary income tax on every dollar that finally comes out.
The SECURE Act’s 10-year rule killed the “stretch IRA” for most adult children who inherit a parent’s retirement account. Nonspouse beneficiaries have a decade to empty a traditional IRA, and a stiff excise tax waits on anything they miss.
Where the Rule Lives and Who It Catches
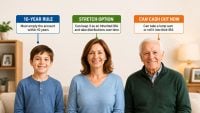
The rule applies to account owners who died after December 31, 2019, under the SECURE Act of 2019, with final IRS regulations issued in 2024. If you are the child, sibling, friend, or unrelated heir of the account owner and you do not fit one of the narrow exceptions below, you are a “non-eligible designated beneficiary.” The account balance must reach zero by December 31 of the 10th year after the owner’s death.
Suze Orman put it plainly on her podcast: “you have 10 years to wipe that account clean. You can no longer take it over the beneficiary’s entire lifetime, called a stretch IRA, which you could before 2020.”
Annual RMDs During the 10 Years, Too
If your parent had already started required minimum distributions before dying, you must continue annual RMDs in years one through nine, based on your own single life expectancy, and still empty the account by year 10. The IRS confirmed you cannot wait until year 10 to withdraw everything if the owner had already begun RMDs. The requirement is live for tax year 2025 and beyond.
If your parent died before their RMDs began, skip the annual withdrawals and time distributions however you want, provided the balance hits zero by year 10.
How the 25% Penalty Drops to 10%
Miss a required distribution and SECURE 2.0 imposes a 25% excise tax on the shortfall, which drops to 10% if corrected promptly. That correction means taking the missed amount and filing Form 5329 within the IRS’s two-year window. Before SECURE 2.0, the same mistake cost 50%.
Worked example for tax year 2026: your mother dies at 78 with a $400,000 traditional IRA, and you are her sole beneficiary at age 55. Your single life expectancy factor is roughly 31.6, producing a first-year RMD near $12,660. Skip it, and the IRS bills you about $3,165 in excise tax on top of the income tax you will eventually owe when the money comes out.
Roth Inherited IRAs Get the Same Clock
In a non-eligible designated beneficiary inherited Roth IRA, the account also has to be wiped clean in 10 years. The strategy flips: leave the Roth alone for the full 10 years so the money grows tax-free, then take it all out at the end. For an inherited traditional IRA, spread withdrawals across all 10 years so a lump sum in year 10 does not stack on top of your peak earning income and shove you into a higher bracket.
Exceptions That Still Get the Stretch
Five categories of “eligible designated beneficiaries” can still stretch distributions over their own lifetimes: surviving spouses, minor children of the account owner (the 10-year clock starts once they reach majority), disabled individuals, chronically ill individuals, and beneficiaries less than 10 years younger than the decedent. Everyone else, which covers most adult children, is on the 10-year clock.
Three Moves Before Year 10
First, confirm whether your parent had started RMDs, because that determines whether you owe annual withdrawals now or only a year-10 payout. Second, model each withdrawal year against your own taxable income; a $40,000 annual distribution during a low-earning year costs far less than $400,000 dumped into a high-earning one. Third, do not roll an inherited IRA into your own IRA unless you are the spouse. Nonspouse rollovers are treated as a full taxable distribution the day they hit your account.
This is exactly the kind of math worth running with a fiduciary advisor or CPA before the first December 31 deadline arrives. The inherited IRA clock is one of nine IRS rules that quietly drain retirement accounts, and we mapped the rest in a free tax trap guide here.
Data Sources
- Kiplinger, “The Hidden Costs of Inheriting an Investment Portfolio”: source for the 10-year distribution rule for nonspouse beneficiaries and the 25% excise tax (reducible to 10%) on missed withdrawals.
- Suze Orman’s Women & Money podcast: source for the plain-English framing of the stretch IRA’s elimination and the strategic difference between inherited Roth and traditional IRAs.
- Suze Orman podcast segment on inherited IRA mistakes: source for the requirement that beneficiaries continue annual RMDs when the original owner had already started them.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)