Your ANOC’s First Page Says $0 Premium Again for 2027. Page Six Says the Hospital Copay Went From $295 a Day to $395, in the Same Size Type
Your Medicare Advantage plan kept its $0 premium for 2027, but buried deeper in that ANOC packet is a number that could cost you hundreds more for a single hospital stay, and most enrollees never read that far.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A woman on a Medicare Advantage HMO pulls the 2027 Annual Notice of Change (ANOC) out of the mailbox in September, flips to the summary page, and sees the same three characters she saw last year: $0 monthly plan premium. She almost tosses the packet. Then she gets to page six, where the inpatient hospital line shows the per-day copay rising from $295 to $395 for the plan’s specified range of days. The premium held flat. The cost of actually using the plan rose.
If you have a Medicare Advantage plan and your 2027 ANOC has already arrived (plans have to deliver it by September 30 under 42 CFR §422.111), the hospital copay line is one of the first places worth looking. A $0 premium does not translate to zero changes.
What a $0 Premium Actually Buys
The plan premium covers only the price of carrying the Medicare Advantage card, separate from the price of using it. Every enrollee still pays the Part B premium to Medicare, which is $202.90 a month in 2026, up from $185.00 in 2025. On top of that, the plan sets its own cost sharing: hospital copays, specialist visits, outpatient surgery, skilled nursing, ambulance, drugs, and the annual out-of-pocket maximum. Any of those can change on January 1 while the headline premium stays flat.
That is the trick baked into a $0-premium comparison. The number on the front of the ANOC held flat. The lines that moved sit five pages deeper.
Run the Hospital Math
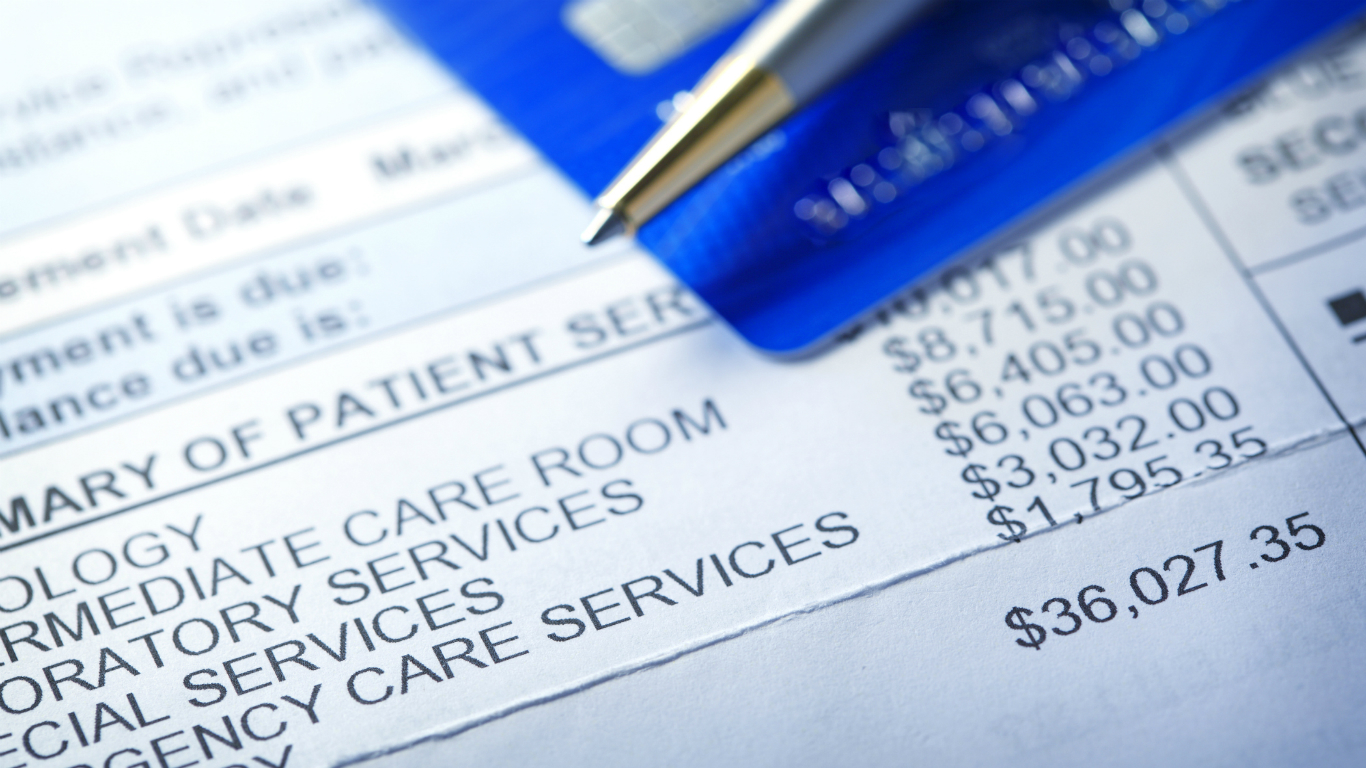
Take the inpatient copay in the scenario. If the charge applies to days 1 through 5 of an admission, a five-day hospital stay under the 2026 plan cost $1,475. The same stay under the 2027 plan costs $1,975. That is a $500 increase for one admission, triggered by nothing the member did.
Two things make that number worse than it looks. First, the day count often restarts with a later admission in the same year, so a second hospitalization stacks another copay block on top. Second, the plan’s medical out-of-pocket maximum may have moved too. Check that line on the same page. If the cap went up, the ceiling on a bad year went up with it.
The member only owes the higher amount if she is actually hospitalized. But that is the whole point. A $0-premium tells you very little about the plan’s actual costs. The ANOC reveals what the sick year now costs.
What Else Moved While the Premium Sat Still
Once the hospital line is understood, the same logic applies down the page. The following details are worth comparing side by side against last year’s Evidence of Coverage:
- Specialist and outpatient-hospital copays.
- Skilled nursing per-day copays (the plan’s version of Medicare’s $217 per day for days 21 through 100 in Original Medicare).
- Ambulance cost sharing.
- The medical out-of-pocket maximum.
- Drug deductible, tier placements, and preferred-pharmacy rules.
- Any supplemental benefit being trimmed or removed.
Any one of those lines can add thousands a year without the premium moving a dollar, which is the whole reason we mapped the surcharges, coverage gaps, and copay traps in a free Medicare guide here.
Income context matters here. The 2027 Social Security COLA is tracking in the mid-3% range based on two of three Q3 months. A one-time $500 hospital copay increase eats several months of that raise for the average beneficiary. A copay change that never touches the premium can still outrun the COLA.
Use the Window That Closes December 7
Annual Enrollment runs October 15 through December 7, with any change effective January 1. Three actions are worth doing before then:
- Put the 2026 EOC next to the 2027 ANOC and compare the inpatient hospital, skilled nursing, and out-of-pocket-maximum lines directly. If any one of those moved materially and you have recurring medical use, model at least one realistic admission under the new numbers.
- Re-check the network. Confirm your primary hospital, your specialists, and your preferred pharmacy are still in-network for 2027 before you decide to stay. Networks move without touching the premium either.
- If you are considering switching back to Original Medicare plus a Medigap policy, verify your state’s guaranteed-issue rules before you drop the Advantage plan. Outside the initial six-month Medigap window, most states let insurers medically underwrite, and a denial after you have already switched is the wrong time to find out.
The first page of the ANOC tells you what it costs to keep the insurance card. Page six of the letter tells you what it costs to use it.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.