My Microsoft Price Prediction Looks Well Beyond the Current AI Cycle
Azure just crossed $100 billion in annual revenue and Microsoft's commercial backlog dwarfs what most investors track, yet the stock's biggest risk has nothing to do with AI demand fading.

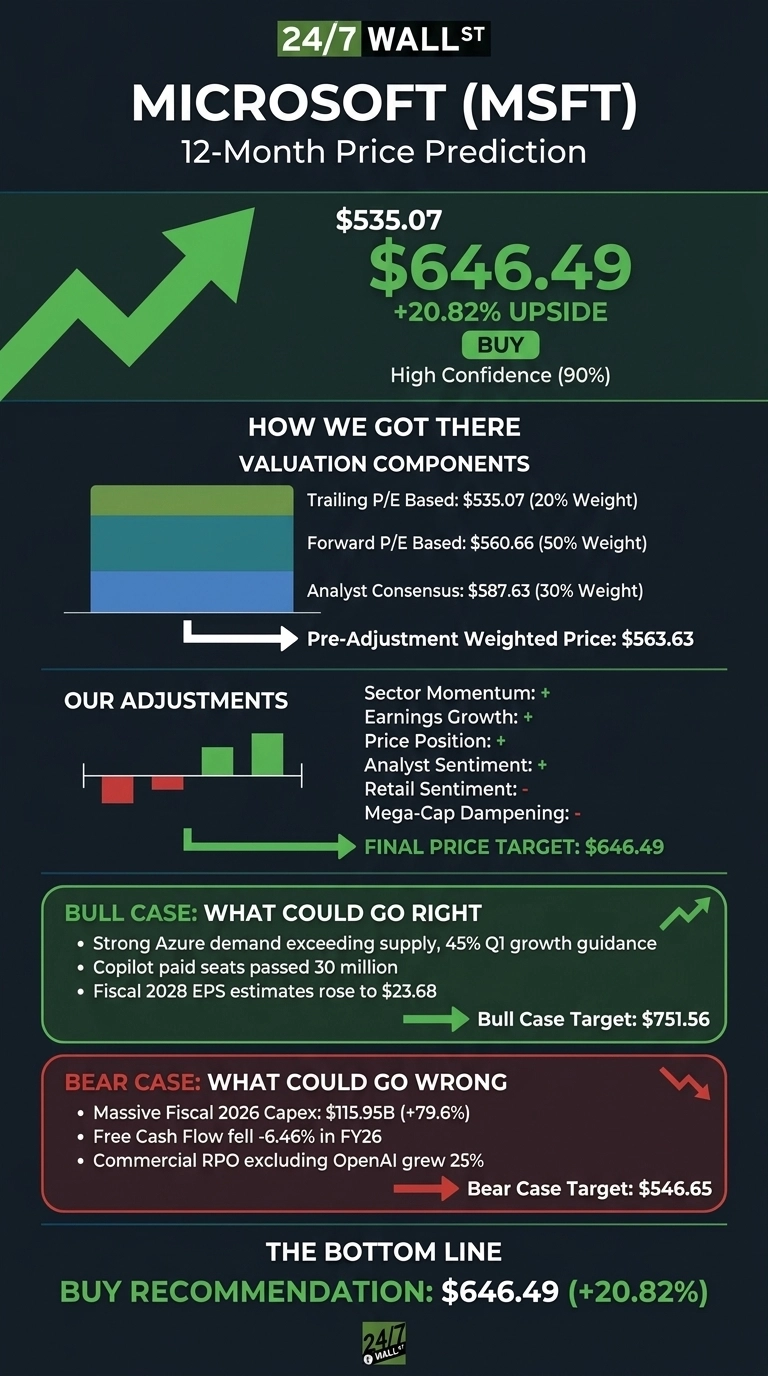
The 24/7 Wall St. price target for Microsoft (NASDAQ:MSFT | MSFT Price Prediction) is $646.49 over the next 12 months. That means 20.82% upside from the latest close of $535.07. Our model rates the stock a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $535.07 |
| Price Target from 24/7 Wall St. | $646.49 |
| Upside/Downside | 20.82% |
| Recommendation | BUY |
| Confidence Level | 90% |

My thesis looks past a single AI spending wave. Microsoft has a $678B commercial backlog,
Azure topped $100B in annual revenue for the first time, and Copilot is moving toward what management calls a seat-plus-usage model. Those are recurring enterprise revenue streams built to survive any one hype cycle.

A 37% Rally Since July Puts Microsoft Near Its High
Microsoft has gained 4.33% over the past week, 9.83% over the past month and 12.36% year to date. From July 13 through October 9, shares rose 37.11%. The stock now sits just below its 52-week high of $549.20 and well above its low of $348.54.
The rally started with the fiscal Q4 report on July 29. Revenue of $90.01B beat the $87.63B consensus, and non-GAAP EPS of $4.74 exceeded the $4.24 estimate. Azure grew 43%. On Monday, Barron’s reported that an AI warning from Microsoft’s CEO drew little reaction from cybersecurity stocks.
Why Bulls See $750 Within Reach
Our bull case hits $751.56. CFO Amy Hood said “demand continues to exceed available supply,” and management guided first-quarter Azure growth to around 45% in constant currency. Microsoft 365 Copilot passed 30 million paid seats.
Analysts have been raising forecasts: fiscal 2028 EPS estimates rose to $23.6759 from $22.6278 90 days ago. Wall Street has 14 Strong Buy, 39 Buy and 2 Hold ratings, with no Sells, and a consensus target of $587.63.

Capex Is the Risk Worth Watching
The bear case lands at $546.65. Fiscal 2026 capex jumped 79.62% to $115.95B, and free cash flow fell 6.46%. Fiscal 2027 capex is expected to hits about $175 billion. Excluding OpenAI, commercial RPO grew a more modest 25%. Q4 EPS also included a $3.20B gain from the Anthropic investment.
Operating cash flow rose 34.35% to $182.94B, and Hood noted that spending has moving toward short-lived chips that Microsoft can slow down if demand cools.
How Microsoft Compares to Alphabet and Amazon
Alphabet (NASDAQ:GOOGL) competes head to head for enterprise AI cloud customers. Google Cloud grew 82%, but Alphabet’s low trailing P/E is boosted by a $99.03 billion equity gain, and its quarterly free cash flow came in at negative $5.855 billion.
Amazon (NASDAQ:AMZN) runs AWS, Azure’s largest rival. AWS grew 37%, slower than Azure, yet Amazon trades at a higher earnings multiple and posted negative trailing free cash flow of $7.6 billion.
| Company | Trailing P/E | Latest Cloud Growth |
|---|---|---|
| Microsoft | 30 | 43% |
| Alphabet | 16 | 82% |
| Amazon | 36 | 37% |
Microsoft pairs a middle-of-the-pack multiple with positive free cash flow. Against this peer group, our target looks reasonable.
Microsoft Price Prediction 2026-2030
The 24/7 Wall St. price target of $646.49 has a buy rating and 90% confidence. The backlog grounds the thesis.
The bull thesis holds as long as Azure keeps growing above 40% and Copilot seat additions keep rose. Rising capex alongside flat backlog growth outside OpenAI would weaken the thesis. For now, the fundamentals support the model’s target.
The 24/7 Wall St. price target model projects where Microsoft could trade in the years ahead, assuming current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (December) | $562.94 |
| 2027 (October) | $647.36 |
| 2028 (October) | $738.64 |
| 2029 (October) | $817.69 |
| 2030 (October) | $875.72 |
The projections assume Microsoft keeps doing its current strategy. Faster growth in Copilot usage revenue could push results higher, while a decline in AI infrastructure demand could pull them lower. The expansion runs on more than chips, which is why we highlighted seven power, cooling, and networking suppliers behind the data centers in a free report you can grab here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.