Suze Orman’s Strategy for Building Real Wealth: Skip the 401(k) After the Match
Suze Orman argues that the wealthiest people she knows share a quiet habit most financial advisors never mention, and it has nothing to do with maxing out a 401(k). Understanding why could change the order in which you invest every…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
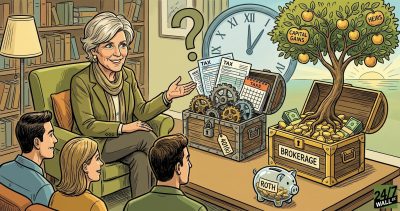
Suze Orman says the wealthy keep much of their money in an ordinary brokerage account. On her Women & Money podcast, she explained:
The majority of people out there who accumulate massive amounts of wealth, they have their money not just in a retirement account, but they invest in a regular investment account at usually a brokerage firm. And that is how they accumulate massive amounts of money.
Pre-tax 401(k) dollars are taxed as ordinary income when withdrawn. They also face forced withdrawals later in life and can leave heirs with a tax bill. IRS publications back up each of these rules.
First, Grab the Match and Fund a Roth
Her argument covers only pre-tax money contributed after the employer match. Her first priority is a Roth: “There is no better investment or retirement account that you can have than a Roth IRA. A backdoor Roth if you can do one, or a Roth 401, 403 or TSP if you can invest that way. That should be your number one priority.”
She is equally firm about the match: “I will always tell you to invest up to the point of the match in any retirement account, bar none.” A match gives an instant return on every dollar invested.
Losses Only Pay You Back Outside a 401(k)
When a fund loses money inside a 401(k), your tax return gets nothing. In a taxable account, Orman notes, you can sell a losing investment and deduct up to $3,000 per year from taxable income.
The IRS confirms the $3,000 limit for individuals in Publication 544. For married people filing separately, the cap is $1,500. Losses above the annual limit carry over to future tax years.
Suppose a fund drops during a bad year. You sell it and buy a substantially different fund, avoiding the wash-sale rule. You deduct the loss up to the annual limit and carry the rest forward. The same loss inside a 401(k) yields no deduction.
Capital Gains Rates Beat Ordinary Income Rates
Every dollar withdrawn from a pre-tax 401(k) is taxed as ordinary income. In a brokerage account, gains on investments held longer than a year get long-term capital gains rates, typically lower than ordinary income rates. Orman says, “That can be a very, very big difference from ordinary income tax.”
Your tax rate in retirement versus today determines this debate. If your bracket drops sharply after you stop working, the upfront 401(k) deduction wins. If your bracket stays the same or rises, deferral only delays a bill you could have paid at capital gains rates. Orman expects the latter: “Don’t count on being in a lower income tax bracket when you retire.”
Orman: Forced Withdrawals Begin at 73
Orman notes pre-tax retirement accounts require withdrawals starting at age 73, whether you need the money or not. The IRS confirms Orman’s figure, setting this required beginning age at 73 for tax years 2023 and later in Publication 590-B. These withdrawals can push you into a higher bracket. A brokerage account has no required distributions. The quiet years between a last paycheck and that first required withdrawal often represent the lowest tax rates a retiree will ever see, and we explain how to use that window for Roth conversions in a free guide here.
What Your Heirs Actually Inherit
In Orman’s example, someone invests $50,000 in a brokerage account that grows to $1 million. Orman says heirs get a stepped-up cost basis of $1 million, so they owe no income tax on the growth if they sell immediately.
In Orman’s 401(k) version, the same $50,000 grows to $1 million. Orman estimates the heirs would pay ordinary income tax on about $100,000 a year over 10 years. That figure is illustrative. The actual tax owed depends on each heir’s own tax bracket and the rate at which they draw down the account. IRS Publication 17 confirms that beneficiaries must include taxable distributions in gross income.
Run These Checks Before Moving a Dollar
- Orman’s first step is contributing enough to capture the full employer match, which she treats as the highest-priority dollar in any retirement plan.
- Her next step is funding a Roth IRA or Roth 401(k) before putting pre-tax dollars past the match.
- Compare your current marginal bracket with your expected retirement income. A big drop favors pre-tax money; a flat or rising bracket favors Orman’s approach.
- Check your 401(k) fund menu and expense ratios. High fees make a stronger case for a low-cost brokerage account.
Orman ends with a discipline test for anyone considering this approach: “If you are not disciplined to invest and save money on your own, forget about this strategy.”
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.