The Insurer Sent $80,000 to Rebuild Her Fire-Damaged Kitchen While She Was in the Nursing Home on Medicaid. The Check Sat Unspent for 10 Months, and That Is When the State Counted It
An $80,000 insurance check sat in a nursing home resident's account, earmarked for her fire-damaged kitchen, and then a federal rule turned it into a Medicaid catastrophe. The calendar, not the contractor, decided her eligibility.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
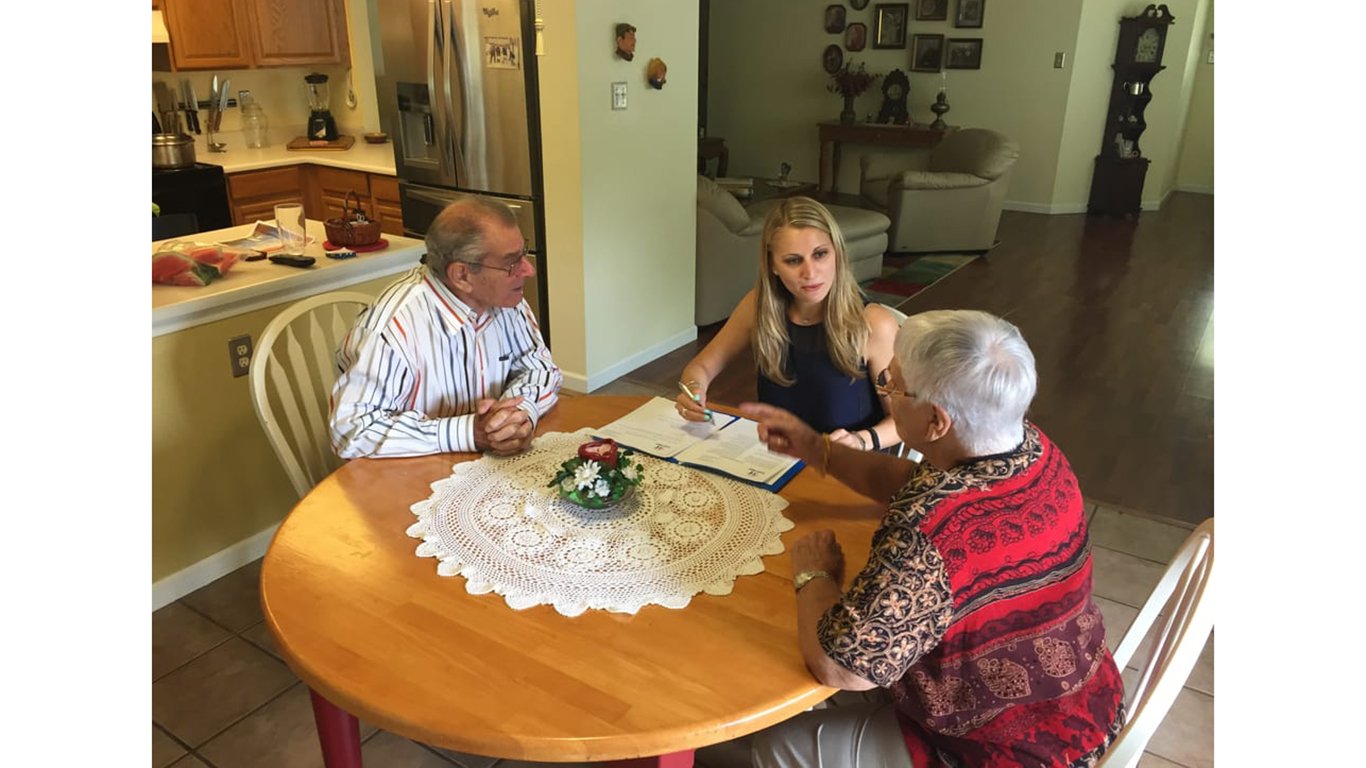
Picture a widow living in long-term care, with Medicaid paying the bill. Back at her house, a kitchen fire has charred the cabinets and the ceiling. Her homeowners insurance company sends a check for $80,000 to rebuild. The family deposits it, calls contractors and waits. Ten months later the money still sits in her account, and the state counts it as an asset.
A federal rule causes that. Under Social Security’s 20 CFR 416.1232, cash received to repair or replace an excluded resource doesn’t count as a resource for nine months from arrival. After that, “Any of the cash (and interest) that is not used to repair or replace the excluded resource will be counted as a resource beginning with the month after the 9-month period expires.” For this widow, that happens to be month 10.
How 20 CFR 416.1232 Shields an $80,000 Insurance Check
The rule comes from Supplemental Security Income regulations, which many state Medicaid programs use when counting resources for older applicants. Mississippi, for example, follows SSI financial eligibility rules for these Medicaid groups.
The federal health insurance program for Americans 65 and up limits skilled nursing facility coverage to 100 days in each benefit period and doesn’t cover custodial care if it’s the only care you need. For someone who qualifies, Medicaid can pick up the long-term-care bill, and that’s when the resource rules matter.
Her house can remain excluded while she intends to return to it and her equity stays within her state’s limit. For 2026, states generally set that home-equity ceiling between $752,000 and $1,130,000. Because the insurance money is meant to repair that excluded home, the cash and the interest it earns can remain excluded during the allowed period.
Month 10: When a Kitchen Fund Collides With a $2,000 Limit
The check arrives in month one. For the next nine months, money still set aside for the repair stays out of the resource test. After that, any unused amount becomes countable unless she qualifies for an extension.
That’s a big number against a small ceiling. Most states let a single nursing home applicant hold only $2,000 in countable assets in 2026. An untouched kitchen fund blows past that limit, and she loses eligibility until the excess is gone. Meanwhile, the facility sends her the bill.
Families stumble into this trap because contractors book up, permits stall, and insurance companies argue over line items. Everyone assumes money earmarked for repairs stays protected. The regulation protects it for a set period, and the clock starts on the date she received the check, regardless of when someone signed a contract.
A 9-Month Good Cause Extension Requires a Paper Trail
The rule allows a second chance. The initial period can stretch for a reasonable period up to an additional nine months if the owner shows good cause. Social Security’s operations manual defines good cause as circumstances beyond the person’s control that prevent repair or replacement. Its example: a hurricane-ravaged area with too few contractors.
The extension applies only if she intends to use the cash or in-kind replacement items to repair or replace the property. If the family decides to sell the house instead, the funds count starting the month they report the change of intent.
For damage in a presidentially declared major disaster area, the government can add up to 12 months more, for a maximum of 30 months. The manual warns caseworkers not to grant that automatically, noting that “18 months is usually sufficient time” even after major disasters. A single-house kitchen fire won’t qualify.
Families who win extensions bring documentation, typically including:
- The insurer’s letter showing the payment was for repairs and the date the money arrived
- Bank records showing the funds in a separate account, untouched for anything else
- Contractor bids, signed contracts, and emails documenting cancellations or backlogs
- Permit applications and inspection delays from the local building department
- A written statement that she plans to restore the home and return to it
Families who submit that file before month nine ends give the caseworker time to rule before the money becomes countable.
State rules can shift the math. Federal regulations let states adopt resource methods that are no more restrictive than SSI’s, and some states write their own exceptions or extension procedures into their Medicaid manuals. The state’s eligibility manual determines how much extra time a delayed renovation can get.
The $80,000 looked exactly the same on day one and in month 10. Same check, same purpose, same burned kitchen. Only the calendar changed, and Medicaid’s exclusion ran out before the contractor showed up.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.