Her Son Will Live Rent-Free in Her Rental House for Four Years After Losing His Job. In Her State, Medicaid May Count the $1,500 a Month He Never Paid as a $72,000 Gift
A widowed mother hands her son the keys to her rental house and tells him not to worry about rent. Years later, Medicaid may see that kindness as something else entirely.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
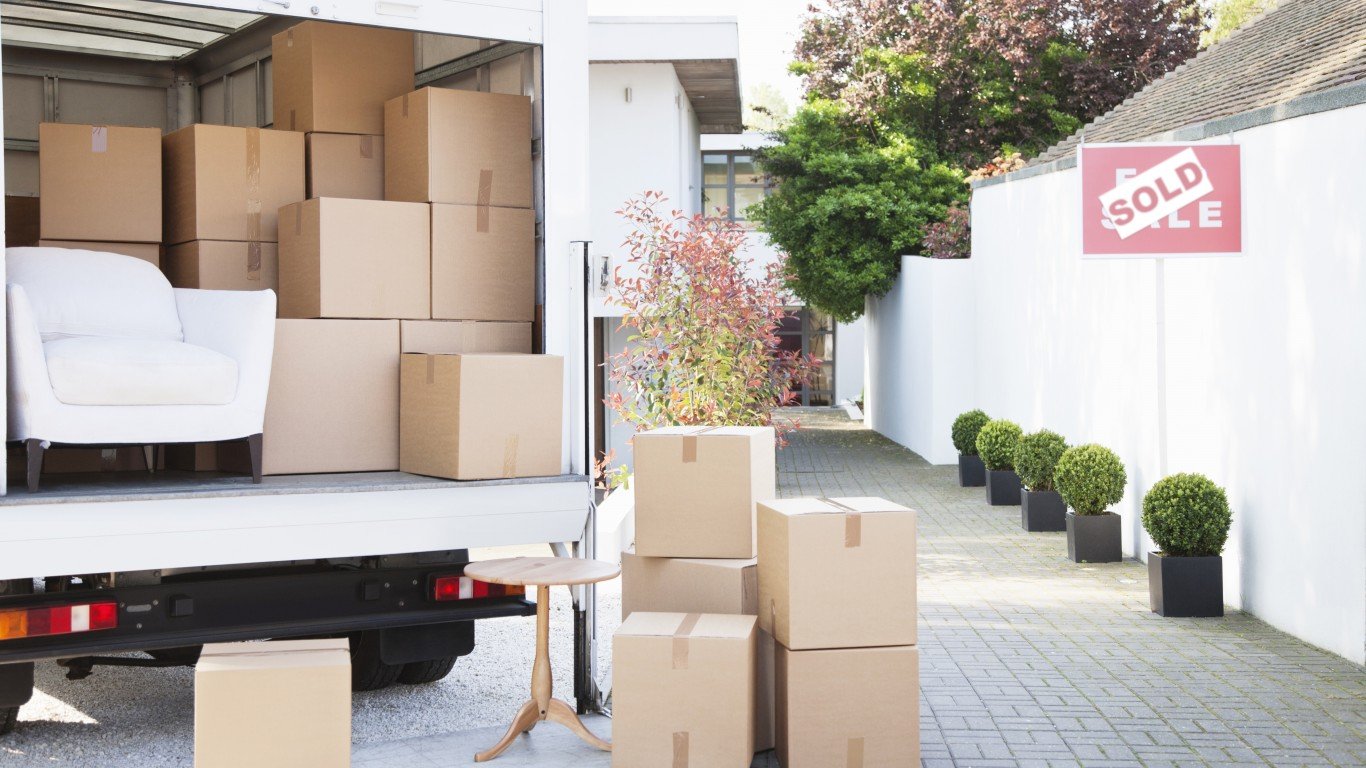
Picture a widowed mother who owns a small rental house across town. Her son loses his job, so she does what plenty of parents would do: she hands him the keys and tells him to forget about rent. Similar homes nearby rent for $1,500 a month, and he stays four years.
Over that stretch, she chose not to collect $72,000 in rent. Now suppose she later needs nursing home care and applies for Medicaid. Her state may treat that rent as a gift to her son, and gifts made inside the look-back window can delay her coverage.
How $72,000 in Rent Nobody Paid Can Become a Medicaid Gift
Medicaid is the joint federal-state program that pays for long-term nursing home care once a person’s assets run low. After a hospital admission, Medicare, the federal health insurance for people 65 and older, covers only short skilled nursing stays. When care bills run for years, Medicaid is usually the program paying them, and it wants to know what you gave away.
Federal Medicaid law defines assets broadly, including income or resources someone had a right to receive but gave up through her own action. States then apply that rule to specific transactions. In Indiana, for example, renting real estate for less than fair market value can create an uncompensated transfer based on the rent the owner gave up.
The same law penalizes transfers for less than fair market value made during the look-back period. If her state counts unpaid market rent as that kind of transfer, every month of free housing inside the window adds to the value she gave away. The penalty is a stretch of time when Medicaid won’t pay for her care, even if she qualifies on every other count.
The mother never wrote her son a check, and her bank statements look spotless. The transfer happened anyway, one unpaid month at a time.
States handle these arrangements differently. Some Medicaid programs expressly treat below-market rent as uncompensated value. Others apply different resource and transfer rules. The answer comes from her state’s Medicaid policy, not from whether a particular caseworker happens to dislike the arrangement.
Why the Rental House Itself Can Fail a Second Medicaid Test
The house can create a second problem. Real estate other than her home may count toward Medicaid’s resource limit unless a state rule protects it, and some income-producing property gets better treatment only when it actually produces a reasonable return.
A rental house producing $0 makes that argument harder. Depending on her state’s rules, the property itself may become countable even before Medicaid gets to the four years of free rent. Then the family has two problems: a transfer penalty tied to the rent and a countable asset that could block eligibility until it’s sold or spent down.
A Written Lease and Repair Receipts Strengthen the File
Families who document the arrangement from day one keep their options open. Files that hold up best usually include:
- A written lease signed by mother and son that states the rent, even if it’s reduced.
- Comparisons with similar homes for rent nearby, showing what fair market rent looked like.
- Records of any actual payments, made by check or bank transfer instead of cash.
- Written proof of rent discounts tied to real work. If the son fixed the furnace, handled repairs, kept up the yard or provided care, receipts and a signed agreement show he paid in services.
- The state’s Medicaid guidance on income-producing property, so the family knows which test the house has to pass.
A son who pays rent, or provides services the state recognizes as fair compensation under a documented agreement, gives the family something concrete to account for. Any uncompensated portion may then be smaller.
Timing matters too. Free rent given more than 60 months before a Medicaid application falls outside the look-back entirely. A healthy parent has more room to work with than one who’s already visiting nursing homes (this is one of several hidden government rules that quietly reduce retirement wealth, and we mapped out the rest in a free guide here: The Retiree’s Tax Trap Map).
No Check Changed Hands, but Medicaid Can Still Find the Transfer
Most families picture Medicaid gift problems as big, obvious moves, like signing over a deed or writing a large check to a grandchild. Free rent feels harmless because no money ever leaves her account.
Still, four years of free housing leaves a trail: a house in her name, a tenant who shares her last name, tax returns that show no rental income and a neighborhood where similar homes rent for $1,500 a month. A Medicaid reviewer can piece that together quickly.
The best time to sort this out is while the son is carrying boxes through the front door. Mom can still help him, but a written lease, a defensible rent and records of anything he provides in return leave far less for Medicaid to reconstruct years later. What feels like an informal family favor today can become a $72,000 gray area when nursing home care enters the picture.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.