At 70, She Will Pull $28,000 From Her IRA for Dental Implants Medicare Won’t Cover. Medicare Will Count the $28,000 as Income and Raise Her Premiums in 2028
A widow's dental implants will cost her twice: once at the dentist, and again two years later when Medicare sends a bill she never saw coming. The way she funds the procedure matters more than the procedure itself.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Consider a 70-year-old widow who needs $28,000 in dental implants. She plans to pay for them with a withdrawal from her traditional IRA. Medicare won’t pay for the implants. Two years from now, it will charge her more because she paid for them herself.
This rule hits single filers whose normal income falls within reach of Medicare’s first surcharge threshold. About 8% of Part B enrollees pay any surcharge. A retiree whose income falls well under the threshold can draw from an IRA for dental work and pay nothing extra.
Why Medicare Usually Won’t Pay for Implants
Medicare generally doesn’t cover routine dental care, including cleanings, fillings, extractions, dentures and implants. The exceptions apply only when the dental work is tied to a covered medical treatment. Examples include an oral exam before a heart valve replacement or organ transplant, an extraction to clear a mouth infection before chemotherapy, or treatment for complications from head and neck cancer care. Implants that replace failing teeth don’t meet any of those conditions.
Many Medicare Advantage plans offer extra benefits that Original Medicare does not cover, but the dental benefits differ from plan to plan. Some exclude implants outright. Others cap annual dental spending far below a multi-tooth implant bill.
Her $28,000 Withdrawal Still Counts as Income
Social Security calculates the income-related monthly adjustment amount (IRMAA) using modified adjusted gross income (MAGI). That’s adjusted gross income plus tax-exempt interest, including municipal bond interest. Her $28,000 traditional IRA withdrawal also counts as taxable income.
The Social Security Administration generally uses income from two years earlier, so her 2026 withdrawal will ordinarily affect her 2028 Medicare premiums. A withdrawal she takes in 2026 therefore sets her 2028 premiums.
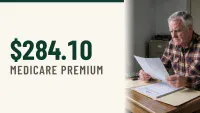
Suppose her baseline MAGI is $90,000. The withdrawal brings it to $118,000. In 2026, a single filer with income above $109,000 through $137,000 pays an extra $81.20 a month for Part B. That raises her premium from $202.90 to $284.10, or $974.40 more for the year. Part D adds $14.50 a month, or $174 a year. Together, the surcharges total $1,148.40.
The $974 covers Part B only and uses 2026 rates. Medicare hasn’t published its 2028 brackets yet. The thresholds rise with inflation, but she is $9,000 over the 2026 line. Between 2025 and 2026, the single threshold went up just $3,000, from $106,000 to $109,000.
Widowhood can make the problem worse. A married couple filing jointly faces a $218,000 threshold, compared with $109,000 for a single filer. Even if much of her household income remains intact, she has less room before Medicare’s surcharges begin.
She can’t appeal it away, either. Form SSA-44 lets beneficiaries ask for a lower surcharge after a life-changing event that lowered income, such as marriage, divorce, the death of a spouse, loss of income, and an employer settlement payment. A voluntary IRA withdrawal raised her income instead, so it doesn’t qualify.
Three Ways the Dental Payment Could Differ
- Cash savings. Taking money out of a savings or money market account adds nothing to MAGI. Her surcharge stays at zero.
- Taxable brokerage account. When she sells shares, only the capital gain counts toward MAGI. The rest of the sale proceeds don’t. Selling holdings with small gains could keep her under the threshold.
- An IRA withdrawal split across two tax years. Implant treatment usually happens in stages over several months. If she withdraws $14,000 in December 2026 and the other $14,000 in January 2027, her MAGI lands at $104,000 in each year. Both amounts fall below the 2026 threshold, assuming her other income stays unchanged.
In any one year, she has $19,000 of room under the 2026 threshold. She shouldn’t delay needed care to protect that room. Deferring treatment to avoid a one-year surcharge of $1,148.40 is a poor trade. Changing the withdrawal dates may help her avoid the surcharge, although she still needs to consider the income-tax consequences.
Before Scheduling the Procedure
- Get a written, staged estimate. Ask the dental office to list the surgical phase and the crown phase separately, with a date and dollar amount for each. Then, if the treatment schedule supports it, line up the IRA withdrawals so they fall in different tax years.
- Check coverage in writing. If she has a Medicare Advantage plan, ask the plan whether it covers implants and what its annual dental cap is. If she doesn’t, use open enrollment, which is underway now, to compare plans whose dental benefits include implants.
- Estimate 2026 MAGI before December. Add AGI so far, expected year-end income, and tax-exempt interest. If that amounts plus the withdrawal goes over $109,000, move part of the withdrawal into January or pay part of the bill from cash.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.