‘Just Don’t Pay Them’: Ramsey to Jobless Caller With $80,426 in Debt From a Manic Episode
Dave Ramsey told a jobless caller drowning in manic-episode debt to stop paying his cards and settle later. The plan skips the legal protection bankruptcy offers, and a hidden tax bill and one upcoming paycheck could decide whether it works.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
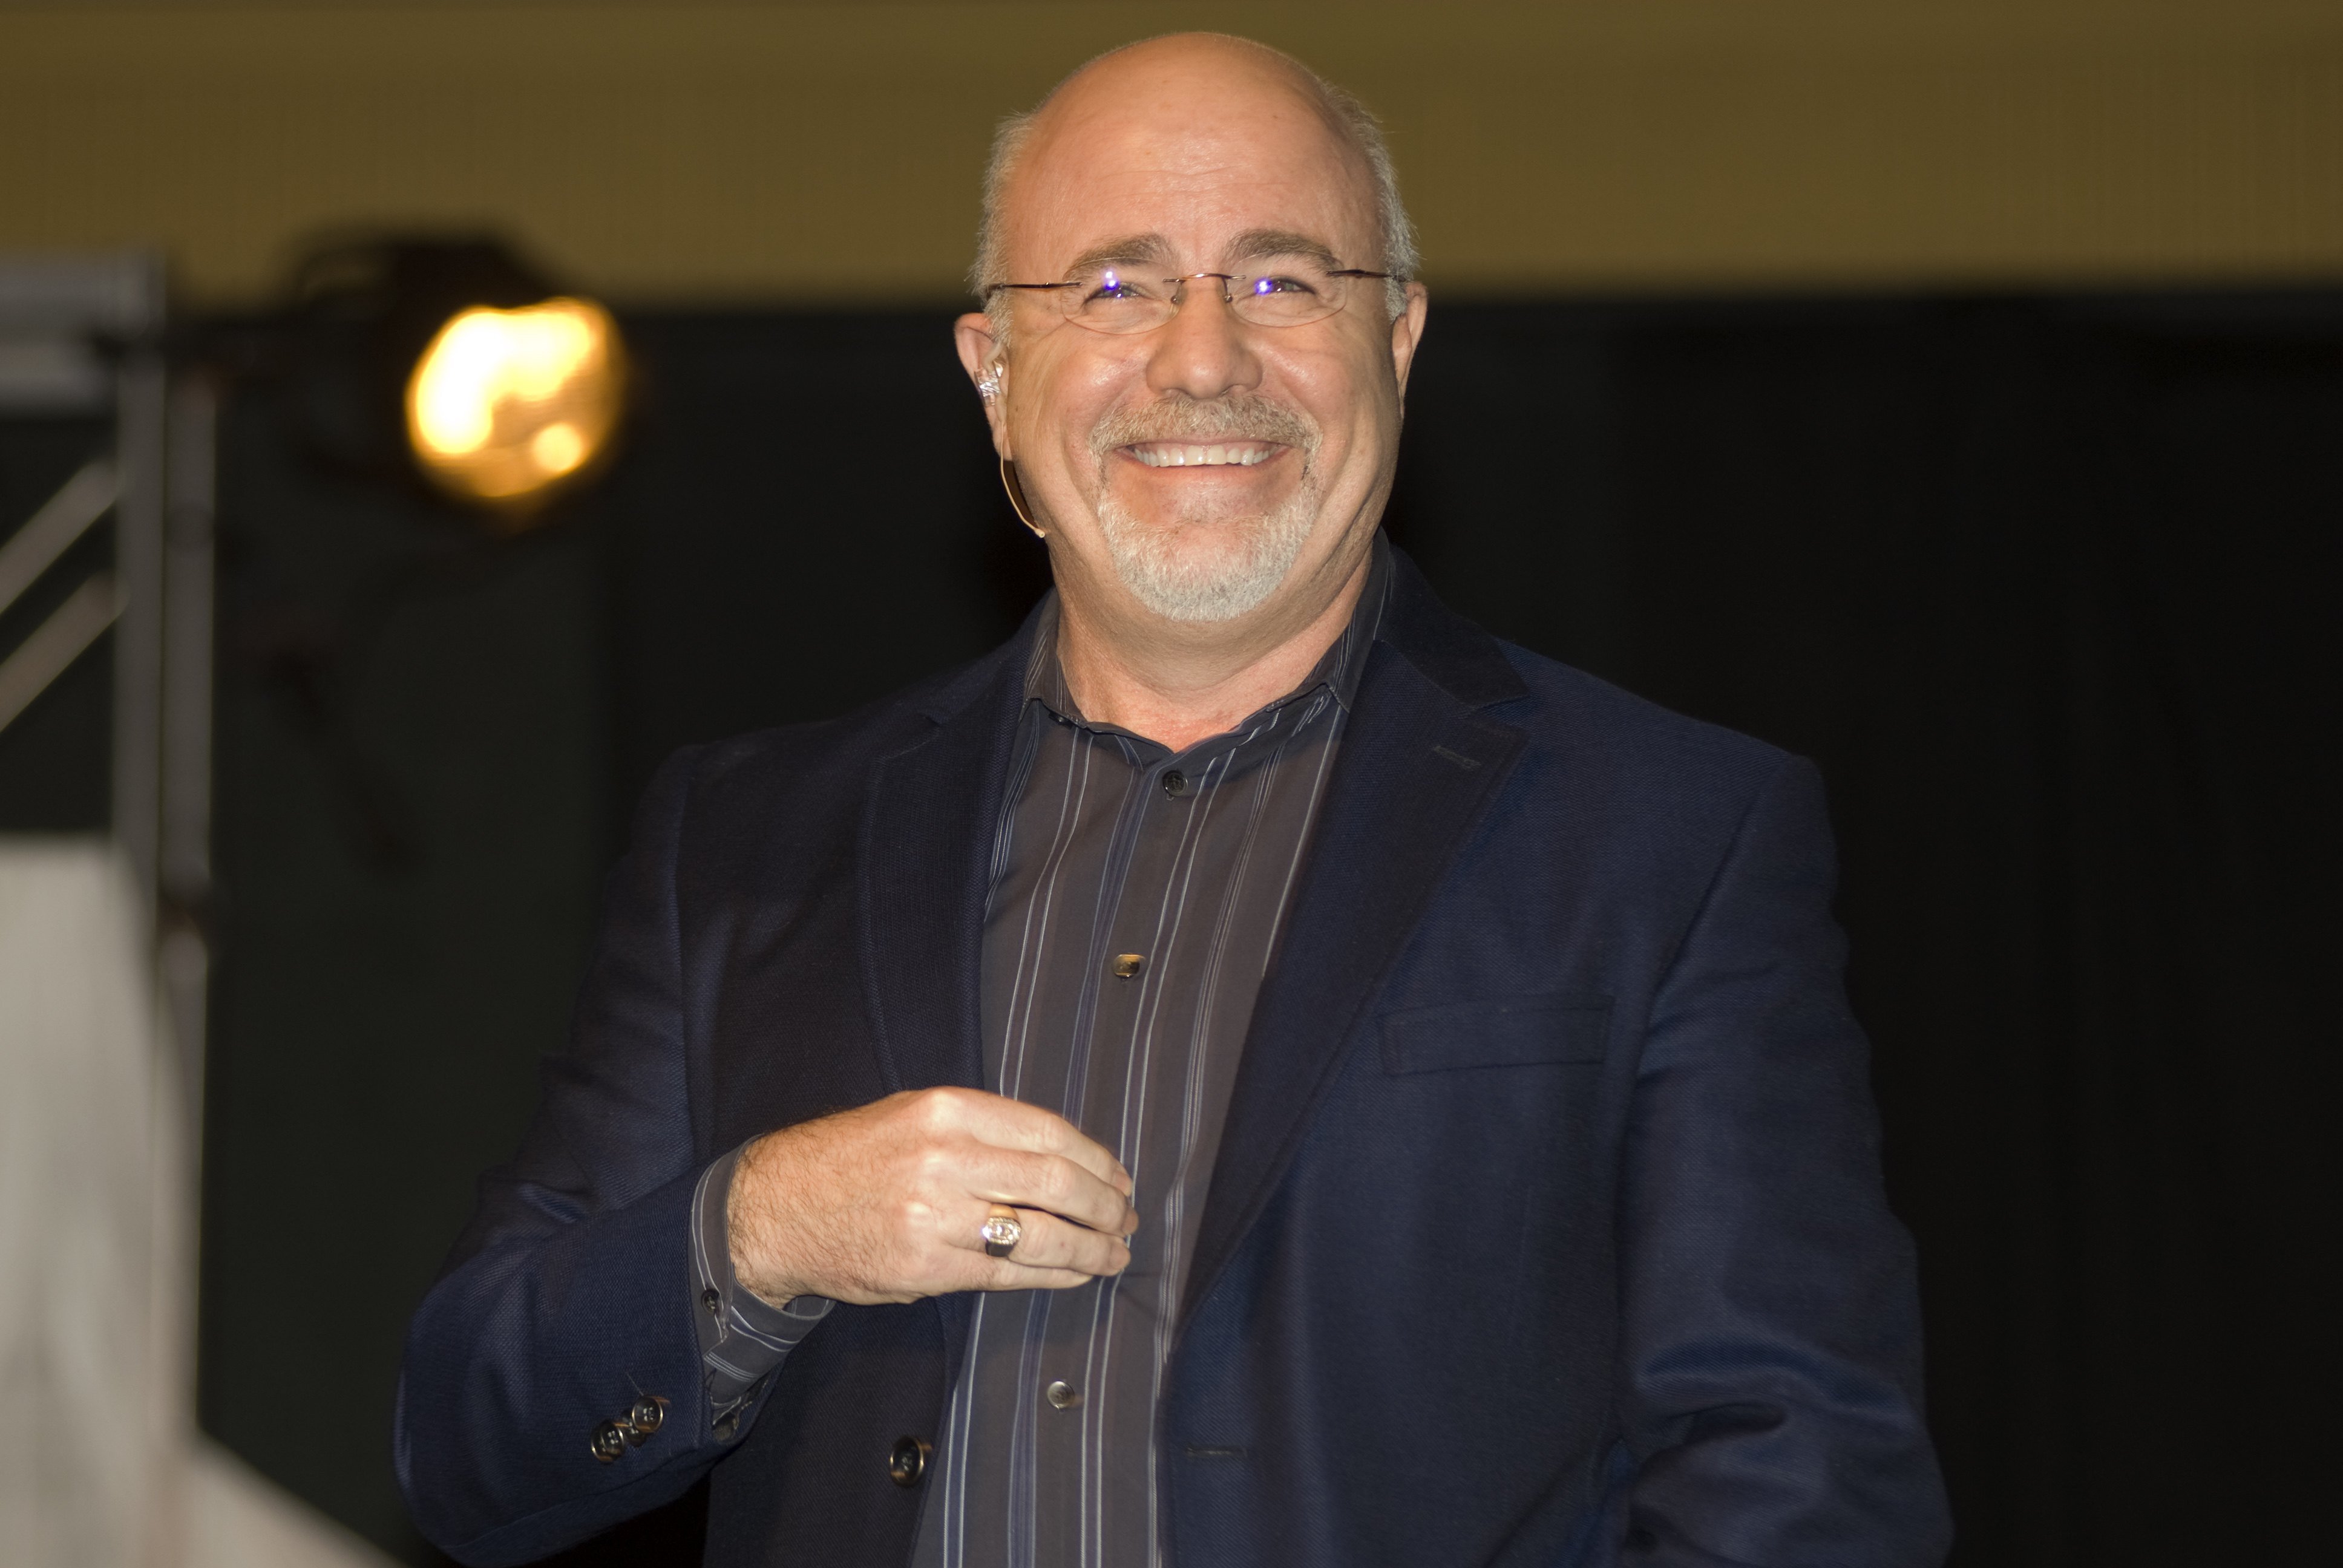
A Boston caller named Richard called The Ramsey Show with “basically no income” and a question about bankruptcy. He had run up $68,000 of debt in six months “due to a manic episode,” before anyone had diagnosed him as bipolar. He owes $12,000 more on a car. His words: “$80,426 is what I owe.”
Dave Ramsey, the show’s debt-free host, told him to pay the car minimums and attack the smallest card first. As for the rest: “If you can’t get to all of them, let them go. Just don’t pay them.” He added, “I would rather you just not pay them and go settle with them later than file bankruptcy.”
Ramsey’s Plan Is a Default With No Legal Shield
The advice is dangerously incomplete. Skipping payments to settle later still ends in a default. Bankruptcy’s automatic stay legally stops collection calls, lawsuits and wage garnishment. Defaulting on your own gives you none of that protection.
Co-host Jade Warshaw said $3,000 a month would get Richard out in 22 months. Those payments add up to $66,000. That is $14,426 short of what he owes, and that’s before any interest.
Interest makes the gap wider. The average card APR is 21%, so the card balance alone builds up about $1,200 a month in interest. At that payment, paying off the balance takes about 29 months. Warshaw’s plan works only if card issuers agree to take less than he owes. That outcome is a settlement, and settlements cost more than they look like they do.
Ramsey knows the alternative firsthand. On an August 7, 2026 episode he described his own rule’s origin: “We decided after filing bankruptcy: we don’t borrow money.” Weeks later he said bankruptcy “relieves the pressure today. It does not fix the problem in your mirror.” On this call, he said Richard’s debt “is the symptom of the manic episode.” Richard’s “mirror” problem is medical, and he says he is on his medication.
Forgiven Card Debt Can Become Taxable Income
Under federal tax law, canceled debt generally counts as income, as stated in 26 U.S.C. § 61(a)(11). Say a card settles for half its balance. The forgiven half can be taxed like wages. There are two key exceptions. Debt discharged in a title 11 case (bankruptcy) isn’t taxed. Neither is debt discharged when the taxpayer is insolvent, meaning your debts are larger than your assets.
Richard is probably insolvent right now. But he has to prove it each time a card settles, using IRS Form 982. In general, charged-off debt can still be sued on until the state’s statute of limitations runs out. Settlements also stay on your credit report much like a bankruptcy does.
One Paycheck Decides Which Path Wins
Richard starts a new job on the 16th at $27 an hour. Full time, that comes to about $4,680 a month before taxes.
Warshaw’s payment would take roughly 64% of that gross pay. He can only manage it because family charges him about $500 a month.
If that paycheck keeps arriving for two-plus years, the snowball-and-settle approach can work without a bankruptcy on his record. If income stops, from a relapse or a job loss, the unpaid cards keep compounding at 21% and creditors can sue. He would have no stay to stop them. Chapter 7 can wipe out unsecured card debt for filers who pass a means test based on recent income. Filing now, with almost no recent income, is when that test is easiest to pass.
Moves to Make Before the First Paycheck Clears
- Book a free bankruptcy consultation. Ask a local attorney whether you qualify for Chapter 7 today. Then compare that answer with the cost and timeline of settling card by card.
- Rerun the payoff math with real rates. Pull the APR from every card statement. Then calculate how many months $3,000 actually covers once interest is included.
- Get settlements in writing first. Never pay a settlement without a signed letter saying the balance is resolved. On each settlement date, record your assets and debts so you can claim the insolvency exception.
- Keep the car loan current. It’s secured debt, which means the lender can repossess the car. And the car likely gets you to the job that funds every other step.
- Build the treatment plan into the budget. Ramsey said it himself: “I’m not a therapist.” Fund medication and therapy before extra debt payments, because a relapse ends any payoff plan.
Choosing default over bankruptcy only pays off if your income survives your creditors’ patience, so run that math before you stop paying anyone.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)