Only 15% of Americans 55 and Older Have Past-Due Medical Bills, About Half the Rate of Middle-Aged Adults. Medicare Is a Big Reason Why
Unpaid hospital bills pile up for millions of Americans, but one age group stays far more current than the rest. The reason is a program with gaps that can still leave retirees exposed, and one simple question can shrink what…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A hospital bill can sit on the kitchen counter for months, unopened or half-paid, and it’s one of America’s most common money problems. How likely you are to have one depends a lot on your age. Survey data on past-due medical bills shows that Americans 55 and older are far less likely to be behind than middle-aged adults. The biggest reason is a health program most people join at 65: Medicare.
Who’s Most Likely to Be Behind on Medical Bills
The numbers come from the FINRA Foundation’s National Financial Capability Study, 2024 wave, a large national survey of how Americans manage money. It asked people whether they had past-due medical bills, meaning bills they hadn’t paid by the due date. The study’s three age groups compare as follows:
- Ages 35 to 54: 28%
- Ages 18 to 34: 26%
- Those 55 and older: 15%
It makes sense that middle-aged adults top the list, as they carry more debt than anyone else while paying for kids, homes, and their own care. Federal Reserve data tells the story. For the second quarter of 2026, it shows households headed by someone 40 to 54 hold 36.7% of all household liabilities and 38.8% of mortgage debt, the biggest shares of any age band. The Fed’s age bands don’t line up exactly with the survey’s, but the pattern holds, and when a surprise medical bill shows up, the budget is already stretched.
Why Medicare Makes Such a Difference
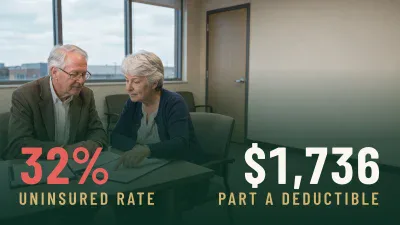
FINRA says older adults probably have the lower rate because Medicare is nearly universal once people reach the eligibility age. The survey numbers back that up. Among respondents with no health insurance at all, 32% had past-due medical bills, the highest rate in the data. Having health insurance clearly matters, though the survey doesn’t establish whether coverage or age has the greater effect.
The 55-and-older group has a catch, though. It includes people in their late 50s and early 60s who aren’t on Medicare yet. The study doesn’t break them out separately, so that figure combines retirees with full Medicare coverage and pre-retirees who may have very little coverage.
What Medicare Still Leaves You Paying
Medicare makes it less likely you’ll fall behind, but you’ll still get bills. Part B covers doctor visits and outpatient care. In 2026, it costs $202.90 a month, and higher earners pay more. Its annual deductible, the amount you pay before coverage kicks in, is $283. After that, you generally pay 20% of the Medicare-approved amount. That share is called coinsurance.
Hospital stays have their own costs. The Part A deductible is $1,736 for each benefit period in 2026. Original Medicare also has no yearly limit on out-of-pocket spending unless you add supplemental coverage like a Medigap policy or join a Medicare Advantage plan. Prescription drugs are the exception, because Part D out-of-pocket costs are capped at $2,100 in 2026. The Medigap or Advantage decision at 65 carries a lot of weight (we detailed the premium surcharges, coverage gaps, and other surprises in a free Medicare guide here).
Gap Years Before 65 Carry the Most Risk
People who retire before Medicare starts have the riskiest stretch, as they lose their employer coverage and have to buy their own, usually through the ACA marketplace, or go without. Given how often uninsured Americans fall behind on medical bills, a few years with no coverage can undo a lot of careful planning. The pressure is building, too, as Reuters reported on November 5 that U.S. hospitals are preparing for a harder 2027 as coverage losses and Medicaid cuts approach. If you’re planning to retire early, it’s smart to price out marketplace coverage before you pick a date.
If a Medical Bill Is Already Past Due
Start by asking the provider for an itemized bill that includes the billing codes for each service. Look for duplicate charges, services you never got, and claims your insurance company should’ve paid. Then ask about financial assistance. Federal law requires nonprofit hospitals to keep a written financial assistance policy. This document spells out who qualifies for free or discounted care and how to apply. If you still owe money after that, ask for a payment plan you can afford before the account goes to collections.
Your credit report matters, too. On July 11, 2025, a federal judge struck down the CFPB’s rule that would have kept medical debt off credit reports. Paid medical collections and those with an initial balance under $500 still generally stay off. Larger unpaid collections can appear after a year and hurt your score, so dealing with a bill early matters.
One Question That Can Shrink a Hospital Bill
Coverage helps people stay current on medical bills. Medicare gives older Americans a level of protection that many younger and middle-aged adults just don’t have. Call the hospital billing office first. If you’re stuck with a bill you can’t pay at any age, your first question should be: “Do you have a financial assistance policy?” It’s the fastest way to learn whether the amount on that bill is what you really owe.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.