One Late Payment Can Stay on Her Credit Report for Seven Years. A Short Goodwill Letter Sometimes Gets It Removed

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Say you have a credit card, car loan, or mortgage. A single late payment on your credit report can follow you for years. There’s a workaround worth knowing. A short goodwill letter asking the lender to remove the mark sometimes works.
How Long One Late Payment Stays on Your Credit Report
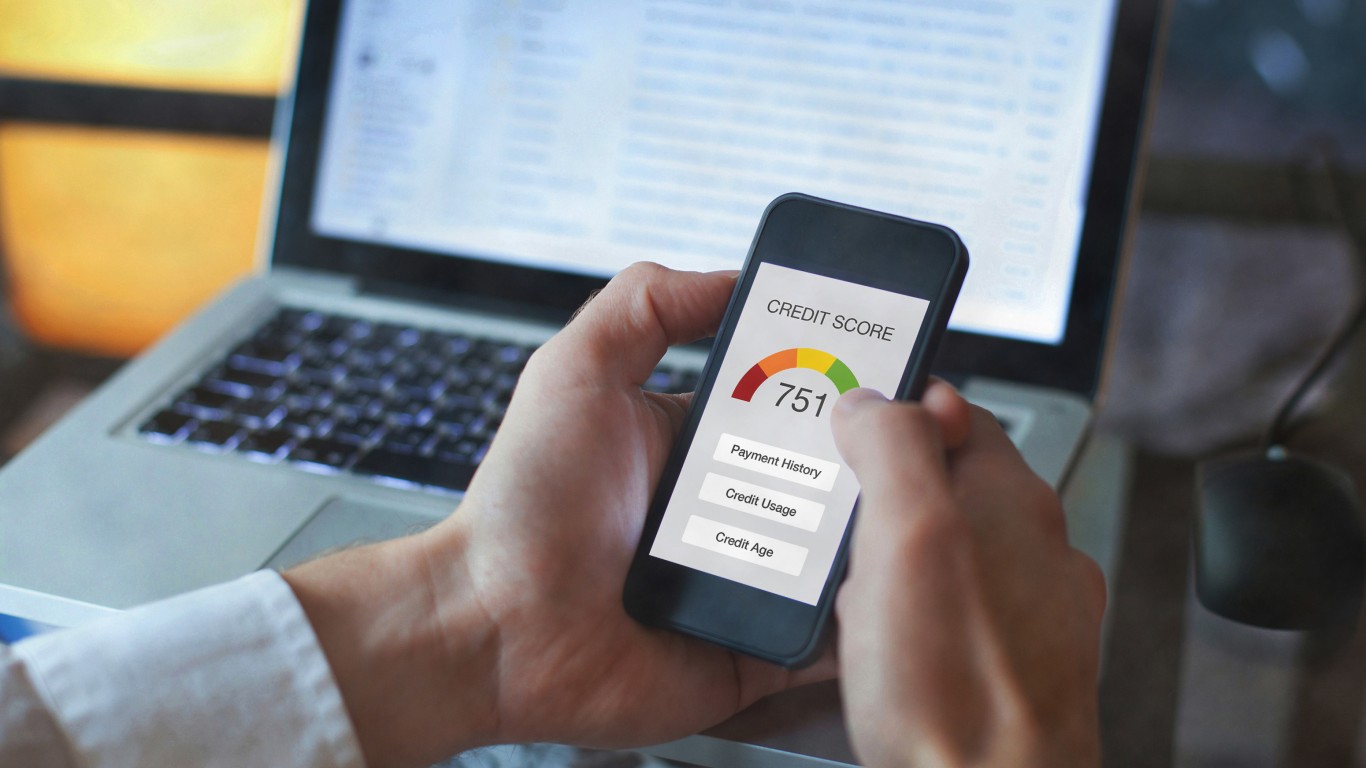
Credit bureaus can generally report negative payment history for up to seven years, according to the Consumer Financial Protection Bureau. That seven-year window is set by federal law. The rule comes from the Fair Credit Reporting Act, the federal law on credit reports, at 15 U.S.C. § 1681c. In most cases, there’s a time limit. Bureaus can’t report negative information more than seven years old, or bankruptcies that are more than 10 years old.
Late payments are common among cardholders. The share of credit card balances at least 30 days past due was 2.99% in the second quarter of 2026, according to the Federal Reserve Bank of Philadelphia. With the average card APR at 21.19% in August 2026, a lower score can drive up your borrowing costs.
Disputes Fix Errors While Goodwill Letters Ask a Favor
If a late mark is wrong, you have a legal right to dispute it, and the credit bureau must investigate unless your dispute is frivolous. Wrong, incomplete, or unverifiable information must be removed or corrected, usually within 30 days.
A goodwill request works differently. In that case, the late payment really happened. You’re asking the lender, the company that reported it, to delete it as a courtesy. A bureau may continue to report information it has verified as accurate, so the decision rests with the lender.
Who Stands the Best Chance
Goodwill letters tend to work best in specific cases. One prime example is a borrower with one late payment who has a clear reason, like an illness or job loss, and a clean record before and after. If you’ve got several missed payments, an account in collections, or a charged-off debt, your chances of success are lower.
Why Your Credit Still Counts in Retirement
Credit checks keep coming after you stop working. Under federal law, insurers, landlords, and lenders can see your report when they have a valid need. That matters if you refinance, move into an apartment, or shop for insurance. Only three states, California, Hawaii, and Massachusetts, ban auto insurers from using credit information to set rates.
How to Write a Goodwill Letter That Gets Read
- Pull your reports from all three bureaus. They’re free every week at AnnualCreditReport.com, and that weekly access is now permanent.
- Check the late mark carefully: the account, the date, and how many days late it says. If anything’s wrong, file a dispute.
- Write to the lender directly. Keep it to a few short paragraphs.
- Explain what happened in a sentence or two, something like “I was in the hospital and missed one payment.”
- Point to your record. Say how long you’ve had the account and that every other payment came in on time.
- Politely ask them to remove the late mark as a goodwill gesture, and thank them.
- Keep a copy, follow up if you don’t hear back, and check your reports later to see whether anything changed.
Lenders Can Say No to a Goodwill Request
No rule forces a lender to say yes. Some may decline or not reply. No form guarantees a result, so be wary of anyone who claims theirs does. Skip paid fixers, too.
The CFPB warns that many companies promise to “repair” or “fix” your credit for an upfront fee. If your letter gets turned down, the mark still has a limited reporting period. The mark drops off once its reporting period ends, and every on-time payment after it helps rebuild your record.
Stop the Next Late Mark Before It Lands
Set up autopay for at least the minimum payment on every card and loan to cover you during a hospital stay or a busy month. Check your reports regularly so you catch problems early. Also consider a credit freeze, which blocks new accounts from being opened in your name.
Your First Move: Confirm the Mark Is Accurate
Before you write a word, pull your reports and make sure the late payment is real and reported correctly. Dispute an error, since the bureau has to fix it as a goodwill letter is only for an accurate mark, and the lender decides whether to remove it.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.