At 66 With $900,000, She’ll Move Into a Continuing Care Community. The Entrance Fee Is the Biggest Check She’ll Ever Write

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Carol is 66, widowed, and back at her kitchen table with the contract from the retirement community she visited this morning. She has $900,000 in savings, and she plans to sell her house to cover most of the entrance fee, which is the one-time payment that gets her in the door. It’ll be the biggest check she ever writes, and many retirees end up at this same table.
What a Continuing Care Community Actually Sells
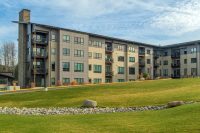
A continuing care retirement community, or CCRC, is a campus where she moves into an independent apartment while she’s healthy. If her health slips, she moves to assisted living, memory care, or skilled nursing on the same grounds. A Kiplinger story quoted a 71-year-old resident. She lives at Well Spring in Greensboro, North Carolina: “Living here is so easy, like being on a cruise ship.”
The cruise ship comes at a steep price. A May 2026 guide from Atlanta advisory firm PeachCap puts the average entrance fee at roughly $400,000, with a range of $40,000 to $2 million. Monthly fees average $3,353 and cover meals, housekeeping, maintenance, and activities.
Three Contract Types, Three Levels of Risk
The contract determines who pays if she needs nursing care later. Here’s PeachCap’s breakdown:
- Life care (Type A): These have the highest entrance fees, often $150,000 to over $1 million. Monthly fees run $2,500 to $5,000 and barely change if she needs more care. Think of it as long-term care she pays for in advance.
- Modified (Type B): She pays $80,000 to $750,000 upfront. A set number of care days is included, and after that she pays market rates.
- Fee-for-service (Type C): She pays $100,000 to $500,000 upfront, then full market price for any care she needs.
Entrance fees also come refundable or non-refundable. Many communities offer a partial or even full refund if she leaves or after she dies (Kiplinger). Refundable plans usually cost more upfront.
Rising Monthly Fees Are the Bigger Threat
The entrance fee is a one-time hit. The monthly fee never goes away, and it keeps rising. At $3,353 a month, she’s paying about $40,236 a year. The average aged widow gets $1,919 a month from Social Security, or about $23,028 a year. Her savings would cover the gap at roughly 2% a year, which is easy to handle today.
Inflation is the catch, as prices for Americans 62 and older rose 3.9%[1] over the past year, but the 2027 Social Security raise is only 3.6%. If her fees rise 3.9% a year for 20 years, that $40,236 grows to about $86,000.
For a single, healthy 66-year-old, life care is usually the better choice. Medicare doesn’t pay for long-term custodial care, like help with bathing and dressing (Medicare.gov)[2]. A fee-for-service contract leaves her paying that full bill in her 80s, while life care costs more now but protects her from the one expense that could actually wipe out $900,000. She should pay extra for a refundable plan only if leaving money to heirs truly matters to her.
Two Tax Breaks Tied to the Move
Selling the house first helps. A single filer can exclude up to $250,000[3] of gain on a home. She must have owned and lived in it for at least 2 of the last 5 years[3]. If she sells within 2 years of her husband’s death and hasn’t remarried, she may qualify for up to $500,000.
The IRS counts the part of a life-care fee paid to a retirement home designated for medical care. It qualifies as a medical expense. If she itemizes, she can deduct medical costs above 7.5%[4] of adjusted gross income. The excluded home gain doesn’t count as income, so the year she pays the entrance fee could bring a big deduction. She should ask the community, in writing, what share of its fees goes to medical care.
She should avoid covering the fee with one big IRA withdrawal. Single filers with income over $109,000[5] pay about $284 a month for Medicare Part B instead of about $203. IRMAA is one of several Medicare surcharges. These quietly surprise retirees, and we laid them all out in a free guide here.
Kick the Tires on the Community’s Finances
Her care depends on the community staying solvent. A Government Accountability Office review found that tough economic conditions stressed some CCRCs financially and put residents at risk. The GAO made no specific recommendations but emphasized the importance of states remaining vigilant about protecting residents. She should ask for the community’s disclosure statement and review occupancy rates, cash reserves, debt, and past monthly fee increases. Then she should call her state’s CCRC regulator and ask about complaints.
Ask This Before Signing
Before she signs, she needs one answer: what happens to her entrance fee if she leaves or dies in the first few years? She should get the refund schedule in writing, including how fast the refund shrinks and whether it’s paid only after her apartment is resold. If the community can’t give her a clear answer, she should think twice about signing.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.