Her $400,000 Annuity Comes Out of Surrender at 71 as Annuity Sales Hit a Record $126.3 Billion. Cashing Out Adds $150,000 of Income Medicare Will Count; a Tax-Free Swap Into a New Annuity Adds $0

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
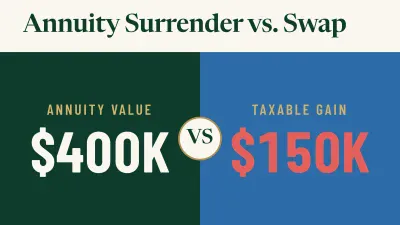
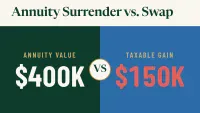
A 71-year-old widow just learned her deferred annuity has passed its surrender schedule. The contract is worth $400,000, and she paid $250,000 into it. She can take the check or move the money into another annuity. Taking the check hands Medicare $150,000 of new income. Moving the money hands it nothing.
Plenty of owners are making the same choice. U.S. annuity sales hit a record $126.3 billion in the third quarter of 2026, the 12th straight quarter above $100 billion, according to LIMRA data. Fixed-rate deferred contracts alone brought in $44.5 billion. Every one of those contracts eventually runs out of surrender charges, and every owner then faces the same tax decision.
The Medicare surcharge at stake is the Income-Related Monthly Adjustment Amount (IRMAA), and it affects under 10% of beneficiaries. For 2027, a single filer with modified adjusted gross income (MAGI) at or below $112,000[1] pays the standard $209.40 Part B premium. The people most likely to cross that line in a single year are owners of nonqualified annuities with large untaxed gains.
How One Surrender Adds $4,788 to Her Medicare Bill
When she surrenders a nonqualified annuity, the gain above what she paid in becomes ordinary income. Here that gain is $150,000. IRMAA uses MAGI, which is adjusted gross income plus tax-exempt interest, so the whole gain counts. Say her Social Security and IRA income already produce $60,000 of MAGI. Cashing out raises that to $210,000. The table uses the 2027 brackets CMS released Nov. 17, 2026[1].
| Scenario (single filer) | MAGI | Part B premium (monthly, per person) | Part D surcharge (monthly, per person) | IRMAA surcharge (annual, per person) |
|---|---|---|---|---|
| 1035 exchange | $60,000 | $209.40[1] | $0[1] | $0 |
| Full surrender | $210,000 | $544.40[1] | $64[1] | $4,788 |
| Surrender plus more than $2,000 of other income | Over $212,000[1] | $670[1] | $88.30[1] | $6,586.80 |
At $210,000, she sits just $2,000 below the next tier. One year-end mutual fund distribution could push her into it.
The timing of the surrender determines which year’s premium she pays. Medicare looks back two years, so 2027 premiums are based on 2025 MAGI[2]. If she surrenders before Dec. 31, the income goes on her 2026 return and raises her 2028 premiums. If she waits until January, the increase moves to 2029. In both cases, a one-time spike costs one year of surcharges.
Being a widow makes it worse. If she still filed jointly, the same $210,000 would fall below the $224,000[1] joint threshold and trigger no surcharge. Her income stayed the same. Her threshold was cut in half.
IRMAA is one of several Medicare costs that scale with income in ways retirees rarely see coming (we mapped out the added fees and coverage limits in a free Medicare guide here).
Form SSA-44 won’t get her out of it. Social Security takes the form for marriage, divorce, the death of a spouse, loss of income, and an employer settlement payment[3]. A voluntary surrender raises income by choice, and SSA will deny an appeal based on it.
Why a Tax-Free Swap Adds $0 of Income
Section 1035 of the tax code says “No gain or loss shall be recognized”[4] on the exchange of “an annuity contract for an annuity contract”. IRS Publication 575 adds one condition: the insured or annuitant remains the same. Her gain moves into the new contract and stays untaxed until she withdraws it.
Two traps can undo the swap. First, the money has to go directly from one insurance company to the other. IRS Publication 544 says the nontaxable transfer rules do not apply to a rollover in which you receive cash proceeds and reinvest them. If she cashes the check and buys a new annuity a week later, the IRS treats it as a surrender. Second, most new deferred contracts start a fresh surrender schedule. Read that schedule before signing.
Three Moves That Keep Her Under the Line
- Swap if she doesn’t need the money. She can request a direct 1035 exchange into a contract with a short surrender schedule or none at all. Her MAGI stays at $60,000.
- Swap into an immediate annuity if she wants regular income. Under the IRS General Rule, each payment includes the tax-free part that is a return of your net cost. That spreads the gain over many years, and only part of each check counts toward MAGI.
- Withdraw in thirds if she wants cash. Withdrawals come out of the gain first under 26 U.S.C. § 72(e)(3)[5], so every dollar is taxable until the gain is used up. Taking $50,000 a year for three years keeps her MAGI at $110,000, under the 2027 threshold of $112,000[1]. That margin is thin, but the threshold has been rising: it was $109,000[2] in 2026. She should start soon, because her IRA required minimum distributions (RMDs) begin at 73 and will add to her income from then on.
CMS won’t release the brackets for 2028 premiums until late 2027, after her 2026 income is already set. Her best plan is to decide based on today’s brackets and leave herself room below each cliff.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.