At 65 With $850,000, He’ll Remember a 401(k) From a Job He Left Decades Ago. A Federal Lost-and-Found Database Can Help Him Find It

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
He’s cleaning out a desk drawer when an old pay stub turns up. It’s from a company that hasn’t existed in years, and it shows a 401(k) deduction. At 65, he already has about $850,000 saved, but now one question won’t leave him alone: did he ever move that money, or is it still sitting somewhere with his name on it?
If you changed jobs a few times early in your career, you probably know the feeling. It’s part guilt and part hope. Lots of people left balances behind, and after they left, companies merged, renamed their plans, or shut down. One caller to The Clark Howard Podcast described getting mail about an ended plan at an old employer and said, “I’m a bit overwhelmed.” That’s a normal reaction, and the fix is simpler than it looks.
Keep the Tax Shelter Intact After You Find the Money
An old account might be small next to his main nest egg, but the biggest risk comes after he finds it. If he takes the money as a check, he could lose a large chunk to taxes, and if he forgets about it, he could miss a required withdrawal and owe a penalty. The goal is to find the account, keep it tax-deferred, and roll it into the money he already handles.
Start With the Federal Lost and Found Database
Congress created the Retirement Savings Lost and Found Database in the SECURE 2.0 Act of 2022, signed on December 29, 2022. The Department of Labor calls it “a centralized location to find lost or forgotten benefits and get information on how to obtain those funds.”[1]
You’ll find it at lostandfound.dol.gov, and you sign in through Login.gov, but it’s important to know its limits. The department says the database only provides information. It does not decide eligibility, process benefit applications, or pay benefits[1]. It points you to the plan, and the plan pays you.
Watch out for scams. The department says it will never call, text, or email you to ask for your password or one-time passcode[1]. If someone reaches out offering to “recover” your old 401(k), hang up.
Three Other Places an Old 401(k) Can Hide
- The old employer or its successor. Call the HR department, or whichever company bought the business, as old statements usually list the plan name and administrator. Before paying out a balance, the administrator has to give you a written explanation of your rollover options[2].
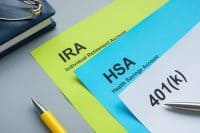
- An automatic rollover IRA. If his balance was small, the plan may have moved it without asking him. Under current law, a plan can immediately pay out balances of $7,000[3] or less, but amounts over $1,000 generally must be rolled into an IRA unless the other elects otherwise. The IRS does say there’s an automatic rollover requirement for mandatory distributions. That often means the money went into an IRA opened in his name at a provider he’s never heard of.
- State unclaimed property. If a check went to an old address and nobody cashed it, the money may have been turned over to the state. Search the unclaimed property site for every state where he lived or worked.
Once He Finds It, Skip the Check
He has three choices: leave the money where it is, roll it into his current plan or an IRA, or cash out.
For most people, cashing out is the worst option. Any pretax money he cashes out counts as taxable income in the year it’s paid out. If the plan pays him directly, it must withhold 20%. That money adds to his other income for the year, so it can push him into a higher bracket. He’s old enough to avoid early-withdrawal penalties, but he still owes the income tax.
Leaving it alone works if the old plan has low fees. But that’s one more login and one more address to keep current, and forgetting about the account is how he got here in the first place.
For most people, a direct rollover is the clear winner. The money goes straight from the old plan to his IRA or current plan. Taking that option avoids the 20% withholding, and the money stays tax-deferred.
Fewer Accounts Make RMDs Simpler
Anyone turning 65 this year was born after 1959, so under current law his required withdrawals start at 75. That’s a decade away, but now is the time to consolidate.
For IRAs, he figures each RMD separately but can take the total from one or more of them. For 401(k)s, RMDs must be taken separately from each plan account. Every 401(k) he leaves scattered around means another withdrawal he has to remember.
Missing one costs real money. The penalty is 25% of the amount he should have taken out, cut to 10% if he fixes it in time. An account he doesn’t know about is the easiest one to miss, and it’s one of nine IRS rules that quietly drain retirement accounts (we detailed all of them in a free tax trap guide here).
What to Do This Week
First, search the Lost and Found database tonight, then call any old employers if it doesn’t turn up. Second, when you find money, ask for a direct rollover into the IRA or plan you already use. If a check is necessary, make sure it’s payable to the IRA or plan, not to you personally. Your goal is to have one or two accounts you know by the time RMDs start.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.