At 67, She’ll Pull $400,000 From Her 401(k) to Pay Cash for a New Home as Builders Slash Prices. Taken All in December, the Federal Tax Is About $111,000. Split Into January, About $86,000

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
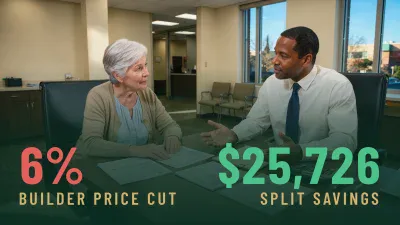
A 67-year-old single retiree who collects $30,000 a year from Social Security has found her house, a new build near the national median of about $400,000. She plans to pay cash from her 401(k).
If she takes the full amount this December, her federal income tax comes to about $111,342. If she takes half in December and half in January, the two-year total falls to about $85,616. Moving half the withdrawal a few weeks later saves roughly $25,726.
Builders Will Wait for January Right Now
The housing market gives her room to set the timing. The National Association of Home Builders sentiment index fell to 25, its weakest reading since April 2012, HousingWire reported.
Price cuts came from 46% of builders, the most since Covid began, with a typical cut of 6%. Another 68% offered incentives.
CNBC tied the same slump to more builders dropping prices. Chances are a builder holding finished homes in that market will agree to a closing date in early January, and that single concession is what makes the split work.
Why One December Withdrawal Costs $25,000 More
She was born in 1959, so her required distributions don’t begin until age 73, with the first required minimum distribution (RMD) year in 2032. This withdrawal is entirely voluntary, so she decides which tax year it lands in.
The math uses 2026 single brackets, the $16,100 standard deduction, and the extra $2,050 for filers 65 and older.
A withdrawal this large also makes 85% of her Social Security taxable, the ceiling set by 26 U.S.C. § 86(a)(2)[1]. That adds $25,500 to her income.
| Scenario | Taxable income | Federal tax |
|---|---|---|
| All $400,000 in December | $407,350 | $111,342 |
| $200,000 per year, split | $207,350 | $42,808 each |
| Split, two-year total | n/a | $85,616 |
The lump sum pushes a large share of the withdrawal into the 35% bracket. In each split year, income only slightly exceeds the top of the 24% bracket. The January half will probably cost less than the table shows, because 2027 brackets get an inflation adjustment. The 2027 brackets are also out, and this half remains in the 24% bracket.
Medicare Bills Her for Both Years When She Splits
Medicare sets IRMAA (the income-related monthly adjustment amount) surcharges using income from two years earlier. A single filer with income between $205,000 and $500,000[2] pays $649 a month for Part B.
The standard rate is $203[2]. Part D adds another $83[2] a month. The lump sum puts her in that tier, and so does each year of the split.
Splitting therefore triggers the surcharge in two years instead of one. At current brackets, the extra year costs about $6,355. After paying it, she still comes out roughly $19,371 ahead. The split is the cheaper path. IRMAA is one of several IRS rules that silently drain retirement accounts, and we mapped the rest in a free tax trap guide.
20% Withholding Shrinks the Closing Check
A cash distribution taken directly from a 401(k) comes with mandatory 20% federal withholding under 26 U.S.C. § 3405(c)(1)(B)[3]. On $400,000, that sends $80,000 to the IRS and leaves her short of the full price on a $400,000 house. With the lump sum, her actual tax bill would still be about $31,342 more than what was withheld.
A direct rollover to an IRA avoids that. IRA withdrawals are nonperiodic distributions with a default 10% withholding rate under 26 U.S.C. § 3405(b)(1)[3], and she can raise it, lower it or waive it. She can then withhold close to her real tax in each year, so the IRS gets the right amount and the builder gets the full price.
Three Steps to Take Before December 31
- Put a January closing date in the contract. Ask for it in writing alongside any price cut or incentive. After that, roll the 401(k) into an IRA and take the first $200,000 before year end. Keep it in a money market fund for a few weeks.
- Make the rollover direct. Request a trustee-to-trustee transfer so the whole $400,000 reaches her IRA. Set the withholding on each IRA withdrawal to approximately $42,808. That way, neither year leaves her with a lopsided balance due in April.
- Set aside cash for the surcharges two years out. Reserve about $6,355 for each of the two IRMAA years, and keep other income low in both years. Realizing capital gains or doing a Roth conversion in 2027 would nudge more of her income into the 32% bracket.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.