Nobody Tells Retirees Who Come Back as Consultants About Self-Employment Tax

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The call often comes a few months after the retirement party. Your old employer, or a firm in your old industry, needs someone who already knows the systems, the clients and the shortcuts. The work is familiar, the hours are flexible, and the hourly rate looks generous.
That rate is gross pay. Once you work as a consultant, you are self-employed, and the tax rules change before you send your first invoice.
You Now Pay Both Halves of Social Security and Medicare
As an employee, you paid 7.65% and your employer matched it. As a consultant, you owe the full self-employment tax rate of 15.3%[1] for 2027. Federal law splits that into 12.4%[2] for Social Security and 2.9% for Medicare (26 U.S.C. § 1401(a) and (b)(1)). For 2026, the Social Security portion applies to earnings up to $184,500. The Medicare portion has no cap. An extra 0.9%[2] Medicare tax applies to self-employment income above $200,000 for single filers and $250,000 on joint returns.
The filing threshold is low. If your net earnings from self-employment reach $400 or more, you have to file a self-employment tax return (26 U.S.C. § 6017). There is some relief: you can deduct one-half of the self-employment tax, not counting the extra 0.9% Medicare tax (26 U.S.C. § 164(f)). That deduction lowers your income tax. Your self-employment tax bill stays the same.
No Withholding Means Quarterly Payments
Nobody withholds tax from a consulting check, so you have to send the IRS four estimated payments a year. The law sets the due dates at April 15, June 15, September 15 and January 15[3] of the following year (26 U.S.C. § 6654(c)). That puts the final payment for tax year 2026 on January 15, 2027[3].
Each payment should cover 25%[3] of what the law calls the required annual payment. That is the smaller of 90%[3] of this year’s tax or 100% of last year’s. The second figure rises to 110%[3] if last year’s adjusted gross income was above $150,000 (26 U.S.C. § 6654(d)(1)). If you pay too little, the IRS adds a charge at its underpayment interest rate. No charge applies if your tax due after withholding is under $1,000[3] (26 U.S.C. § 6654(e)(1)).
Consulting Pay Counts Toward Social Security’s Earnings Limit
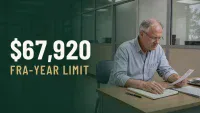
If you started Social Security before full retirement age, the Social Security Administration counts "all net earnings from self-employment" toward its earnings limit. For 2026 that limit is $24,480[4]. Above it, SSA holds back $1 for every $2[4] you earn. In the year you reach full retirement age, the limit is $65,160[4] and SSA holds back $1 for every $3. Only earnings before the month you reach that age count. Once you reach full retirement age, the limit disappears. SSA then raises your benefit to make up for the months it held back.
Consulting income can also raise your Medicare premiums two years later. For 2027, single filers with modified adjusted gross income above $112,000 ($224,000[5] joint) pay more than the standard Part B premium of $209.40 a month.
Self-Employment Lets You Keep Saving for Retirement
For retirement plan purposes, tax law treats a self-employed person with earned income as an employee (26 U.S.C. § 401(c)(1)). That means you can open a Solo 401(k) or a simplified employee pension, or SEP IRA (26 U.S.C. § 408(k)), and keep saving while you work. Social Security can pay off too. If consulting gives you one of your highest-earning years, SSA recalculates your benefit[4] and pays any increase.
Price Your Hours After Self-Employment Tax
Before you accept a rate, take out the 15.3%[1] self-employment tax and your income tax. Then check the earnings limit if you are under full retirement age, and check the Medicare income brackets. Quote the rate that still leaves you the take-home pay you want. Put each check’s tax share in a separate account, and mark the four payment dates on your calendar the day you sign the contract. Phasing out of work this way comes with a handful of tax traps beyond self-employment tax, and we mapped them in a free semi-retirement playbook here: Retire Twice.
Contact [email protected] for any questions or corrections.
Austin Smith is a financial publisher with over two decades of experience as an investor, analyst, and advisor. He covers stocks, ETFs, Artificial intelligence and personal finance for 24/7 Wall St. Previously, he spent over a decade at The Motley Fool as a senior editor for Fool.com, portfolio advisor for Millionacres, and launched The Ascent to help reader take control of their personal finances.
His work has been featured on Fool.com, NPR, CNBC, USA Today, Yahoo Finance, MSN, AOL, Marketwatch, and many other publications. He is as an advisor to private companies, and co-hosts The AI Investor Podcast with Eric Bleeker.
When not looking for investment opportunities, he can be found skiing, running, or playing soccer with his children. Learn more about Austin's investment approach here.