Beef Prices Remain High. Social Security’s 3.6% Raise Uses a Price Index Built Around Workers, Not Retirees
Social Security's raise is calculated from an index that deliberately excludes retiree households, and the government already tracks a separate measure that weights medical care and housing more heavily for older Americans. Congress just hasn't required anyone to use it.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
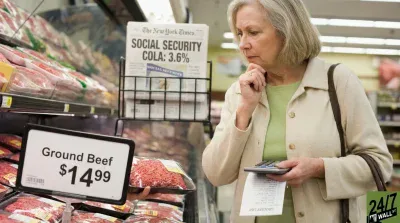
A retiree is standing at the meat counter with a package of ground chuck in her hand, working out whether it fits this week’s budget. She just heard that Social Security’s 2027 cost-of-living adjustment (COLA) is 3.6%. That should feel like good news. She’s wondering why a raise that size never seems to go far enough.
Beef is a reasonable place for that doubt to start. According to reports, high beef prices have been stubborn and aren’t likely to ease anytime soon. The meat case is likely to stay expensive for a while.
The bigger question is how closely Social Security’s inflation formula reflects a retiree’s actual expenses.
Whose Shopping Cart Sets Your Raise
Social Security’s 2027 COLA fact sheet says benefits will rise 3.6% in 2027. That number comes from the Consumer Price Index for Urban Wage Earners and Clerical Workers, an inflation measure the government shortens to CPI-W.
The formula is simple. Social Security averages the index over July, August and September and compares that average with the same three months a year earlier. The percentage change becomes the raise.
The catch is whose spending determines the raise. CPI-W reflects households supported mainly by wages from certain occupations, including clerical, service and construction work. Retiree-only households aren’t part of that group. So the index can give less weight to expenses that take up a larger share of older Americans’ budgets, particularly medical care.
A Retiree Index Exists, and No Check Uses It
The Bureau of Labor Statistics, the agency that produces the government’s inflation data, also releases a research index called R-CPI-E. It tracks spending patterns in households where the reference person or spouse is at least 62. Housing and medical care receive greater weight, reflecting how older households spend their money.
It remains a research index, and Social Security doesn’t use it to set benefits. When it rises faster than CPI-W, the official COLA falls short of the inflation measured for older households. When it rises more slowly, the opposite is true.
Social Security can’t switch indexes on its own. Using a different one would take an act of Congress.
Why Your Inflation Rate Belongs to You Alone
Even an ideal retiree index would still be an average. Food is one part of the index, next to housing, transportation, medical care and other categories. Beef is a small piece of the food part.
So two people getting the same 3.6% raise can have very different years. A renter who just signed a more expensive lease, takes brand-name medication and cooks beef most nights will probably feel a bigger squeeze than the official number suggests.
Her neighbor owns her home outright, fills generic prescriptions and mostly eats chicken and beans. For her, the same raise may more than cover her rising costs. Both of them are reading inflation correctly. Each one is measuring her own.
Budget for Your Own Cart Before the Next Raise Arrives
The debate over which index to use is worth following, but it moves at the speed of Congress. Your grocery bill shows up every week. Keeping the two separate stops a policy argument from driving your household decisions.
A good place to start is to pull a few months of bank and card statements and sort the spending into a handful of groups: housing, health, food and transportation. Compare each group with the same months last year. Look for the biggest increases in dollars, then focus on expenses you can realistically trim. If beef is the problem, that could mean cheaper cuts, larger packs you freeze, or replacing a couple of beef dinners each week.
The mistake that’s hardest to undo is quietly taking extra money from savings to keep your old spending habits while you wait for the COLA to catch up. Over a long retirement, that shortfall adds up. Next year’s raise will again be set by summer figures of an index built around workers.
Every household spends differently on rent, prescriptions and groceries, so the most useful numbers are the ones on your own statements. The COLA reflects inflation for a particular group of working households. Your receipts show what happened to yours.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.