A Couple Maxes Out Their Credit Cards on Black Friday and Regrets It. Americans Face $19 Billion in Buyer’s Remorse. Social Security Gives Them 12 Months to Undo a Much Bigger Retirement Decision

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Picture a hypothetical couple on the Friday after Thanksgiving: a new TV, a stand mixer, gifts for the grandkids, and two credit cards maxed out by noon. By Sunday, the receipts feel heavier than the shopping bags.
They have plenty of company. A November 5 SweepsPluse survey estimates that Americans will make $19 billion in Black Friday purchases they later regret, and 43% of shoppers said they regretted something they bought. The number merely projects regret. It does not measure credit card debt.
This couple has a second regret that carries higher stakes. The husband, 62, started collecting Social Security earlier in 2026 and now wonders if he moved too fast. A store gives him 30 days to return a blender. He has 12 months to take back his retirement claim through Social Security, and the cost of doing that is much higher.
A Return Window You Get Only Once
Social Security generally lets you withdraw a retirement application within 12 months of your first month of benefit entitlement, using Form SSA-521. You can do this only once in your lifetime.
Withdrawing wipes out the claim as if he never filed. When he applies again later, the agency figures his payment from his age at that new start date, and the reduction he locked in at 62 goes away.
Why the Undo Button Costs $10,500
Say he has received $1,750 a month for six months, or $10,500 in total. To withdraw, he has to pay back all of it. That includes any amounts held back for taxes and any benefits paid to family members on his record. If his wife collected a benefit on his record, she generally has to consent in writing, and her payments go back too.
Their holiday debt makes this harder. At a 21% credit-card interest rate, a $10,500 balance would cost about $2,205 a year in simple interest. Putting the repayment on a credit card would only swap one problem for another, so the money realistically has to come from savings.
What Waiting Puts in His Pocket
He was born in 1964, so his full retirement age is 67.
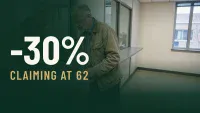
For anyone born in 1960 or later, taking at 62 cuts the monthly check by 30%.
His $1,750 check works out to a full-retirement-age benefit of about $2,500. Waiting until 67 would give him about $750 more per month, or $9,000 more annually, before future cost-of-living adjustments (COLAs).
Each cost-of-living raise, like the 3.6% increase coming in 2027, is a percentage of the check. A bigger check gets bigger raises in dollar terms.
The catch is time. Waiting means giving up about five years of $1,750 checks, roughly $105,000, counting the $10,500 he would repay.
At $750 more per month, he would break even around age 79 in a simplified calculation that excludes inflation adjustments, taxes and other costs. Living into his 80s could favor waiting, and the larger benefit could also increase his wife’s survivor payment if he dies first.
Withdrawing Now Versus Pausing at 67
If he misses the 12-month window, he still has one weaker option. At full retirement age, he can voluntarily suspend his payments and makes delayed retirement credits of 8% a year until 70.
Nothing has to be repaid. The original early-claiming cut remains, although delayed retirement credits can increase his payment after suspension. Withdrawing erases the original claim. Suspending raises a benefit that was already diminished.
Covering five years without Social Security means relying on savings or a paycheck. If he keeps his claim and goes back to work before 67, the agency holds back some benefits once earnings pass $24,480 in 2026. A return to work is a common reason people choose to withdraw.
Two Deadlines With Very Different Stakes
Some Black Friday regrets can be fixed with a return receipt or a payoff plan in January. Before filing, this couple would want to confirm his exact first month of entitlement, set aside the repayment from savings rather than credit, and make sure they can cover several years of bills without adding new debt.
The mistake that’s hardest to fix is letting the deadline pass while they’re still deciding. After month 12, the 30% cut is permanent. Their health, their savings and her own work history could all change the math, so asking Social Security for the exact amount he would owe is a reasonable first step.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.