Is Lucid a Real Company?
How many Lucid cars do you see on the road in a week? I own EVs myself, but I can count my Lucid sightings on one hand with fingers to spare. I see more International Scouts from the 1970s on…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
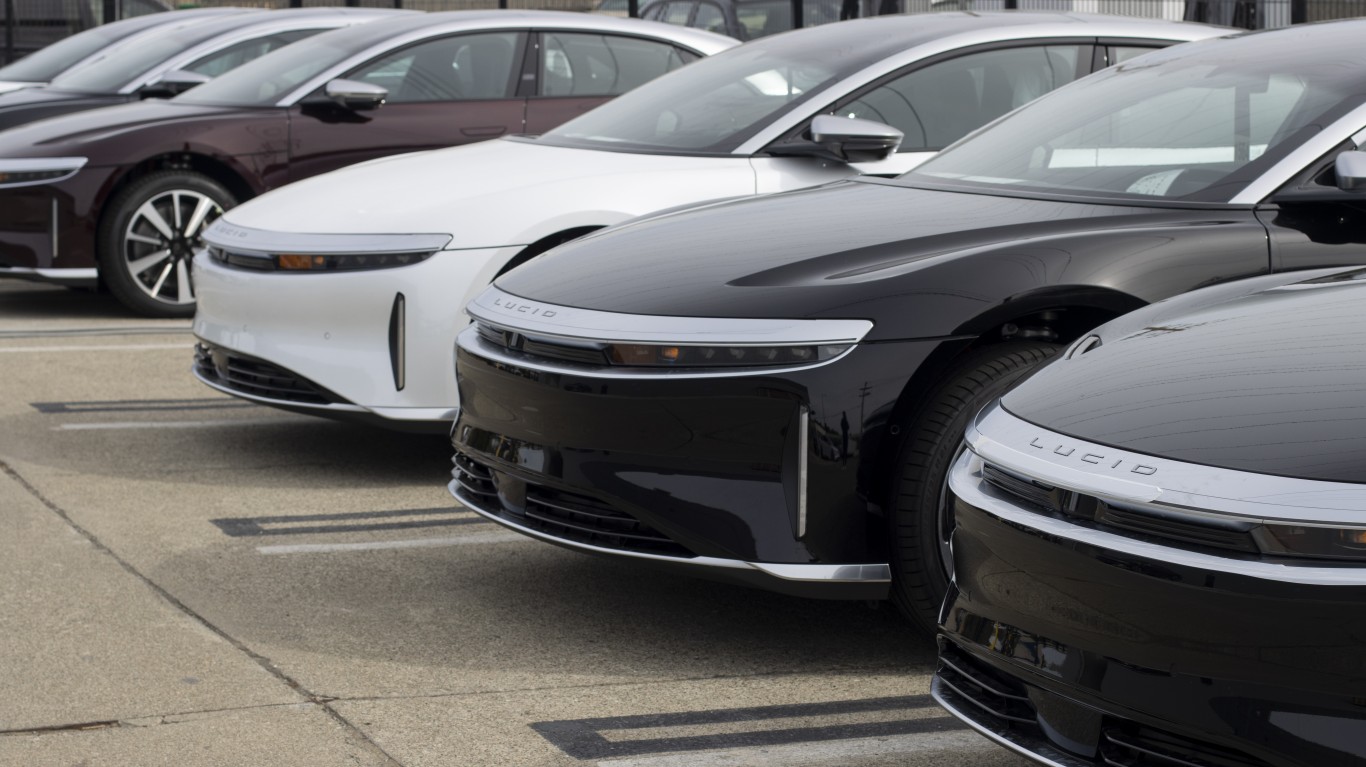
How many Lucid cars do you see on the road in a week? I own EVs myself, but I can count my Lucid sightings on one hand with fingers to spare.
I see more International Scouts from the 1970s on the road than I do Lucids. That’s a genuine question about the business.
The Ad
Lucid Group (NASDAQ:LCID | LCID Price Prediction) recently ran an ad with the tagline: “Anyone can build an EV. We built the best damn car.” Did you though?
The best damn car that cost $944.64 million to produce in Q4 2025 alone, against $522.73 million in revenue? Every single car Lucid sells costs roughly twice what the company collects for it. That’s…not a business.
Full year 2025 production came in at approximately 17,840 vehicles. A single busy Toyota dealership moves that in a year. Lucid’s Q4 2025 deliveries were 5,345 vehicles, up 72% year over year. Growth is real. Scale is not.
The EPS picture is worse. Q4 2025 non-GAAP EPS came in at -$3.08, missing estimates by 43%. That miss follows a -19% miss in Q3 and a -11% miss in Q2. The direction of travel on execution is wrong.
The Saudi Question
Saudi Arabia’s Public Investment Fund, through Ayar Third Investment Company, is Lucid’s largest stakeholder. The PIF also extended a term loan facility to approximately $2 billion, making them both owner and banker. Lucid operates a manufacturing facility in Saudi Arabia (AMP-2), and the PIF is an anchor customer.
If the Saudi government stopped writing checks tomorrow, what happens to Lucid? One retail investor on r/stocks said after watching a 3.5-hour investor presentation in March 2026:
Think Lucid has about a 50% chance of going to zero without Saudi Arabia.
—reidmrdotcom, r/stocks
Prediction markets put the odds of Lucid announcing bankruptcy before 2027 at 30%. That’s a tradeable market with real money behind it. I think it’s pretty unlikely they go bankrupt. This is a $3B market cap company built on near infinite oil. It’s much more likely they go private than bankrupt.
Regardless, is this a car company or a geopolitical technology project dressed in Silicon Valley branding? Probably both, and that’s what makes it genuinely hard to value.
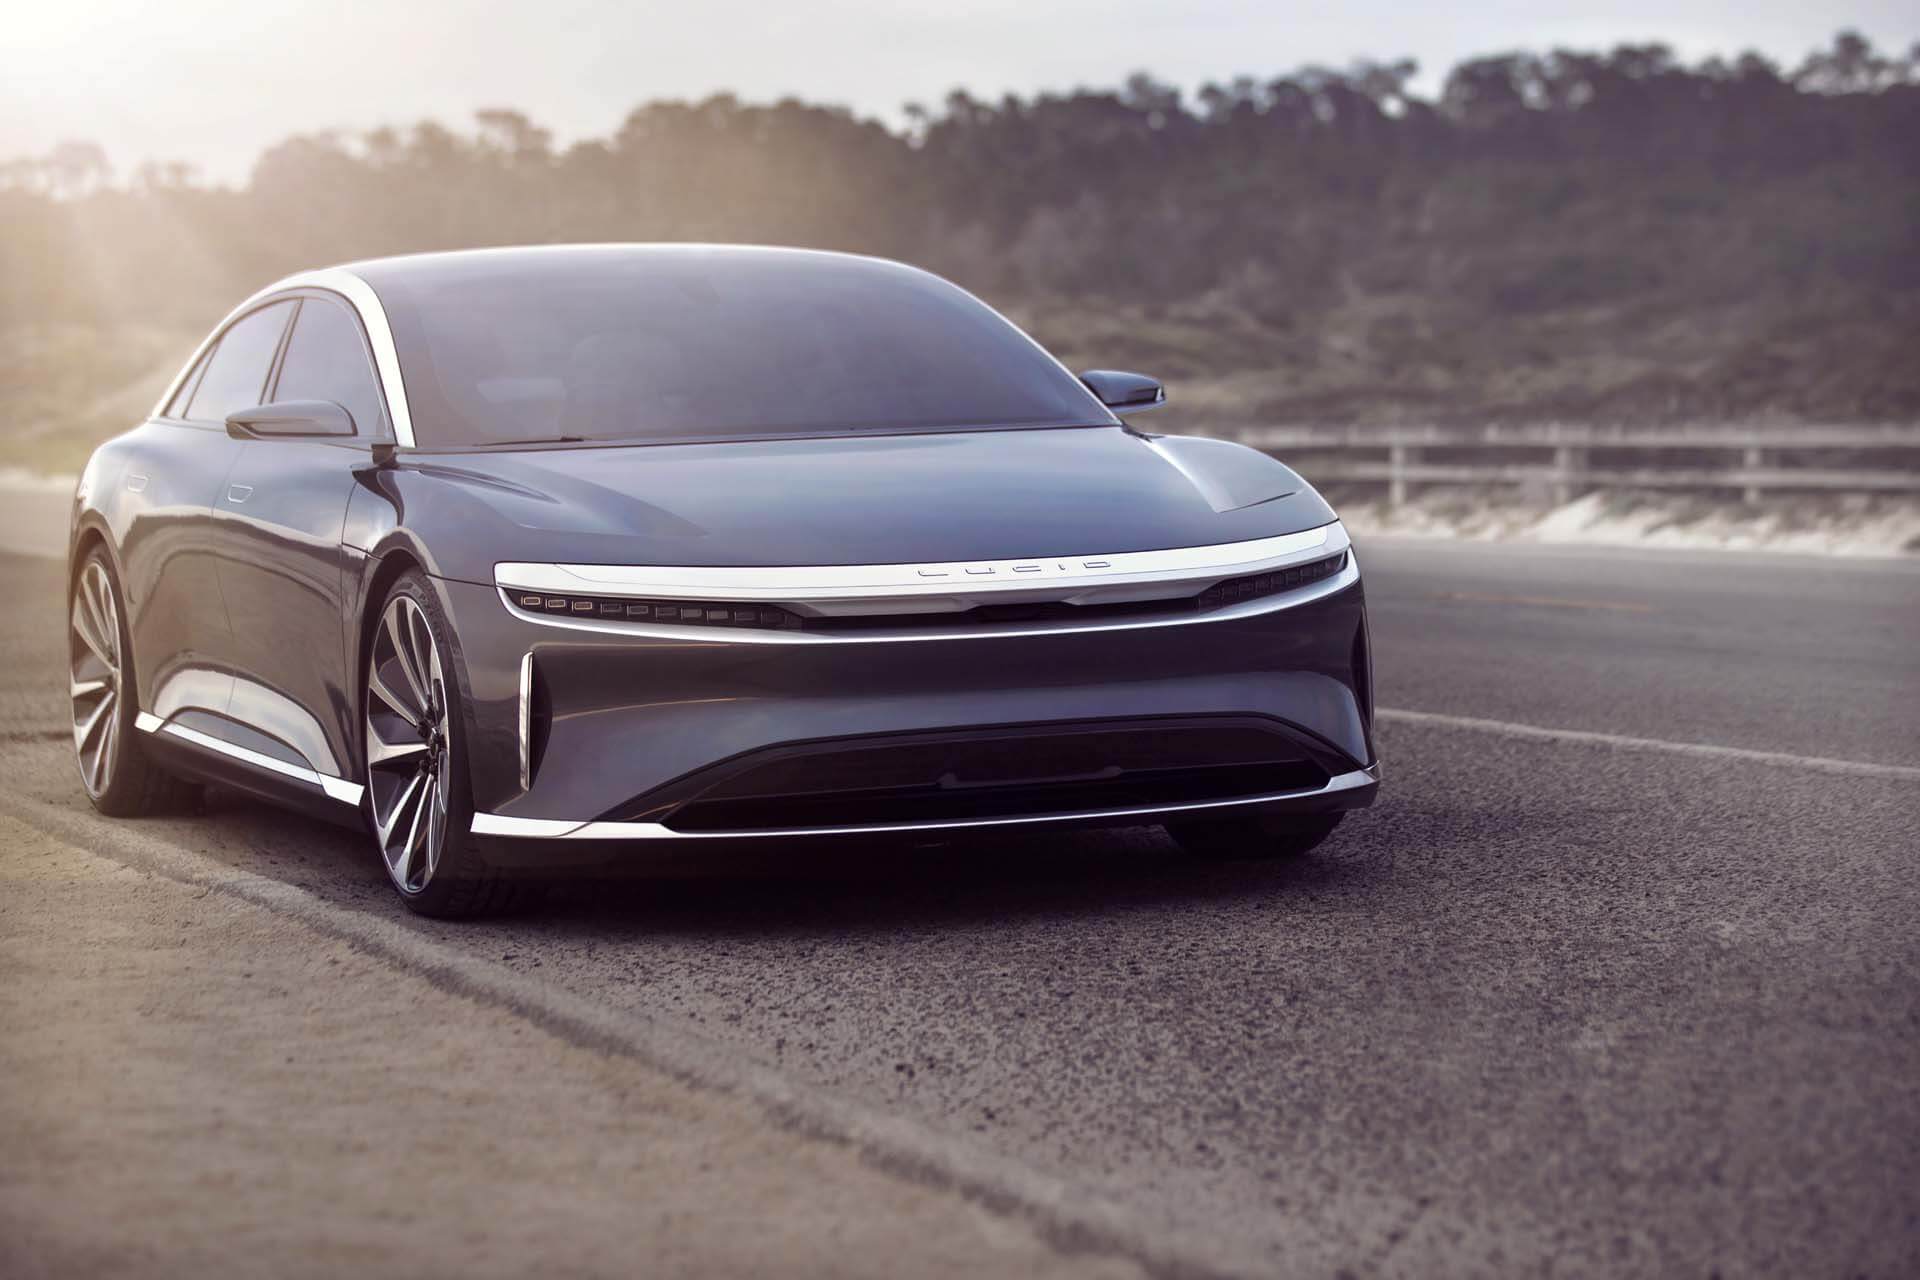
I’ll give them this. The powertrain efficiency is real. The Lucid Air ranked third in the overall large luxury car segment including ICE vehicles in 2025 and drove 520 kilometers on a single charge in Norway’s NAF winter test. The technology deserves respect.
But “best damn car” is bold when your stock is down 65% over the past year, your cost of revenue doubles your revenue, and your liquidity runway extends only into the first half of 2027. Lucid is a real company. Whether it’s viable depends almost entirely on decisions made in Riyadh.
When Lucid starts funding their operations with customers, and I see more Lucids than bald eagles, I’ll start to change my mind.
Contact [email protected] for any questions or corrections.
I've been writing about stocks and personal finance for 20+ years. I believe all great companies are tech companies in the long run, and I invest accordingly.