If You Bought Coca-Cola When Buffett Did, Here’s What You Have Today
Coca-Cola (NYSE: KO | KO Price Prediction) is one of the most famous long-term investment stories in history, starting with Warren Buffett. Berkshire Hathaway began buying Coca-Cola shares in 1988, after the stock had been battered by the 1987 market…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Coca-Cola (NYSE: KO | KO Price Prediction) is one of the most famous long-term investment stories in history, starting with Warren Buffett. Berkshire Hathaway began buying Coca-Cola shares in 1988, after the stock had been battered by the 1987 market crash and Coca-Cola had just completed the disastrous New Coke episode. Buffett saw a globally dominant brand with pricing power, an asset-light model, and the ability to compound dividends for decades. He was right.
63 Years of Raises and a Brand That Never Stopped Printing Cash
The thesis Buffett identified in 1988 has only deepened. Coca-Cola operates in over 200 countries through a franchise model that keeps capital requirements low and cash returns high. CEO James Quincey has layered in new growth vectors: Coca-Cola Zero Sugar posted 14% volume growth for full-year 2025, and the company launched Simply Pop, a prebiotic soda, as a new category bet. The company has raised its dividend for 63 consecutive years, paying out $8.8 billion in dividends in 2025 alone. That consistency is the core of the Buffett thesis, compounding quietly for nearly four decades.
What $1,000 Became at Every Horizon
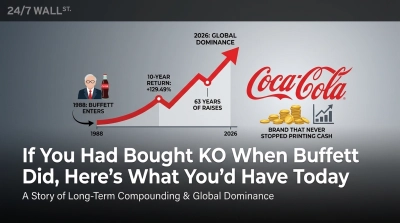
These figures reflect price appreciation only (split-adjusted) and do not include dividend reinvestment, which would meaningfully increase every figure below.
| Return | Current Value | |
| 1-Year Return | 5.64% | $1,056.40 |
| 5-Year Return | 59.26% | $1,592.60 |
| 10-Year Return | 129.49% | $2,294.90 |
| Since Buffett Buy-In | 3,024.71% | $31,247.10 |
Price appreciation alone understates the real return. Coca-Cola has paid rising dividends every year, and an investor who reinvested those dividends would have compounded their position substantially. The current quarterly dividend of $0.53 per share represents significant growth from $0.16 per quarter in 1999. Buffett’s Berkshire collects an enormous annual dividend check on a cost basis from 1988 that is a fraction of today’s price.
The Income Case and the Risks
Coca-Cola suits investors seeking a reliable, low-volatility dividend compounder with a beta of 0.361 and a dividend yield near 2.7%. The bull case rests on pricing power, the Zero Sugar tailwind, and 2026 guidance calling for 4% to 5% organic revenue growth and 7% to 8% comparable EPS growth. Analyst consensus supports this view: 19 of 24 analysts rate it a Buy or Strong Buy, and their $83.67 consensus target is greater than the 52-week high of $82.00.

For investors chasing market-beating returns, the case is weaker. The forward P/E is 23x, a full valuation for a business growing revenue at roughly 2%. Currency headwinds remain persistent, the BODYARMOR acquisition resulted in a $960 million impairment charge in Q4 2025, and ongoing IRS tax litigation adds uncertainty. This is a wealth-preservation and income stock. Buffett has held it for nearly 38 years because it compounds quietly. That is exactly what new buyers should expect today.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.