Warren Buffett’s 1992 ‘Kamikaze Pricing’ warning came true at 3 a.m. on May 2
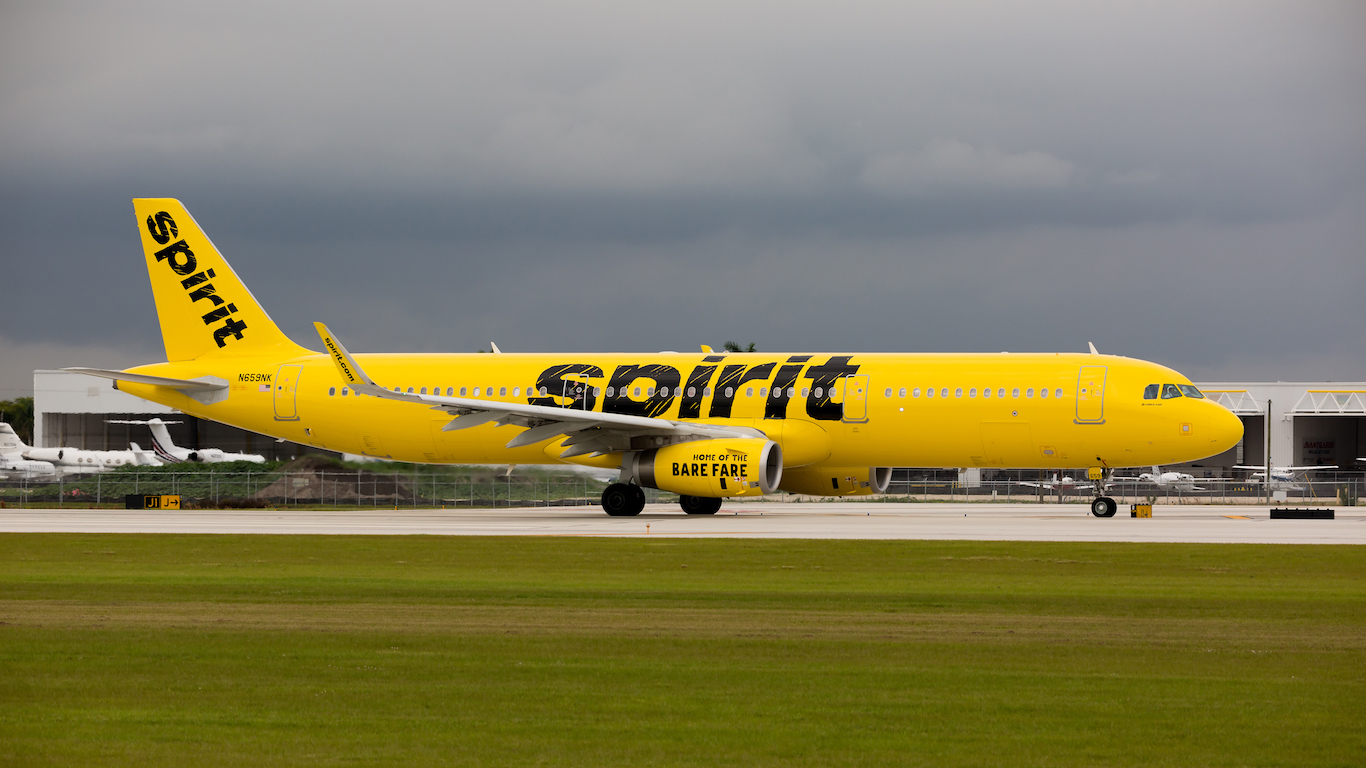
When Spirit Airlines' yellow Airbus fleet went dark at 3:00 a.m. Eastern on May 2, stranding passengers and dissolving 17,000 jobs, the immediate culprits were obvious. A doubled jet fuel bill traceable to the Iran conflict. A bankruptcy court that…

When Spirit Airlines’ yellow Airbus fleet went dark at 3:00 a.m. Eastern on May 2, stranding passengers and dissolving 17,000 jobs, the immediate culprits were obvious.
A doubled jet fuel bill traceable to the Iran conflict. A bankruptcy court that had run out of patience. A group of senior creditors led by Citadel and Ares who refused to subordinate their claims to a federal rescue package.
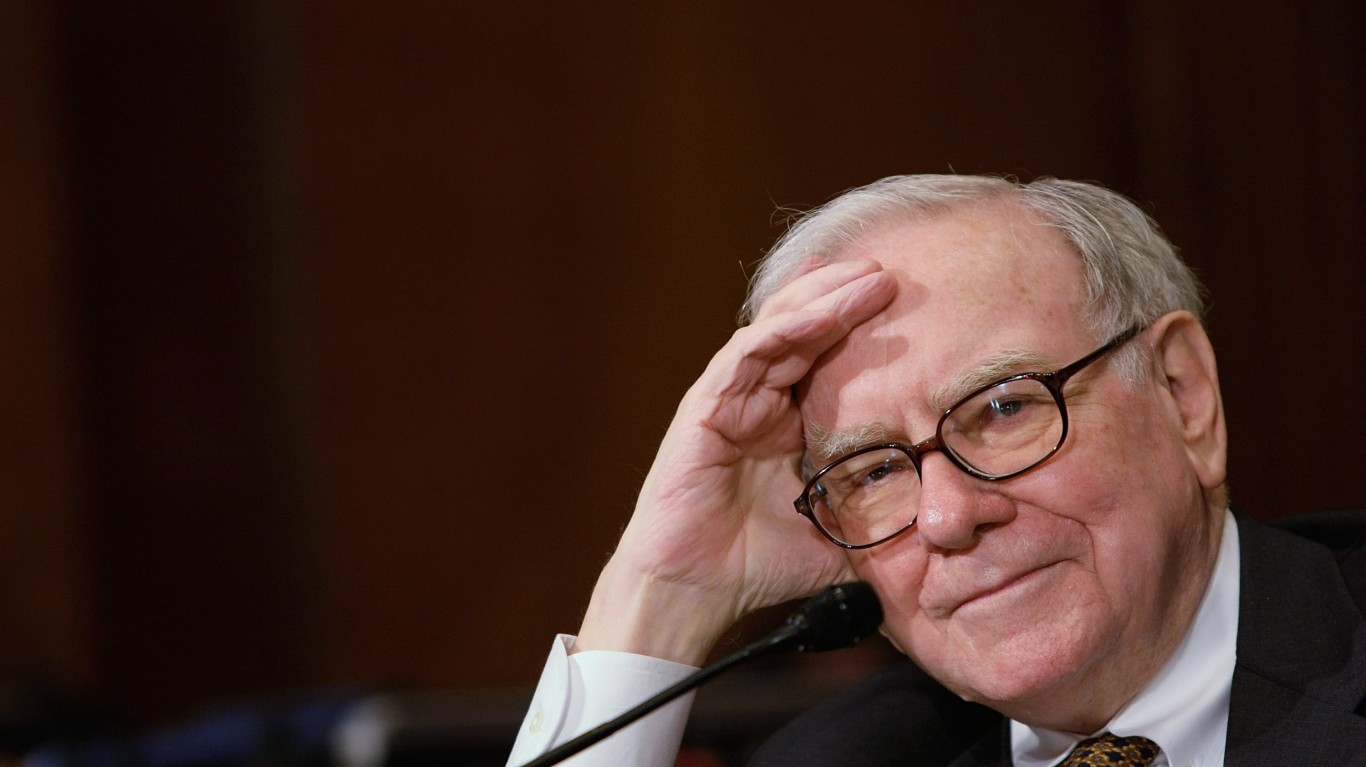
But the deeper diagnosis was written more than three decades earlier, in a Berkshire Hathaway shareholder letter dated 1992.
A thesis written in 1992
In that letter, Warren Buffett delivered what would become his most enduring critique of the airline business. The total profit earned by the entire domestic airline industry since the dawn of powered flight, he argued, was effectively zero. The mechanism he identified was “kamikaze pricing,” a practice common among carriers operating under bankruptcy protection or desperate for cash, in which seats are sold below the cost of providing them.
Because air travel is a commodity sold from a vehicle with extraordinarily high fixed costs, any operator can fill an empty seat at almost any price and improve its day. Aggregate that behavior across an industry, Buffett warned, and you produce a permanent race to the bottom: “In a business selling a commodity-type product, it’s impossible to be a lot smarter than your dumbest competitor.”
The carrier that became the dumbest competitor
Spirit Airlines was, for nearly two decades, that competitor. Its “bare fare” model stripped every service to a base price and sold each amenity back as an ancillary, posting the lowest number on the screen while collecting fees for everything else. The resulting industry-wide downward pressure on yields earned an economic label: the “Spirit Effect.” For a time, Spirit’s cost structure was genuinely lower than that of legacy carriers, and the gap looked like a moat. It was not.
Once Delta, United, and American introduced Basic Economy fares, they could match Spirit on price while offering vastly superior networks, frequent-flier programs, and brand reputations. Spirit’s only differentiator quietly evaporated.
Buffett’s framework predicted exactly this outcome. In a commodity business, the competitor with the lowest cost has an advantage only as long as that cost gap is sustainable, and almost no cost gap in aviation ever is. Labor agreements get matched. IT systems get modernized. Fleets get refreshed. The moat fills in.
When the fuel bill arrived
Spirit’s restructuring plan was built around a fuel cost assumption of $2.24 per gallon for 2026. When U.S. and Israeli forces struck Iran in late February, that assumption became untenable almost overnight. By the end of April, jet fuel had climbed to approximately $4.51 per gallon, and U.S. prices were running roughly 70% above pre-war levels. J.P. Morgan calculated that if fuel held at $4.60 per gallon, Spirit’s projected operating margin for fiscal year 2026 would swing from a positive 0.5% to negative 20%. The airline had no buffer to absorb that swing.
Spirit’s second Chapter 11 filing, initiated in August 2025, had already drained working capital. The Trump administration’s proposed $500 million bailout collapsed when senior lenders refused to cede priority to the government, and the wind-down began hours later.
A vindication priced in dollars
The aftermath reads like the commodity thesis running in reverse. Spirit’s shutdown removed roughly 1.8 million seats from the domestic market, and the pricing effects were felt quickly. Historical data from CBS News found that fares rise an average of 23% on routes Spirit previously served when it exits a market, with passenger volume dropping about 20%. Fort Lauderdale, where Spirit had accounted for nearly 29% of total airport capacity, faced the sharpest exposure. Analysts at Bank of America and TD Cowen welcomed the result because the carrier most responsible for “irrational pricing” had finally exited the market, even as travelers absorbed the cost.
The grounding set off a separate legal front as well. On May 12, former workers filed a class-action lawsuit in U.S. Bankruptcy Court for the Southern District of New York, alleging that Spirit violated the federal WARN Act by terminating approximately 17,000 employees without the required 60-day advance notice. Workers reported they had not received final paychecks, accrued vacation pay, or unused sick time.
Buffett himself said nothing about Spirit’s demise. He handed the CEO role to Greg Abel on January 1, 2026, and has stepped back from individual security commentary. The $397 billion cash pile Abel inherited at the end of the first quarter, parked overwhelmingly in Treasury Bills, was the comment, though Abel has since begun deploying it: by the end of the second quarter Berkshire’s cash position had declined to $365.5 billion as Abel initiated buybacks and made new equity investments.
The 1992 letter still describes the business it describes. Spirit’s tail numbers ferrying empty to the Arizona desert are simply the latest receipts.
Editor’s note: This article has been updated to include the J.P. Morgan margin estimate based on $4.60-per-gallon fuel, the confirmed fuel price of $4.51 per gallon at end of April 2026, the 1.8 million seats removed from the market, the 23% historical average fare increase on Spirit-exited routes, Fort Lauderdale’s 29% capacity exposure, the WARN Act class-action lawsuit filed May 12 by former Spirit employees, and updated context on Berkshire Hathaway’s cash position reflecting Greg Abel’s second-quarter capital deployments, which reduced the cash pile from a record $397 billion to $365.5 billion.
Contact [email protected] for any questions or corrections.
Don Lair writes about options income, dividend strategy, and the kind of boring-but-durable investing that actually funds retirement. He's the founder of FITools.com, an independent contributor to 24/7 Wall St., and a former writer for The Motley Fool.