Prediction: Shopify Will Trade at This Price in Two Years
Shopify (NASDAQ:SHOP | SHOP Price Prediction) is one of the most polarizing growth stories in software right now. The platform processed $123.84 billion in gross merchandise volume in Q4 2025 alone, grew revenue 30.58%, and commands over 14% of US…

Shopify (NASDAQ:SHOP | SHOP Price Prediction) is one of the most polarizing growth stories in software right now. The platform processed $123.84 billion in gross merchandise volume in Q4 2025 alone, grew revenue 30.58%, and commands over 14% of US ecommerce.
Yet the stock is down 26.25% year-to-date. It trades at $118.71, far below where fundamentals suggest it could go. The question is whether shares can reach $200 by 2028.

Why Shopify Shares Are Stuck Despite 30% Revenue Growth
The headline problem is earnings optics. Net income fell 42.54% year-over-year in Q4 2025 and 39.03% for full-year 2025. The decline stems almost entirely from mark-to-market accounting on equity investments. Operating income rose 35.7% in Q4. Free cash flow grew 17.02% to $715 million.
SHOP is down 2.1% over the past month and 26.25% year-to-date, with a beta of 2.644 that amplifies macro shocks. After touching $159.85 in December, shares fell to a 52-week low of $94 before recovering 15.25% over the past week. This high-beta stock faces a market that has lost appetite for growth.
Wall Street Sees 26% Upside. Our Model Disagrees
The Street is firmly bullish. The consensus target sits at $150.11, with 10 Strong Buys, 29 Buys, 12 Holds, and one Sell. Bullish sentiment is 75%.
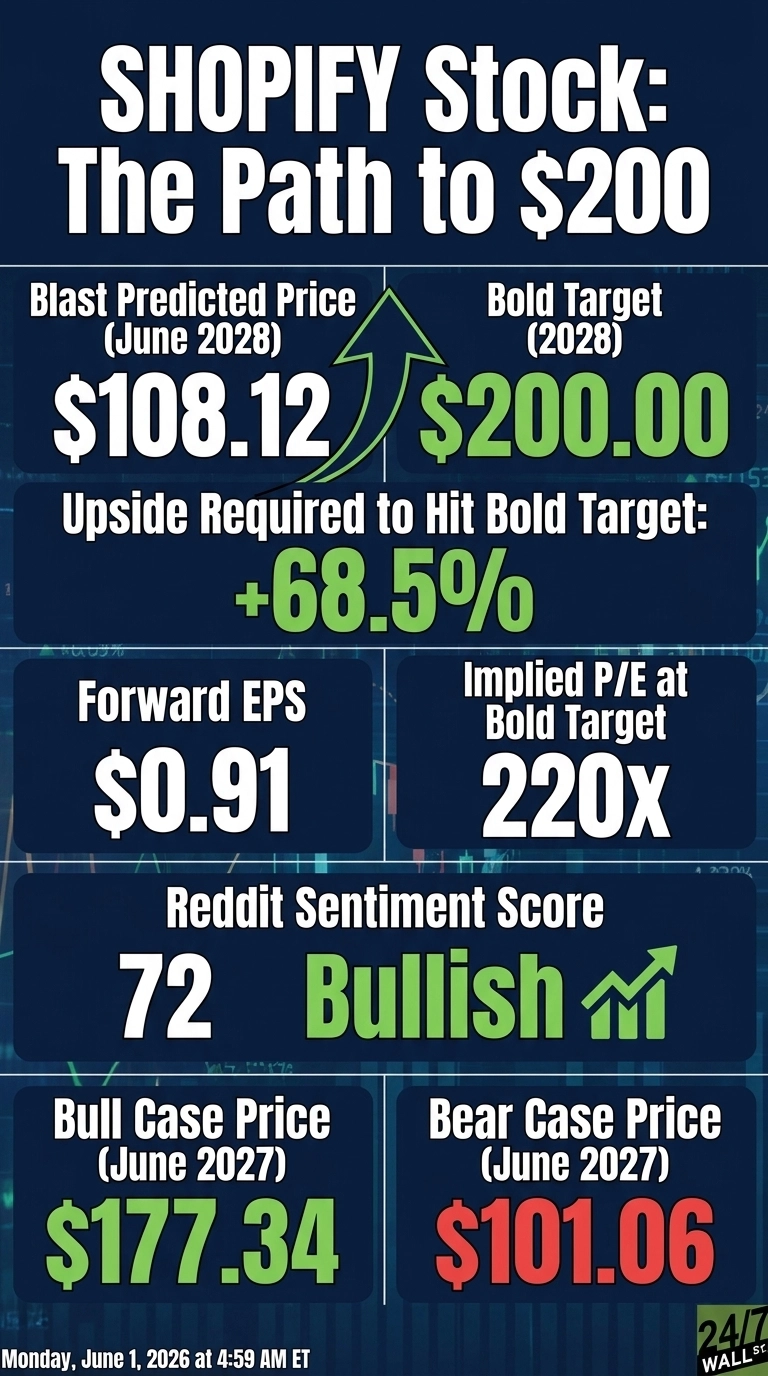
My model is more cautious near-term. The base case lands at $108.12 by mid-2027, implying -8.92% total return with 90% confidence. The optimistic scenario hits $177.34, and the conservative case is $101.06.
Wall Street anchors on real operating leverage but underweights multiple compression risk while EPS optics remain poor. Strip out accounting noise and growth justifies a premium. The Street is right directionally, but the 12-month price target is too aggressive.
The Path to $200 Per Share
Reaching $200 from $118.71 requires a 68.5% gain. That is a stretch.
With forward EPS of $0.91, $200 implies a forward P/E of 220x. Our base case of $108.12 already implies 165x, meaning the bold target requires roughly 55x additional multiple expansion. That math works only if forward EPS estimates climb materially as equity-investment noise normalizes.
The bull setup: Q1 2026 guidance points to low-thirties revenue growth, continuing 11 straight quarters of 25%+ growth. B2B GMV grew 96% in 2025 and international revenue rose 36%. The $2 billion buyback authorized February 17, 2026 will shrink share count. If 2026 EPS roughly doubles as accounting drag clears, the 220x multiple becomes digestible. The primary risk is consumer-spending slowdown cutting GMV growth in half.

Where Shopify Trades Today vs Its Earnings Power
At $118.71, SHOP carries a forward P/E of 130x on $0.91 EPS. Rich, but distorted by mark-to-market losses that shouldn’t recur at this magnitude. Shares sit 18% below the 52-week high of $182.19 and well off the low of $94. The 10-year return is 3,952.92%, a reminder of compounding when a platform takes share. The five-year return is -4.49%. That gap is where the bull case lives.
Is $200 Realistic?
Reaching $200 by 2028 requires a 68.5% gain. Realistic, but a clear stretch.
Three things must go right: EPS optics must normalize as equity-investment volatility settles, revenue growth must hold above 25% through 2027 via international and B2B expansion, and the buyback must absorb meaningful float. A consumer recession would derail the thesis. We’ve outlined the blueprint for how Shopify could reach $200 in 2028.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.