One Semiconductor Stock Could Surprise Investors Over the Next 3 Years
Marvell Technology has quietly become one of the purest AI infrastructure plays in semiconductors, but the real question is whether its explosive run has already priced in the future or if a case exists for another 79% gain from here.

Over time, Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction | MRVL Price Prediction) has become one of the purest AI infrastructure plays in semiconductors. Data Center revenue hit a record $2.17 billion last quarter, up 46% year over year, and now makes up 79% of sales.
Shares are up 228.02% year to date at $278.35. Near-term forecasts still look modest next to fundamentals like these. That gap leads to my question: can Marvell reach $500 per share by 2029?

What’s Holding Marvell Back Right Now
Marvell’s problem is its own momentum. A 228.02% YTD run pulled years of growth into the price. Shares gained 5.35% in a week and 24.51% in a month, then slipped 2.22% today.
A beta of 2.26 means violent moves: the stock went from $278.67 in mid-June to $188.30 by mid-July. Customer concentration among a few hyperscalers adds risk, and Communications revenue is guided to fall in the low to mid-teens percentage range in Q3.
Wall Street Sees Modest Upside. Estimates Point Higher
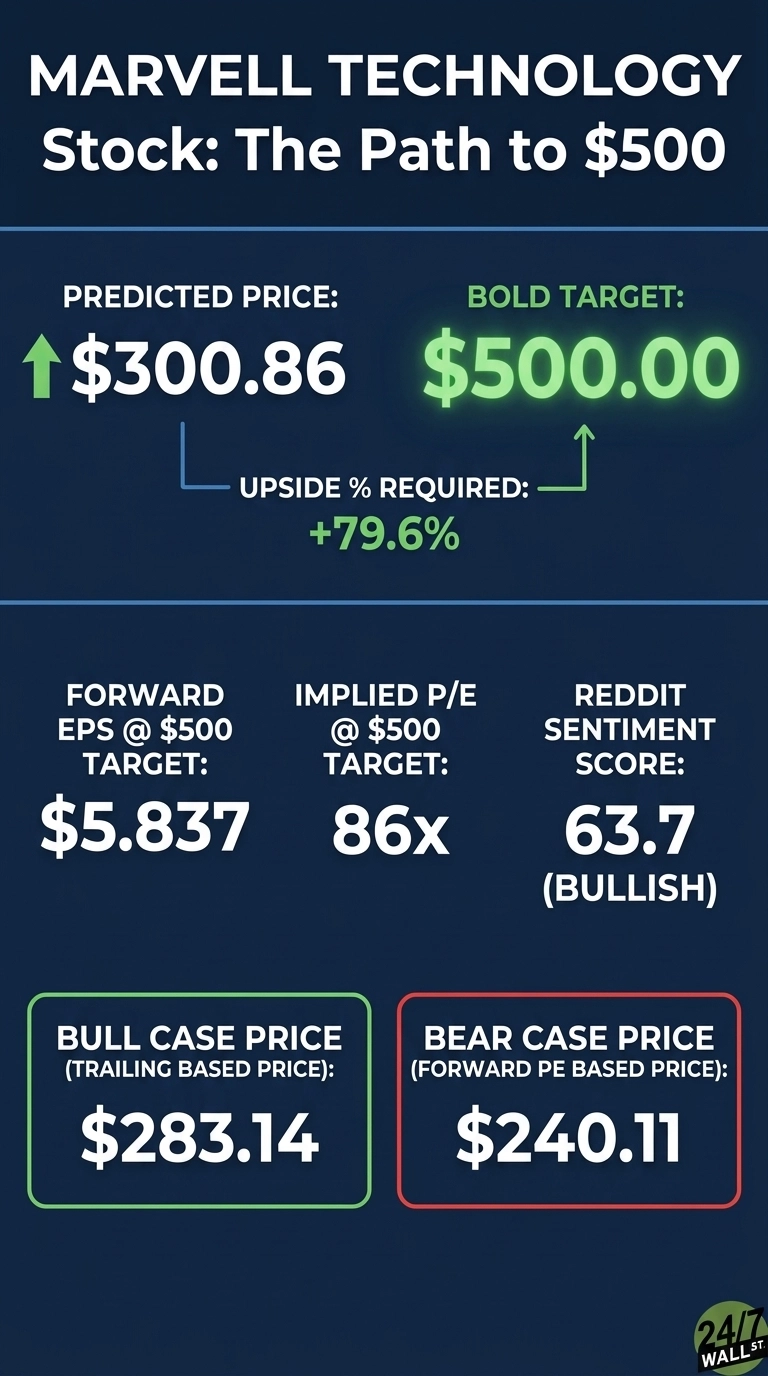
The consensus target is $293.88, about 5.6% above today’s price, backed by 8 Strong Buy, 32 Buy, 6 Hold, plus 0 Sell ratings. The $300.86 base case implies 8.1% upside, inside a one-year range of $229.67 to $354.70, with high confidence of 0.9.
I think targets lag the earnings. With 87% of analysts bullish and earnings growth contributing 0.03 to our model, fiscal 2028 EPS consensus rose from $6.1726 to $6.7609 in 90 days.

Here’s What It Takes for Marvell to Reach $500
A jump to $500 from the current price of $278.35 would require a gain of 79.6%.
With forward EPS of $5.837, $500 would translate to a forward P/E of 86x. The $300.86 base case already implies 52x, meaning the bold target requires 34x of additional multiple expansion.

Earnings growth does the heavy lifting. On fiscal 2028 consensus EPS, $500 equals about 74x, and management expects fiscal 2028 revenue growth of approximately 50%.
Reuters reported Marvell raised its 2028 revenue forecast on strong AI data center demand, and Morningstar raised its valuation on bullish long-term guidance.
An expanded Google deal includes a warrant for up to 7% of shares tied to revenue milestones. Matt Murphy, the CEO, said “AI-related bookings remain exceptionally robust.” The primary risk is a hyperscaler capex pause hitting a premium multiple.
Where Marvell Trades Today vs Its Earnings Power
Marvell trades at about 48x forward EPS. That is expensive, yet reasonable for guidance of more than 50% revenue growth in Q3. Shares sit between a 52-week low of $70.64 and a high of $329.80.
The 10-year return of 2,174.21% shows how Marvell compounds when a cycle catches. If earnings outrun the multiple, the forward P/E would contract at today’s price.
Is $500 Realistic? Here’s My Take
$500 by 2029 requires a 79.6% gain, above our three-year bull case of $436.77. My verdict: a stretch, yet reachable.
Custom revenue must more than double in fiscal 2028, scale-up optics must ramp, and operating margins must hit the upper end of the 38% to 40% target. An AI spending slowdown would disrupt it. Such returns are rare in any single year, and we’ve outlined the plan for how Marvell could reach $500 in 2029 (we also reverse-engineered what the biggest tech winners looked like early in a free playbook you can grab here).
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.