Prediction: Tesla Stock Will Hit $500 on This Date
Tesla (NASDAQ:TSLA | TSLA Price Prediction) sits in an awkward place. Q1 2026 showed automotive gross margin rebounding to 21.1% from 16.2% a year earlier, FSD subscriptions hit 1.28 million (+51% YoY), and free cash flow more than doubled to…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Tesla (NASDAQ:TSLA | TSLA Price Prediction) sits in an awkward place. Q1 2026 showed automotive gross margin rebounding to 21.1% from 16.2% a year earlier, FSD subscriptions hit 1.28 million (+51% YoY), and free cash flow more than doubled to $1.444 billion.
Yet shares closed at $418.45, down 6.95% YTD. Can Tesla reach $500 this cycle?

What’s Holding Tesla Back
The stock is stuck because investors cannot decide which Tesla they own. Shares are off 5.35% in the last week alone, even after rallying 7.47% over the past month. With a beta of 1.79, every macro wobble gets amplified.
The bigger overhang is strategic. Prediction markets peg a SpaceX-Tesla merger by year-end at just 42.5% probability, and the dominant view is that a combined entity would lose money on day one. Add in 43 recent insider transactions tilted toward selling, energy revenue down 12% YoY, and inventory rising to 27 days of supply, and buyers are hesitating.
Wall Street Sees Modest Upside
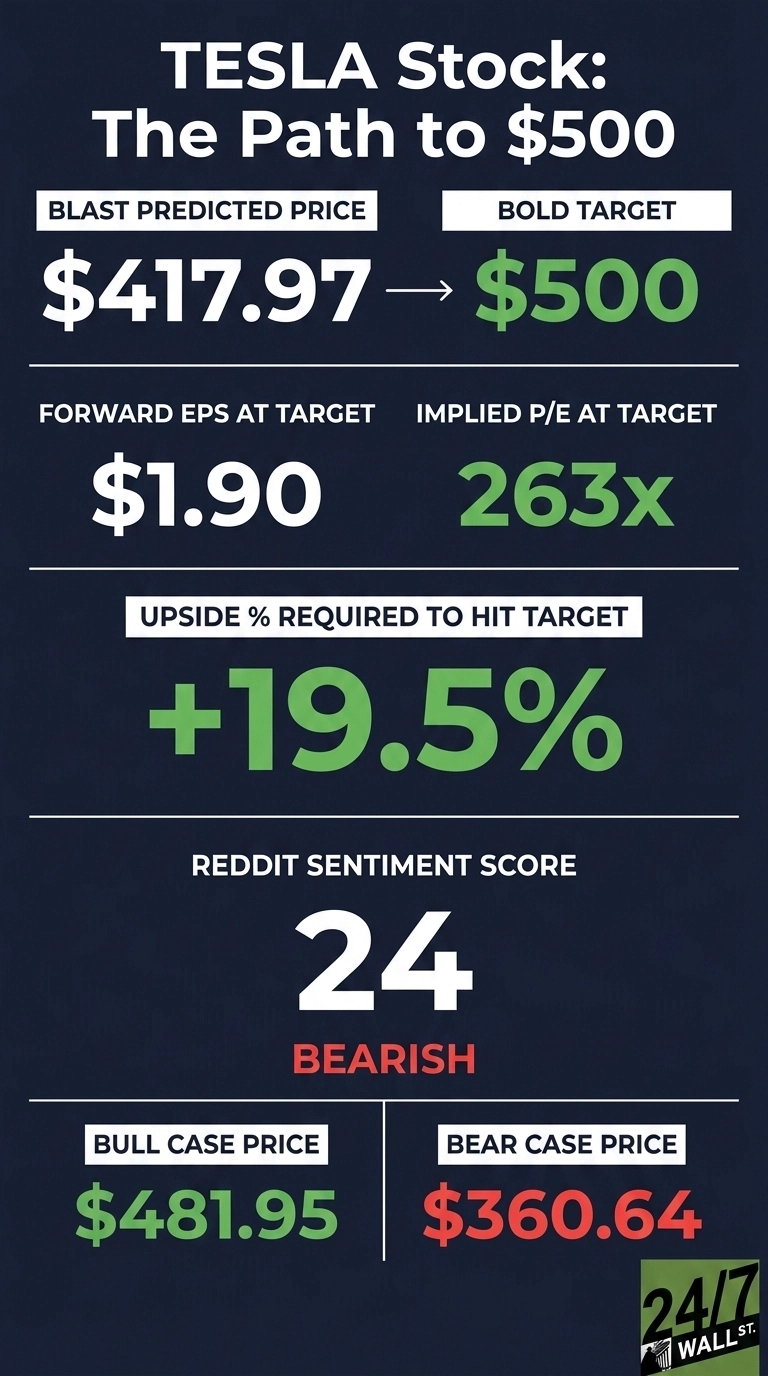
Consensus is lukewarm. The Street’s average price target sits at $411.89, slightly below current price, with 5 Strong Buy, 18 Buy, 17 Hold, 4 Sell, and 3 Strong Sell ratings. My base case lands at $417.97 with 90% confidence, calling fair value. The bull scenario clocks in at $481.95, the bear at $360.64.

Only 49% of analysts are bullish, which undersells the operating leverage here. Q1 operating income jumped 135.84% YoY on modest revenue growth. That signals a business at an inflection point.
The Path to $500
Reaching $500 from today’s $418.45 requires a gain of 19.5%. With a forward EPS of $1.90, a $500 price implies a forward P/E of 263x. My base case at $417.97 already implies 231x, meaning the bold target needs roughly 32x additional multiple expansion.
That is substantial but not impossible if EPS growth accelerates. Catalysts include Cybercab, Tesla Semi, and Megapack 3 entering volume production in 2026, plus Optimus production lines at Fremont.
FSD v14.3 cut inference latency by up to 20%, and unsupervised Robotaxi rides are live in Dallas and Houston. Hit those milestones and forward EPS estimates move higher fast. Main risk: merger drama with SpaceX or xAI that confuses the equity story.
Valuation Today vs Earnings Power
At $418.45, Tesla trades at roughly 220x forward earnings of $1.90. That is rich on any backward-looking lens. Shares sit between a 52-week high of $498.83 and a low of $281.85, currently 17% off the high. Over 10 years, TSLA is up 2,744.28%, so the long-term compounding case is undeniable. The bull thesis to $500 asks whether autonomy and Optimus justify that triple-digit multiple.
Is $500 Realistic?
$500 requires a 19.5% move, and the 52-week high already brushed $498.83, so the level is not fantasy.
Three things need to go right: Q2 deliveries land in the 450,000 to 475,000 range the crowd expects, FSD subscriber growth stays north of 50% YoY, and SpaceX merger noise resolves cleanly.
What derails it: another quarter of regulatory-credit erosion paired with weak Optimus traction. Prediction markets assign 17% probability to $495 in June, so I am not promising it happens fast. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Tesla could reach $500 in 2026.

Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.