AppLovin Could Hit $600+ With 28% Upside as AI Ad-Tech Story Rebounds
AppLovin (NASDAQ:APP | APP Price Prediction) has had a wild ride in 2026. After a blistering 2025 that pushed shares higher, the stock has cooled meaningfully, leaving investors wondering whether the AI ad-tech story is broken or simply digesting gains.…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

AppLovin (NASDAQ:APP | APP Price Prediction) has had a wild ride in 2026. After a blistering 2025 that pushed shares higher, the stock has cooled meaningfully, leaving investors wondering whether the AI ad-tech story is broken or simply digesting gains. My read leans toward the latter, and the 24/7 Wall St. price target reflects that.
Our price target for AppLovin is $603.42, implying roughly 28.47% upside from the current price of $469.71. The recommendation is buy at a 90% confidence level, which is among the highest readings our model assigns.
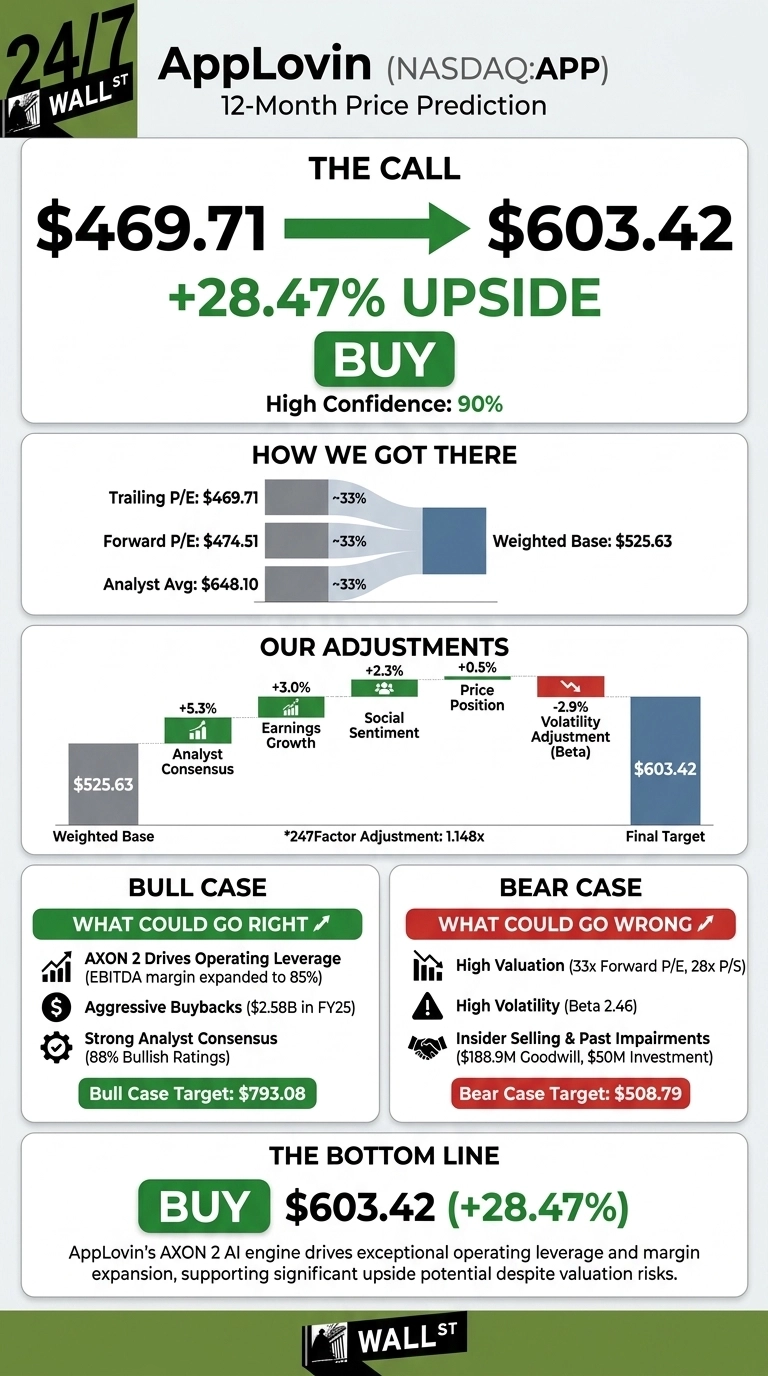
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $469.71 |
| 24/7 Wall St. Price Target | $603.42 |
| Upside | 28.47% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Volatile 2026 Has Reset Expectations
AppLovin is down 30.29% year to date, with shares slipping 1.85% over the past week and sitting 13% below the 52-week high of $745.61. Over a one-year window, however, the stock is still up 36.4%, and the five-year return of 432.49% reflects the payoff from the company’s pivot to a pure-play ad-tech model powered by the AXON 2 AI engine.
The fundamentals remain exceptional. Q1 FY26 revenue of $1.84B rose 24.15% YoY and beat estimates, while EPS of $3.56 topped the $3.46 consensus. Operating income jumped 117% YoY to $1.44B at a 78% margin, and the team returned $1B to shareholders through buybacks in the quarter.

Why Bulls See a Breakout Ahead
The bull case rests on AXON 2’s operating leverage. Adjusted EBITDA margin expanded from 81% in Q2 2025 to 85% in Q1 2026, and Q2 2026 guidance calls for revenue of $1.915B to $1.945B at 84-85% EBITDA margins. Free cash flow of $3.95B in FY25 funds aggressive buybacks, with 6.4M shares retired for $2.58B last year.
With 7 Strong Buy and 21 Buy ratings against just 4 Holds, the Street is loud. Our bull case scenario points to $793.08 over the next year, a 68.84% total return, if e-commerce ad expansion accelerates.

The Risks Worth Watching
The bear case starts with valuation. APP trades at a forward P/E of 33x and a P/S of 28x. A beta of 2.46 means any AI sentiment crack hits hard. Insider activity skews to selling across 165 transactions, and FY25 included a $188.9M goodwill impairment plus a $50M investment writedown.
Bulls would counter that these charges tie back to the Apps divestiture to Tripledot Studios for $400M cash plus 20% equity, a cleanup move that sharpens the pure-play ad-tech focus. Our bear case still nets a $508.79 target.
AppLovin Price Prediction 2026-2030
The 24/7 Wall St. price target of $603.42 with 90% confidence keeps me constructive. The decisive factor is operating leverage: net margin expanded to 65% while revenue grew 24%.
The constructive case strengthens if AXON 2 continues compounding ad pricing and impressions into 2027. The thesis weakens if forward guidance signals deceleration below 20% growth or if the e-commerce vertical disappoints.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $603 |
| 2030 | $969 |
These projections assume AppLovin continues executing on AXON 2 monetization and e-commerce ad expansion. Significant upside could come if connected TV ad share grows materially, while downside risk centers on platform policy shifts at Apple or Google.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.