Will Snowflake Reach $300 This Year?
Snowflake (NYSE:SNOW | SNOW Price Prediction) has been one of 2026’s most violent round trips, plunging to $144.48 in April before ripping back above $230. The question on every shareholder’s mind is whether the AI data cloud narrative can carry…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Snowflake (NYSE:SNOW | SNOW Price Prediction) has been one of 2026’s most violent round trips, plunging to $144.48 in April before ripping back above $230. The question on every shareholder’s mind is whether the AI data cloud narrative can carry shares to $300 this year. Our model says the path is real, but not quite there in 12 months.
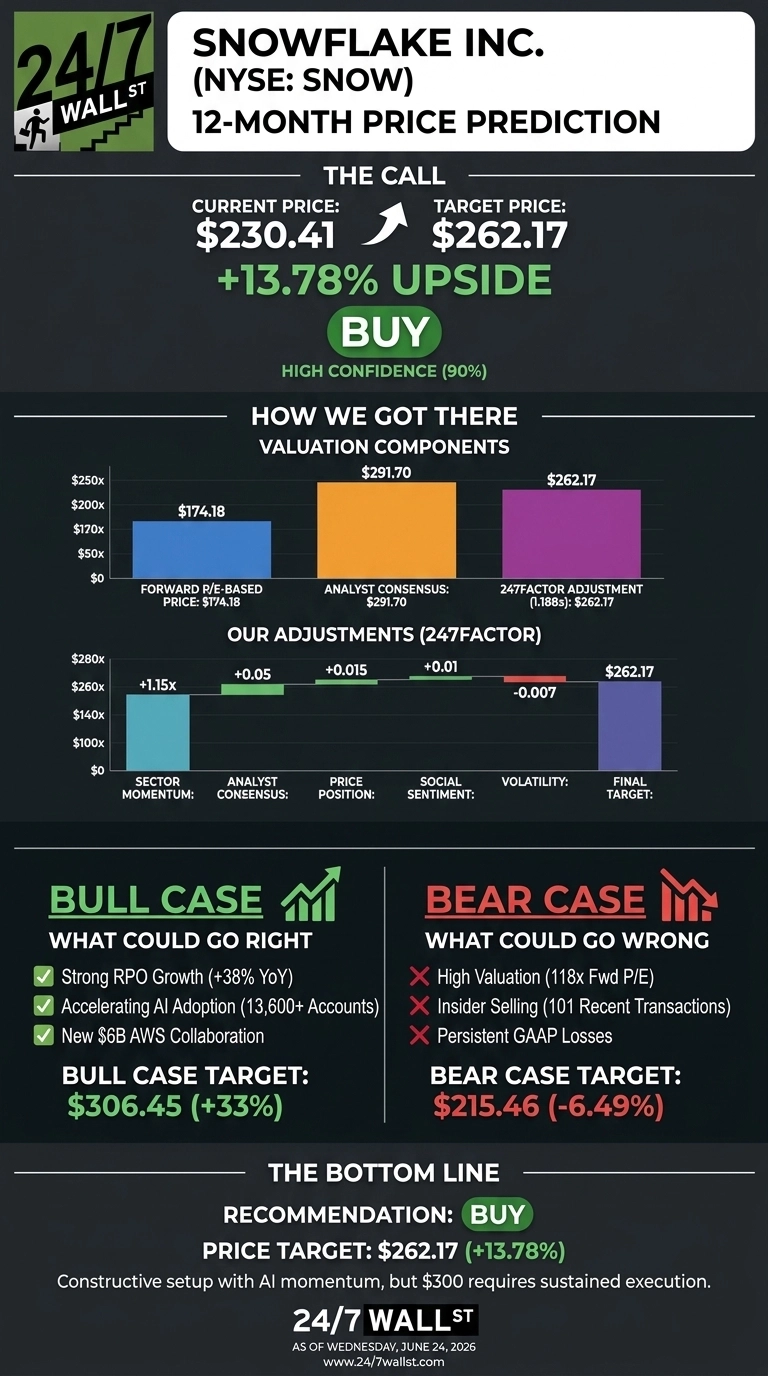
Our 24/7 Wall St. price target for Snowflake is $262.17, implying 13.78% upside from $230.41. We rate the stock a buy with high (90%) confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $230.41 |
| 24/7 Wall St. Price Target | $262.17 |
| Upside | 13.78% |
| Recommendation | BUY |
| Confidence Level | 90% |
From $144 to $230: A Violent Recovery
Snowflake is up 33.8% over the past month and 5.04% year to date, sitting 2% below its 52-week high of $284.99.
The fuel was a blowout Q1 FY27 earnings report on May 27, 2026: revenue of $1.39 billion grew 33.5% YoY, beating estimates by 5.13%, while non-GAAP EPS of $0.39 beat by 21.95%. Management raised full-year product revenue guidance to $5.84 billion (31% growth) and lifted non-GAAP operating margin guidance to 13.5%.
The deal flow is equally aggressive: a new $6 billion multi-year AWS collaboration, a deepened OpenAI partnership, the Natoma acquisition for AI agent infrastructure, and SAP integration now in general availability.
The Case for $306 and Beyond
Bulls have a clean story. RPO of $9.21 billion grew 38% YoY, net revenue retention sits at 126%, and 13,600+ accounts are now using Snowflake AI. CEO Sridhar Ramaswamy framed Q1 as “a clear inflection point” as Snowflake becomes “the control plane for the Agentic Enterprise.”
Our bull case projects $306.45 by June 2027, a 33% gain. Wedbush, Morgan Stanley, and others sit in the $291.70 consensus with 9 Strong Buy and 35 Buy ratings.
What Could Go Wrong
The bear case is valuation. Snowflake trades at 15.6x trailing sales and 118x forward earnings while still posting GAAP losses (-$326 million operating loss in Q1). Insider activity skews to net selling across 101 recent transactions, and stock-based compensation remains elevated.
Our bear case projects $215.46, a 6.49% decline. Counterpoint: the GAAP losses largely reflect SBC, and the consumption model that creates revenue variability is the same model producing $232.8 million in quarterly free cash flow.
Snowflake Price Prediction 2026-2030
The 24/7 Wall St. price target of $262.17 says yes to buy but no to $300 in 12 months. Reaching $300 requires the bull scenario, which our model gives meaningful but not majority weight. T
he setup looks constructive if Q2 product revenue lands above the $1.42 billion guide and AI account growth keeps compounding. The thesis weakens if NRR slips below 120% or operating margin guidance gets walked back. The risk/reward favors patient accumulation.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $262 |
| 2027 | $290 |
| 2028 | $315 |
| 2029 | $335 |
| 2030 | $355 |
These projections assume Snowflake sustains 25%+ product revenue growth and continues margin expansion. Significant upside could come from agentic AI monetization; downside risk centers on consumption optimization by enterprise customers.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.