The $1 Trillion Question Facing Palantir Stock
Palantir just posted growth numbers that humiliated Wall Street estimates, yet the stock still needs to more than double before it touches a trillion-dollar valuation. Here is what the math actually says about whether that gap ever closes.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
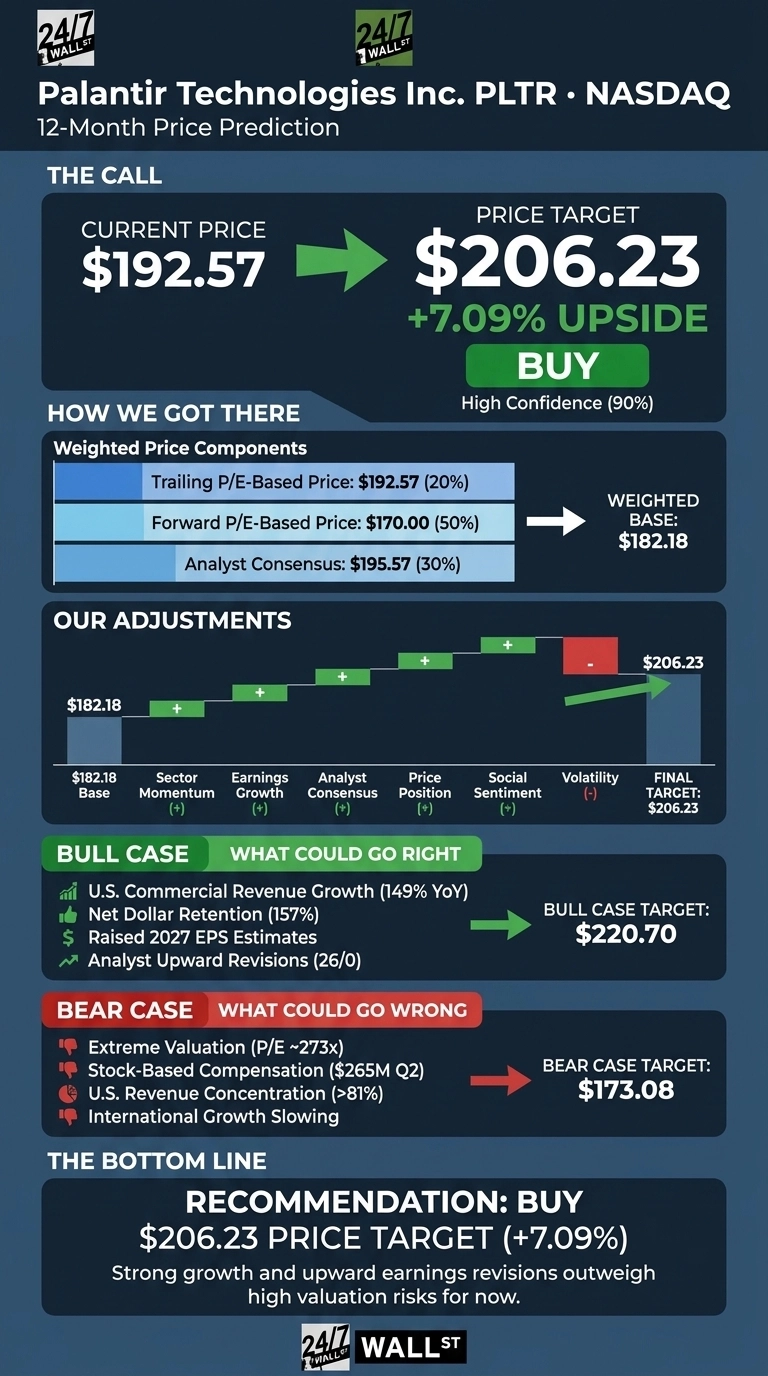
Palantir (NASDAQ:PLTR | PLTR Price Prediction) carries a market cap of $440.66B. Reaching $1 trillion would take roughly 2.27x that value, or about $434.65 per share. The 24/7 Wall St. price target of $206.23 over the next 12 months is a more modest step toward that number.
| Metric | Value |
|---|---|
| Current Price | $192.57 |
| Price Target from 24/7 Wall St. | $206.23 |
| Upside/Downside | 7.09% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model rates Palantir a buy with high confidence. Fundamentals are speeding up faster than the share price, which keeps the upside moderate but real.
A Record 93% Growth Quarter Brought Palantir Shares Back
Shares traded at $191.53 Friday afternoon. That is up 8.68% over the past week, 10.88% over the past month and 7.75% year to date, and well above the $133.25 close on June 16. The stock sits about 6% below its 52-week high of $207.52 and 80% above its low of $106.37.
The Q2 earnings report on August 3 showed EPS of $0.41, beating the $0.28 estimate. Revenue rose 92.8% to $1.935B, and U.S. commercial revenue climbed 149%. Management raised full-year revenue guidance to $8.150-8.158B. CEO Alex Karp said “demand for AI sovereignty has now been unleashed.”

Why Bulls See $220 and Beyond
The bull case reaches $220.70. Several numbers support it:
- Total remaining deal value hit $13.1 billion, up 83%.
- Net dollar retention reached 157%.
- Analysts raised their 2027 EPS consensus to $2.3230 from $2.0821 90 days ago. Over the past 30 days there were 26 upward revisions and none down.

Karp is aiming “to grow at a rate equal or above to what we have in U.S. commercial for the next 18 months.” Wall Street has 21 Buy ratings, 9 Holds and 2 Sells on the stock.

What Could Pull Palantir Back to $173
The bear case sits at $173.08. The stock trades at 273x trailing earnings. Stock-based compensation totaled $265M in Q2, and the U.S. accounts for over 81% of revenue. International commercial grew only 26%, and government contracts can be terminated for convenience.
Management also noted a “significant ramp in expense” for Q3. That spending pays for hiring and product work, and it comes with a GAAP operating margin already at 47%.
How Palantir Stacks Up Against Snowflake and Datadog
Snowflake (NYSE:SNOW) competes directly in data sovereignty, while Datadog (NASDAQ:DDOG) is a benchmark for fast-growing enterprise software.
| Company | Latest Revenue Growth | Market Cap |
|---|---|---|
| Palantir | 92.8% | $440.66B |
| Snowflake | 35.09% | $117.83B |
| Datadog | 35.64% | $90.93B |
Snowflake trades at 105x free cash flow and still posts GAAP operating losses. Palantir trades at 211x but makes a GAAP profit.
Datadog raised its outlook to $4.45-4.47 billion in 2026 revenue, about half of Palantir’s guidance. Palantir’s growth is well ahead of both peers, which makes our target look reasonable, if not conservative.
Palantir Price Prediction 2026-2030
The 24/7 Wall St. price target of $206.23 carries a buy rating with 90% confidence. What tips the scale is upward earnings revisions with no cuts.
I’d grow more confident if U.S. commercial growth holds above 100%. I’d grow more conservative if bookings slow while the stock still trades near 94x forward earnings. For now, growth keeps outpacing valuation concerns.
These base-case figures continue the 24/7 Wall St. price target model.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $192.49 |
| 2027 | $207.57 |
| 2028 | $225.76 |
| 2029 | $226.45 |
| 2030 | $241.37 |
The projections rest on Palantir continuing its current strategy. Even at the 2030 figure, the stock would be well short of the roughly $434.65 per share a $1 trillion valuation requires.
Growth in sovereign AI demand that runs ahead of forecasts is the catalyst that could close that gap (we reverse-engineered what the biggest tech winners looked like early and put the pattern in a free playbook here).
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.