Two AI Stocks, Two Price Targets: What’s Next for AMD and Palantir
Palantir has cratered while AMD has gone parabolic, yet our model hands both the same rating and confidence score. The reasoning behind that call reveals a tension in AI investing that most price targets ignore.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Two of the market’s most talked-about AI plays sit on very different footings this summer. Palantir (NASDAQ:PLTR | PLTR Price Prediction) has cooled after a torrid run, while AMD (NASDAQ:AMD) has ripped higher on accelerating Data Center demand.
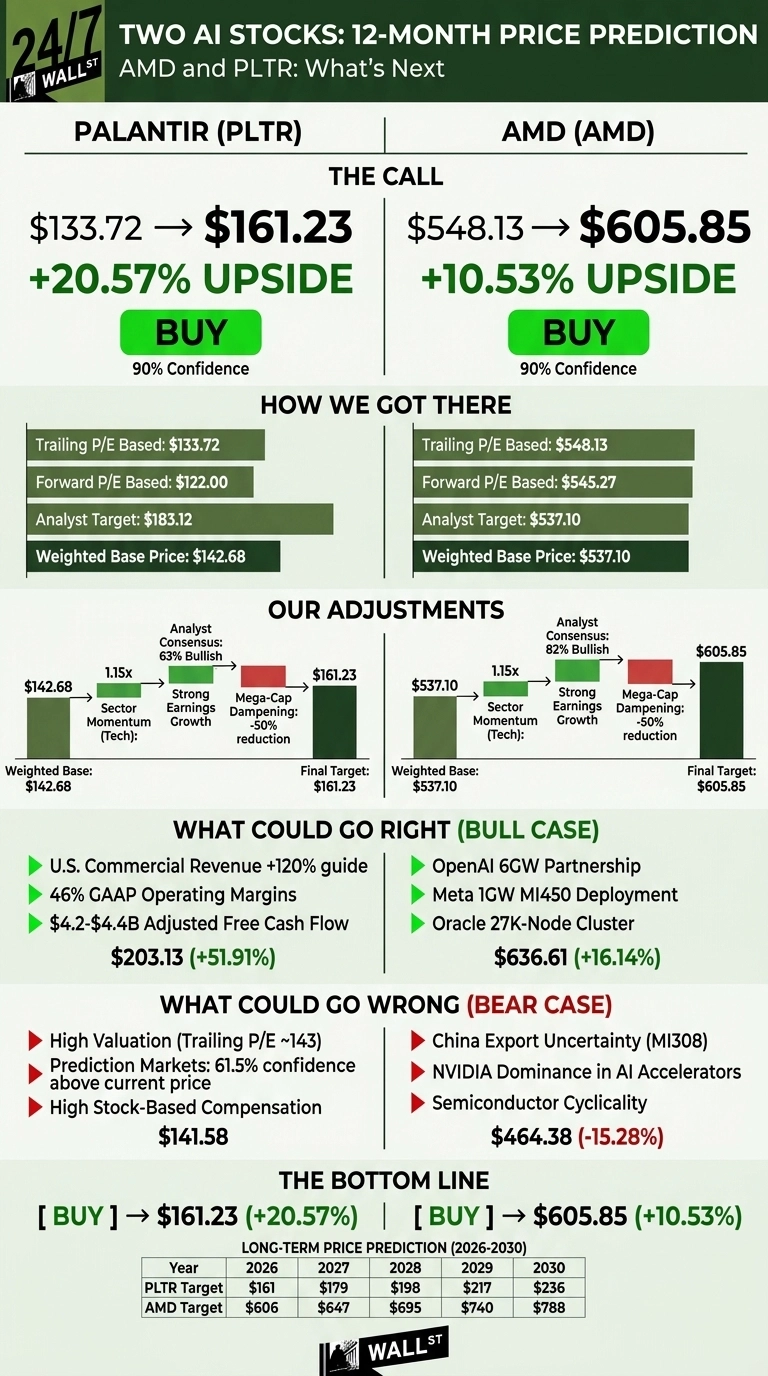
Our proprietary model has a buy on both, but the upside profiles differ meaningfully. Our 24/7 Wall St. price target for PLTR is $161.23, implying 20.57% upside from $133.72. For AMD, the 24/7 Wall St. price target is $605.85, or 10.53% above $548.13. Confidence on both at 90%.
| Metric | PLTR | AMD |
|---|---|---|
| Current Price | $133.72 | $548.13 |
| 24/7 Wall St. Price Target | $161.23 | $605.85 |
| Upside | 20.57% | 10.53% |
| Recommendation | BUY | BUY |
| Confidence | 90% | 90% |
How Palantir and AMD Got Here in 2026
Palantir is down 24.77% year to date and 10.35% over one year, well off its 52-week high of $207.52. Q1 2026 revenue hit $1.63 billion, up 84.7% YoY, with adjusted EPS of $0.33 beating estimates for the eighth straight quarter. CEO Alex Karp raised full-year guidance to 71% growth and touted a Rule of 40 score of 145%.
AMD is the opposite: up 155.94% YTD and 274.82% over one year. Q1 2026 revenue reached $10.25 billion (+37.85%), with Data Center contributing $5.78 billion (+57%). Q2 guidance calls for roughly $11.2 billion.
The Bull Case for Both AI Names
PLTR bulls point to the $3.22 billion U.S. Commercial revenue guide (+120%), 46% GAAP operating margins, and $4.2 to $4.4 billion in projected adjusted free cash flow. Our bull-case one-year target is $203.13, a 51.91% return.

AMD bulls cite hard commitments: OpenAI’s 6GW deployment, Meta’s 1GW MI450 rollout, and Oracle’s 27,000-node cluster. Our AMD bull case reaches $636.61, or 16.14%.

What Could Go Wrong
For Palantir, valuation is the elephant. A trailing P/E near 143 leaves no cushion, and Polymarket traders assign only 61.5% odds to closing above the current level this week. Our bear case sits at $141.58. Bulls counter that high stock-based compensation ($201.6 million in Q1) reflects growth-stage hiring.

AMD’s downside is dominated by China export uncertainty on MI308 and NVIDIA’s grip on the AI accelerator market. Our AMD bear case is $464.38, a 15.28% loss. Wall Street is bullish on the stock. Rosenblatt raised the firm’s price target on AMD to $665 from $490 and keeps a Buy rating on the shares while UBS analyst Timothy Arcuri raised the price target to $700 from $670 and keeps a Buy rating.

How PLTR and AMD Stack Up Against NVIDIA and Snowflake
NVIDIA (NASDAQ:NVDA) is the natural yardstick for AMD. NVIDIA posted Q1 FY27 revenue of $81.6 billion (+85.2%), and trades at a P/E of roughly 43. AMD’s 185 trailing multiple makes our AMD target look aggressive on absolute valuation but reasonable given AMD’s earnings ramp is still early.
Snowflake (NYSE:SNOW) is the closer read on PLTR. Snowflake grew Q1 FY27 revenue 33.5% to $1.39 billion with a 126% net retention rate, yet trades at a market cap under $100 billion versus Palantir’s roughly $311 billion. Palantir’s premium is earned by faster growth and 46% margins, making our $161.23 target appropriate.
Our Verdict on PLTR and AMD


Our 24/7 Wall St. price target model is constructive on both: $161.23 on PLTR (Buy, 90% confidence) and $605.85 on AMD (Buy, 90% confidence).
The PLTR thesis strengthens if U.S. Commercial keeps compounding above 120%. The AMD thesis weakens if MI450 customer forecasts slip or China restrictions tighten.
| Year | PLTR Target | AMD Target |
|---|---|---|
| 2026 | $161 | $606 |
| 2027 | $179 | $647 |
| 2028 | $198 | $695 |
| 2029 | $217 | $740 |
| 2030 | $236 | $788 |
These projections assume both companies execute on current AI-driven growth trajectories. Meaningful upside or downside could come from a China export-control resolution for AMD or sustained triple-digit U.S. Commercial growth at Palantir.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.