After Palantir’s Blowout Earnings, Here’s Where The Stock Could Head Next
Palantir just delivered a software quarter that left analysts scrambling for new benchmarks, yet the stock sits far below its peak and the market seems unmoved. Here is what the numbers actually suggest about where shares go from here.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Palantir (NASDAQ: PLTR | PLTR Price Prediction) just delivered one of the most staggering software quarters I have ever covered, and the market’s reaction has been oddly muted. Palantir posted $1.94 billion in Q2 2026 revenue, up 92.83% year over year, yet the stock trades down 29.31% year to date. That gap between fundamentals and price is exactly what our model is trying to price in.
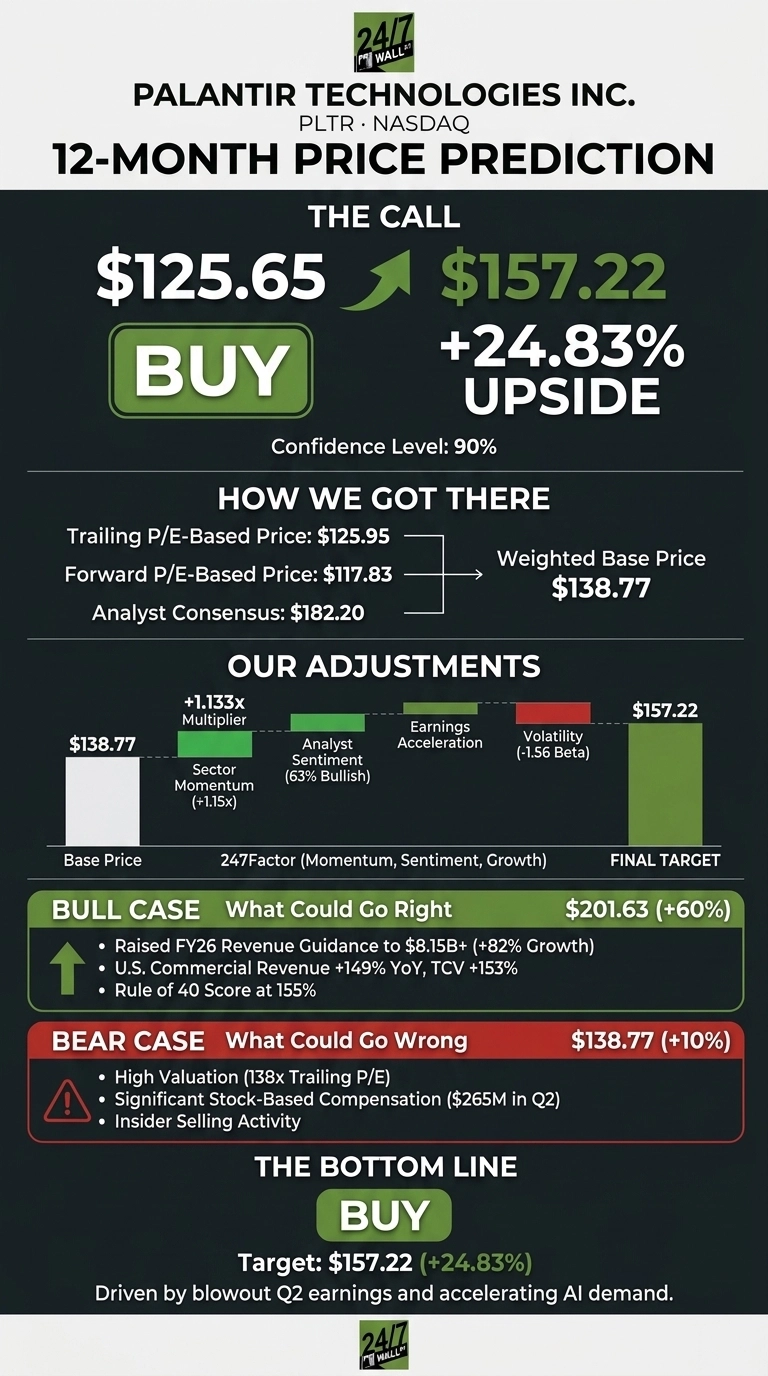
Our 24/7 Wall St. price target for Palantir is $157.22, implying 24.83% upside from the current $125.65 quote, with the recommendation set to buy.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $125.65 |
| 24/7 Wall St. Price Target | $157.22 |
| Upside | 24.83% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Blowout Quarter the Market Has Not Digested
Palantir sits 12% below its 52-week high of $207.52 and just above its 52-week low of $106.37. Shares are down 4.47% over the past week and off 18.55% over one year, even after climbing 2.1% on August 3.
Q2 EPS of $0.41 beat the $0.346 estimate by 46.43%, extending the streak to nine consecutive beats. U.S. commercial revenue jumped 149% to $764 million, and the Rule of 40 score reached 155%, an almost unheard-of figure at this scale.
Why Bulls See a Breakout to $201
Our bull case pegs Palantir at $201.63 within 12 months, a 60.08% return. The driver is simple: management raised FY2026 revenue guidance to $8.150 to $8.158 billion, or 82% growth, with adjusted free cash flow between $4.5 and $4.7 billion. CEO Alex Karp told investors “demand for AI sovereignty has now been unleashed”, and the numbers back him.
U.S. commercial remaining deal value hit $6.238 billion, up 124%, meaning growth is booked, not hoped for. If AIP adoption compounds, the analyst consensus target of $182.20 becomes a floor rather than a ceiling.
What Could Go Wrong
Our bear case lands at $138.77. Palantir trades at a trailing P/E of 138 and a forward P/E of 84, leaving zero margin for a stumble. Stock-based compensation ran $265 million in Q2, and insider activity shows net selling across 70 recent transactions.
Bulls would counter that SBC is the cost of retaining engineers building a category-defining platform, and that $1.22 billion in Q2 free cash flow more than absorbs it. Termination-for-convenience clauses in government contracts remain a structural risk worth respecting.
How Palantir Compares to Snowflake and Salesforce
Snowflake (NYSE: SNOW) is the closest AI-data-platform comparable. Snowflake posted Q1 FY27 revenue of $1.39 billion, up 33.5%, a fraction of Palantir’s 93% pace, yet still runs GAAP operating losses. Palantir’s 47% GAAP operating margin is the differentiator, and it makes our target look reasonable rather than aggressive.
Salesforce (NYSE: CRM) offers the value counterpoint. Salesforce trades at a P/E near 20 with 13.3% revenue growth. Palantir grows roughly 7x faster and carries net cash. The premium is earned, though it demands sustained execution.
| Company | Revenue Growth YoY | Forward P/E |
|---|---|---|
| Palantir | 92.83% | 84 |
| Snowflake | 33.5% | N/A (losses) |
| Salesforce | 13.3% | 20 |
Where the Setup Stands
The 24/7 Wall St. price target of $157.22 with 90% confidence and a buy rating reflects a business firing at a Rule of 40 score of 155% while trading well below its 52-week high.
The bullish thesis strengthens if U.S. commercial bookings maintain triple-digit growth through Q3. It weakens if government contract cancellations accelerate or if operating margins compress below 40%. The setup favors the bull case.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $157 |
| 2027 | $185 |
| 2028 | $205 |
| 2029 | $225 |
| 2030 | $242 |
These projections assume Palantir continues converting AIP demand into booked revenue. Meaningful upside or downside could result from federal AI budget shifts or a broader software multiple reset.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.