The $5 Trillion Question: Does Apple or Nvidia Maintain The Highest Market Cap?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
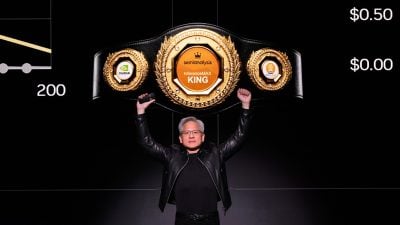
Apple (NASDAQ: AAPL | AAPL Price Prediction) sits at $4.89 trillion, just behind NVIDIA (NASDAQ: NVDA) at $5.01 trillion. Both just reported blockbuster quarters. Apple reports again on July 30, and Nvidia follows on August 26. The $5 trillion crown is genuinely in play.
iPhone 17 Fuels Apple. AI Factories Fuel Nvidia.
Apple’s Q2 FY26 delivered $111.18B in revenue, up 16.6% year over year, with iPhone alone contributing $56.99B on what Tim Cook called “extraordinary demand for the iPhone 17 lineup.” Services hit an all-time record of $30.98B, and every geographic segment grew double digits. That is a diversified machine humming on brand power.
Nvidia’s Q1 FY27 was a different beast entirely. Revenue jumped 85.2% to $81.61B, with Data Center revenue reaching $75.25B and networking tripling year over year. Jensen Huang described the moment plainly: “The buildout of AI factories, the largest infrastructure expansion in human history, is accelerating at extraordinary speed.”
Consumer Cash Machine vs. AI Infrastructure Monopoly
| Lens | Apple | Nvidia |
| Gross Margin | 46.9% | 71.1% |
| Revenue Growth | +16.6% | +85.2% |
| Core Bet | iPhone plus Services | Blackwell, Rubin, networking |
| China Exposure | $20.50B (growing) | Effectively zero Data Center compute |
Apple’s capital efficiency is the quiet story. A viral r/stocks post flagged Apple’s capex at just 1.8% of revenue versus Alphabet’s 37.5%, framing Cupertino as the anti-AI-capex trade. Nvidia sits on the opposite side: it is the vendor collecting checks from that spending, backed by $119B in supply commitments.
The Next 30 Days Decide the Crown
Apple’s July 30 report is the immediate catalyst. Hardware margin guidance of 47.5% to 48.5% faces pressure from rising DRAM costs. Hold that line, and Apple could become the first company to close above $5 trillion. Polymarket traders assign 89.5% probability to iPhone revenue above $52B and 82% to Greater China above $18B. Nvidia’s August 26 answer matters just as much. Consensus expects $393B in FY27 revenue. Any reassurance on Blackwell 300 and Rubin uptake, plus hyperscaler capex language, could flip the leaderboard within a session.
Why I Give Nvidia the Edge on Growth, but Apple the Edge on Certainty
For research purposes, Apple offers the profile of a durable compounder with a $100B buyback and a proven 8-quarter beat streak, though the margin question looms larger than the demand question. Nvidia offers raw growth with more volatility, backed by a 75% gross margin and a tripling networking business. The AI capex cycle has not peaked, which favors Nvidia’s growth setup over the next 12 months, while Apple’s Wednesday report will test the margin thesis. I hold both positions into this week. This title fight is genuinely two rounds away from a decision.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.