One Massive AI Hardware Truth Keeps Me Loading Up On AMAT Ahead of Aug. 13 Earnings Print
Everyone racing to own AI chip stocks may be buying into the wrong part of the supply chain. The real toll booth sits one step behind the GPUs, and one company collects on every wafer that makes next-gen AI hardware…

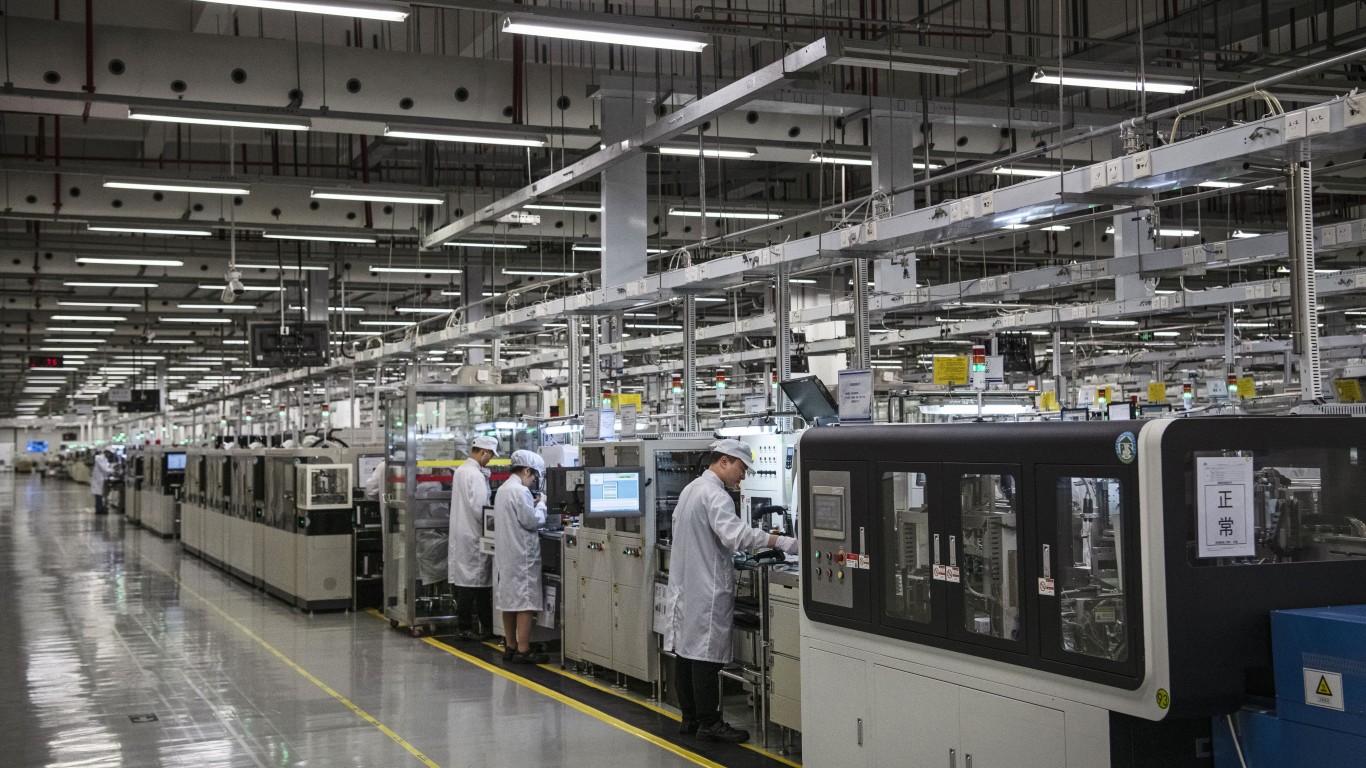
I keep hitting the buy button on Applied Materials (NASDAQ:AMAT | AMAT Price Prediction) because one truth about the AI build-out has become impossible to ignore: NVIDIA (NASDAQ:NVDA), Advanced Micro Devices (NASDAQ:AMD), and custom ASIC designers cannot ship a single next-gen AI chip without advanced wafer fab packaging, and Applied sells the etch, deposition, and CMP tools that make Through-Silicon Vias and Chip-on-Wafer-on-Substrate stacking possible in the first place.
That is the core of my conviction. Everyone talks GPUs. I own the toll booth behind the GPUs. CEO Gary Dickerson framed it plainly on the last call: “The rapid global build-out of AI computing infrastructure” is driving Applied’s positions in leading-edge foundry logic, DRAM, and advanced packaging, and the company now expects its semiconductor equipment business to grow more than 30% this calendar year. Packaging revenue alone is guided to grow more than 50% in calendar 2026.
The Receipts Behind the Buy
Q2 FY2026 delivered record revenue of $7.91 billion, non-GAAP EPS of $2.86, and a non-GAAP gross margin of 50%, the highest in more than 25 years. Applied Global Services, the recurring high-margin base I care most about for a retirement account, ran at $1.67 billion in the quarter, with more than 35,000 chambers connected to Applied’s proprietary AIx software.
Then there is the shareholder return story. The board raised the quarterly dividend 15% in March, extending a nine-consecutive-year streak of increases, with FY2025 buybacks of $4.895 billion against $5.698 billion in free cash flow. Analyst consensus sits at 32 Buy or Strong Buy ratings versus 7 Hold and zero Sell, with a target of $629.09.
Why Not Lam Research?
I respect Lam Research (NASDAQ:LRCX). It is putting up 30% YoY revenue growth and a 37.4% operating margin. My money still lands on AMAT because forward valuations are nearly identical, with Applied at a forward P/E of 32 versus Lam at 32, while Applied’s quarterly dividend of $0.53 runs double Lam’s $0.26. AMAT trades at a price-to-book of 17 versus Lam’s 29, and Applied’s services segment at that scale is a recurring cash engine Lam does not match at the same volume.
The Risk I Am Taking Seriously
China is the real one. It was 27% of Q2 FY26 revenue, or $2.087 billion, down from 35% a year earlier, and Applied paid a $253 million settlement with the U.S. Commerce Department’s BIS in Q1 FY2026 tied to export controls. The mix keeps shrinking as leading-edge logic and HBM demand in Taiwan, Korea, and the U.S. takes a larger share of the pie, which is exactly the direction the moat needs to travel.
Why the Buy Button Stays Active
Dickerson said a customer he met with was “worried about the supply all the way into 2030”. That is the demand curve I am underwriting. Ahead of the August 13 report guided to $8.95 billion in revenue and $3.36 in EPS, with prediction markets pricing a 92.5% chance of a beat, I keep adding because Applied sells the tools that decide whether the next decade of AI hardware ships at all.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.