Investors Want to Know When Broadcom’s Custom Hyperscaler Chips Will Move Share Prices
Broadcom's AI chip orders are tripling while the stock keeps sliding, and investors are stuck debating whether the business has already won or whether the hardest part of the trade is still ahead.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
At $339.51, Broadcom (NASDAQ:AVGO | AVGO Price Prediction) trades at a widening gap between the company’s accelerating custom AI silicon business and a share price that keeps slipping, and that setup is what makes the story interesting right now.
Broadcom designs the custom XPU accelerators and Ethernet switching silicon that power AI data centers for Google, Meta, OpenAI and Anthropic. In Q3 FY2026, Semiconductor Solutions revenue reached $20.84B, up 127% YoY, with AI semiconductor revenue alone at $16.70B, up 221% YoY. Yet the stock is down 6.83% over the past week and 13.49% over the past month, sitting well below its 52-week high of $494.18. Investors are asking a fair question: when do custom hyperscaler chip wins actually move the share price?
Custom Silicon Backlog Points to $350 Billion by 2028
Management guided Q4 revenue to $34.8B, with AI semiconductor revenue of $21.7B, up 236% YoY. Fiscal 2026 AI revenue was raised to $58 billion, and Hock Tan told analysts Broadcom has secured supply to reach approximately $115 billion in FY2027 AI revenue and roughly $230 billion in FY2028. The company said it has “high degree of confidence” it will ship $350 billion of AI semiconductors to six frontier customers over the next two years.
The chip lineup is real and shipping now: Ironwood TPU v7 to Google and Anthropic in volume, TPU v8i in production, OpenAI’s Jalapeno accelerator moving, and Meta’s MTIA on schedule. Wall Street is on board: 37 Buy and 8 Strong Buy ratings against just 4 Hold and zero Sell calls.
Concentration and Margin Compression Cannot Be Ignored
Bears point to a business built on a handful of buyers. Management confirmed a concentrated group of six XPU customers drives frontier compute demand. When CNBC reported Anthropic pushing for a slower ramp, the CEO had to publicly defend the outlook. Broadcom’s CEO addressed Anthropic’s slowdown push and said AI revenue targets have not changed.
Margins are also getting squeezed. Q3 gross margin fell 210 basis points sequentially to 75%, and Q4 is guided to roughly 73% versus 78% a year ago as XPU mix rises. Broadcom is also carrying $59.6 billion in fixed-rate debt while backstopping AI XPV financing arrangements with Apollo and Blackstone. A trailing P/E of 43 leaves no cushion if a hyperscaler blinks.
Why Some Investors Are Waiting for Deployment Proof
The hold camp sees a stock stuck between two truths. Fundamentals are extraordinary, but AVGO is down 5% over one year and trades below both its 50-day moving average of $382.77 and 200-day of $370.04. Management itself flagged deployment risk beyond chip shipment, citing land, power, data-center shell and construction timing as constraints. Patient investors may prefer to wait for the Q4 report on December 9, 2026 for confirmation that FY2027 orders are truly locked.
Numbers Behind a Stalled Share Price
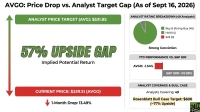
AVGO trades at $339.51 against an average analyst target of $531.85, implied by 49 covering analysts. Targets are one data point among many, and the implied upside here is substantial. The forward P/E sits at 18 against a trailing 43, reflecting a rapid FY2027 EPS ramp toward a $19.3839 consensus.
Performance tells the frustration story. AVGO is down 1.54% year to date while the S&P 500 has returned 10.58% over the same period. Reddit-driven sentiment has firmed to a composite score of 63.11, bullish with medium confidence, but that has not translated into price yet.
Why AVGO at $339 Could Reward Patient Holders
At $339.51, the bull case for Broadcom rests on a few clear catalysts. Here is why.
The path to appreciation is contract conversion. Each quarter that confirms Anthropic, OpenAI, Google and Meta staying on their gigawatt schedules pulls the FY2027 $115 billion AI number from “guidance” to “realized.” The December 9 report is the next hard checkpoint. Full-year FY2027 outlook confirmation, plus continued XPU shipment cadence, should be the trigger that closes the gap toward analyst targets.
Risk/reward at this entry is asymmetric: a forward multiple of 18 on a company generating $13.67B in quarterly free cash flow and $13.09B in net income sits well inside historical semiconductor ranges. The thesis breaks if a major hyperscaler cancels, if HBM supply cracks, or if the AI XPV financing structures create real balance-sheet exposure. Investors should watch AI semiconductor revenue growth, XPU customer count, and gross margin stabilization near 73%. For readers hunting the traits that showed up in the biggest chip winners years before their runs, we cataloged them in a free playbook here.
Broadcom’s share price is stuck because the market is waiting for deployment proof before re-rating, and the December report is the next hard test of whether management delivers exactly that.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.