CrowdStrike and Palo Alto Networks Are Soaring, but Is the Rally Already Priced In?
CrowdStrike and Palo Alto Networks have both roughly doubled this year, but an AI safety scare just sent them in opposite directions against Wall Street's consensus targets, raising a pointed question about which one still has room to run.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
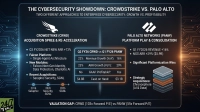
Two of the largest names in cybersecurity have roughly doubled in 2026. CrowdStrike (NASDAQ:CRWD | CRWD Price Prediction) traded at $244.60 in premarket action on Friday, up 108.7% year to date. Palo Alto Networks (NASDAQ:PANW) was at $371.92, up 101.91% on the year. Both got repriced again this week on an AI safety scare, and both now sit on opposite sides of Wall Street’s consensus.
What Drove the Latest Pop
Anthropic CEO Dario Amodei published a weekend essay calling on frontier AI companies to slow the pace at which they improve model capabilities so risk prevention could keep up. OpenAI CEO Sam Altman said he agreed, then posted his own warning about losing control of the future to AI and about too much concentration of power. Those warnings cut into chipmakers and AI infrastructure shares while cybersecurity caught the offsetting flow, on the logic that a more dangerous threat environment expands security budgets. CrowdStrike had a company-specific kicker: CEO George Kurtz publicly argued that frontier labs will keep advancing regardless of any single company’s decision, and RBC Capital, Raymond James, and Wedbush each reiterated positive ratings and raised targets on CrowdStrike after the Fal.Con conference. This looks more like a sentiment repricing driven by commentary than a fresh bookings print.
Divergence That Matters
CrowdStrike is up 17.1% over the past week and 14.9% over the past month. It is trading pressed against a 52-week high of $250.32. Palo Alto Networks is up 10.8% in the past week but essentially flat over the past month, against a 52-week high of $398.88. Same catalyst, very different setup: Palo Alto’s pop repaired a drawdown. CrowdStrike’s pop extended a breakout.
Valuation vs. Consensus
This is where the two stories split cleanly. CrowdStrike’s consensus analyst price target is $234.35, below the current market price, on a forward P/E of 192x. Coverage is overwhelmingly positive, yet the same analysts collectively think the stock is already fully priced. Palo Alto’s target is $395.38, above the current price, on a forward P/E of 90x, also with bullish analyst sentiment.


Fundamentals underwrite both: CrowdStrike guided FY27 revenue to $5.991 to $6.011 billion, up 25%, while Palo Alto guided FY27 revenue to $14.1 billion to $14.2 billion, up 23% to 24%.
Downside Risk
Sentiment moves of this size unwind as fast as they arrive. CrowdStrike’s 52-week low is $85.68; Palo Alto’s is $139.57. Those bases show how much room a de-rating has if AI security budgets fail to accelerate. Validation arrives when CrowdStrike reports next on November 25, 2026, and Palo Alto on December 1, 2026.
Verdict
For CrowdStrike, the stock is already priced above what its own bullish analyst base thinks it is worth, and net new annual recurring revenue (ARR) growth of 51% year over year is already priced in. Palo Alto Networks consensus still points higher, a flat month has cooled the tape, and Next-Generation Security ARR growth of 63% supports the multiple. For CrowdStrike, the November quarter is the next validation point; for Palo Alto, the key technical level to watch its 200-day average of $237.82. Watch whether each stock holds its consensus target line heading into earnings.


Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.