The SMCI Number I’m Watching Could Decide Where the Stock Goes Next
Super Micro Computer has beaten earnings three of the last four quarters, its backlog just hit a record, and one specific valuation metric now sits at a level that historically precedes a major repricing. Here is what has to happen…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
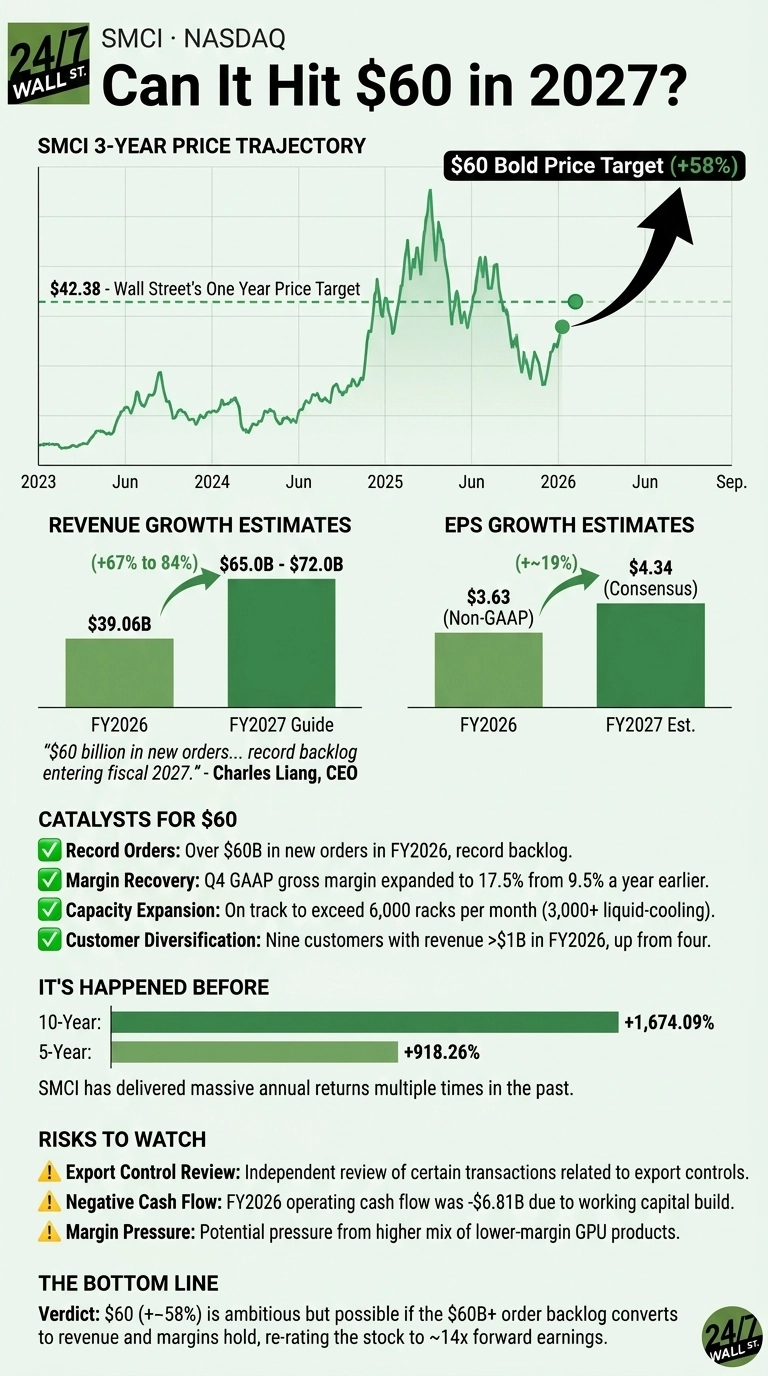
Super Micro Computer (NASDAQ: SMCI | SMCI Price Prediction) is on the mend in 2026. Shares are up 29.59% year to date, even after slipping 15.54% over the last twelve months. The rebound follows a fiscal 2026 in which the AI server maker posted revenue of $39.06B, up 77.79% year over year, and non-GAAP EPS of $3.63, beating the $2.84 consensus by 27.96%.
CEO Charles Liang told investors the company generated “over $60 billion in new orders” during Q4 and booked record backlog entering fiscal 2027. Here is what it would take for SMCI to hit $60 per share in 2027.

Wall Street Sees Modest Upside, But Estimates Are Ripping Higher
The Street’s average price target sits at $42.38, with a ratings split of 2 strong buys, 3 buys, 11 holds, 2 sells, and 1 strong sell. That looks cautious. What matters more is the direction of estimates.
The FY2027 EPS consensus has climbed to $4.34, up from $3.35 thirty days ago and $3.27 ninety days ago, with 16 upward revisions and zero downward revisions in the last 30 days. FY2028 EPS has jumped to $5.33 from $3.86 a month ago. When numbers move this fast, price targets typically follow.

Path to $60 Per Share
At today’s $37.93, SMCI trades at roughly 9x forward earnings. If shares reach $60, they would trade near 14x the FY2027 consensus of $4.34. That is still a discount to the S&P 500’s forward multiple around 22x, and far below what most AI infrastructure names command.

What could push SMCI to $60?
- Backlog conversion. Liang cited $60 billion in new orders and management guided full-year FY2027 revenue to $65B to $72B, implying 67% to 84% growth.
- Margin recovery. Q4 GAAP gross margin expanded to 17.5% from 9.5% a year earlier, driven by a richer enterprise mix and the DCBBS architecture Liang called “our long-term much better profit margin product line.”
- Beat streak. SMCI has beaten EPS in three of the last four quarters, including a 77.55% surprise in Q4.
- Customer diversification. The company had nine customers over $1 billion in fiscal 2026, up from four in fiscal 2025.
- Capacity. Total manufacturing is on track to exceed 6,000 racks per month, including more than 3,000 direct-liquid-cooling racks per month.
SMCI’s History Says $60 Isn’t Out of Reach
Getting from $37.93 to $60 requires a gain of roughly 58%. That is a big move, but SMCI regularly delivers bigger. Shares are up 918.26% over five years and 1,674.09% over ten. The stock has a beta of 1.996 and a 52-week range of $19.48 to $58.78.
Volatility cuts both ways, but at 9x forward EPS with earnings accelerating, the setup favors upside. SMCI is one of the clearest non-chipmaker plays on the AI data-center buildout, and we profiled seven more suppliers powering that same wave in a free report you can grab here.
Bottom Line on $60
Reaching $60 in 2027 would take roughly 58% appreciation from here. The hurdles are real: the board is still working through an independent review of certain transactions related to export-control issues, and FY2026 operating cash flow was negative $6.81B on a working capital build.
But if Liang converts even the low end of the $65B to $72B revenue guide, gross margin holds near Q4’s 17.5% print, and the estimate-revision cycle keeps running, a re-rating to 14x forward earnings is well within reach. Returns at this level should not be expected every year, but we’ve outlined the blueprint for how SMCI could deliver outsized gains in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.