Prediction: SMCI Stock Will Trade At This Price In 2027
Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction) just printed $10.24 billion in Q3 FY2026 revenue, up 122.68% year over year, while CEO Charles Liang declared that “Supermicro’s transformation into a total datacenter infrastructure provider is accelerating.” Shares are up…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction) just printed $10.24 billion in Q3 FY2026 revenue, up 122.68% year over year, while CEO Charles Liang declared that “Supermicro’s transformation into a total datacenter infrastructure provider is accelerating.”
Shares are up 41.1% year to date, yet still sit miles below last cycle’s highs. Can SMCI reach $60 per share in 2027?
Why SMCI Shares Are Stuck Below Their Old Highs
The recent ramp is real, but the year-long picture is messier. SMCI is down 1.57% over the trailing twelve months and sits 40% below its 52-week high of $62.36. The overhang is governance.
Results remain preliminary and unaudited as the Board conducts an independent review of export-control matters. Margins have been the other wound. GAAP gross margin compressed to 6.3% in Q2 FY2026 from 11.8% a year earlier before clawing back to 9.9% in Q3.
Add $8.8 billion in total debt and convertibles and a beta of 1.684, and you have a stock that punishes any whiff of bad news. The one-week move of 23.43% shows the volatility cuts both ways.
Wall Street Is Cautious. Too Cautious.
The Street consensus is uninspired. The average analyst target sits at $37.12, with a rating split of 2 Strong Buys, 3 Buys, 9 Holds, 2 Sells, and 2 Strong Sells. Only 28% of analysts are bullish.
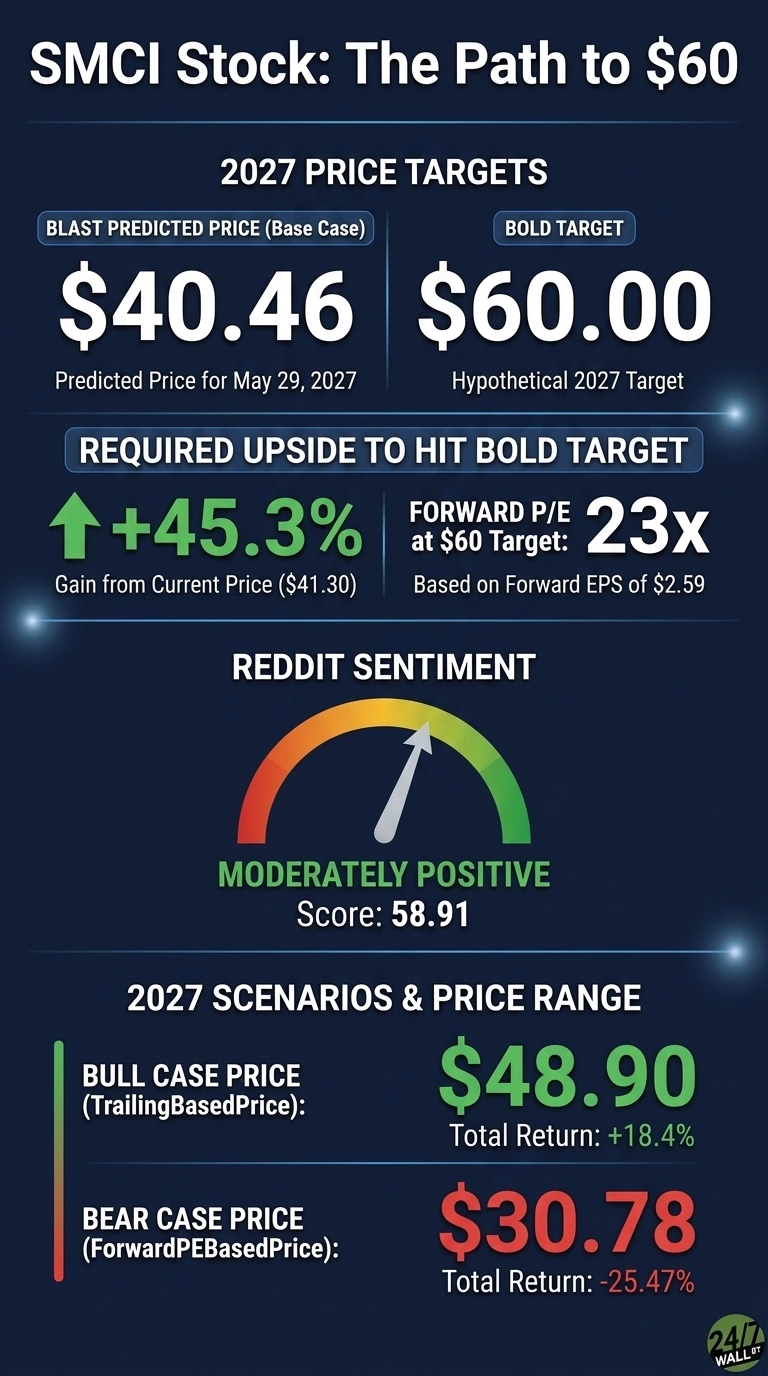
Our internal base case puts 2027 fair value at $40.46, with an optimistic scenario at $48.90 and a bear case of $30.78, all carried at a 90% confidence.
Here’s my pushback. Full FY2026 guidance was raised to $38.90 to $40.40 billion, nearly double FY2025’s $21.97 billion. Analysts are anchored to the margin scare. If the audit clears and DCBBS scales, the consensus target looks stale by Q1 2027.
The Path to $60 Per Share
Reaching $60 from today’s price of $41.30 would require a gain of 45.3%. With forward EPS of $2.59, a price of $60 implies a forward P/E of 23x. Our base case of $40.46 already implies 18x, meaning the bold target needs roughly 5x of additional multiple expansion.
That is achievable if the EPS denominator keeps moving up. Q3 FY2026 non-GAAP EPS beat consensus by 34.51% and Q2 FY2026 beat by 41.42%.
Liang has pointed to “more than $13B in Blackwell Ultra orders” and said Supermicro is “exceptionally well-positioned to meet the massive demand for various AI and enterprise verticals” as new Silicon Valley manufacturing comes online.
If margins normalize toward FY2025’s 11.1% GAAP gross margin average, the forward multiple compresses as EPS grows into the price. The risk: the export-control review delivers a worse outcome than expected.
The Valuation Case for SMCI Right Now
SMCI trades at a current forward P/E of roughly 16x, well below the trailing 20x and a PEG ratio of 0.913. Shares sit between the 52-week low of $19.48 and high of $62.36. Long-term holders have been rewarded: SMCI is up 1,485.41% over the past decade. A sub-PEG, sub-20 multiple on a business compounding revenue triple digits is the entire bull case in one sentence.
$60 Is a Stretch, But Here’s Why It’s Possible
To hit $60 in 2027, SMCI needs a 45.3% gain from here. It is a stretch, but not a long shot.
Three things need to go right. The export-control review must close cleanly. Gross margins need to keep recovering toward double digits. And Blackwell Ultra shipments have to convert the $13B+ order book into reported revenue without further inventory write-downs.
What would derail it: another quarter of margin compression that resets the EPS curve lower. We’ve outlined the blueprint for how Super Micro Computer could reach $60 in 2027.

Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.