Prediction: The Cheapest Mega Cap in the AI Trade, Alphabet Could Hit $600 in 2027
Alphabet just posted numbers that should have sent the stock soaring, yet something is keeping a lid on it. Here is why the cheapest mega-cap in the AI trade might still have the most room to run.

Google (NASDAQ:GOOG | GOOG Price Prediction | GOOG Price Prediction) just posted the most striking quarter of any mega-cap AI beneficiary. Cloud grew 82% to $24.8 billion, backlog reached $514 billion, and CEO Sundar Pichai said Alphabet is in the “very early innings” of a secular AI shift.
Yet the stock trades at a 17x trailing P/E, the cheapest multiple in the mega-cap AI cohort. Shares sit at $352.20, up 12.46% YTD. Can this stock reach $600 by 2027? Here is the math.

What Is Really Holding Alphabet Back
The stock is stuck because of what fundamentals are costing. Q2 free cash flow swung to negative $5.855 billion as CapEx doubled to $44.92 billion. Long-term debt jumped from $46.5 billion to $98.2 billion, the buyback was suspended in Q2 2026, and management projected FY26 CapEx of $175 billion to $185 billion.
Investors are underwriting the biggest infrastructure build in corporate history (the power, cooling, and networking suppliers riding that same wave are the subject of a free report on seven AI infrastructure names that aren’t chipmakers).
That anxiety shows in the stock. Shares are up 3.14% over the past month and 4.99% over the past week, despite a 39.95% one-year gain. With a beta of 1.225, GOOG moves harder than the market when sentiment on AI capex shifts.
Wall Street Sees 20% Upside. My Model Sees 51%
The Street consensus target is $422.34, drawn from 13 strong-buy, 43 buy, and 5 hold ratings with zero sells. Bullish share sits at 92%. My base case is more aggressive: a $519.98 predicted price, or 50.98% upside, with a bull scenario of $586.04 and a bear case still at $427.72. Confidence: 0.9, high.

The Street is underweighting two things. First, the FY26 EPS estimate has moved from $14.23 ninety days ago to $20.60. Second, earnings growth contribution to my model is only 0.03.
Path to $600 Per Share
Reaching $600 from $352.20 requires a 70.4% gain.
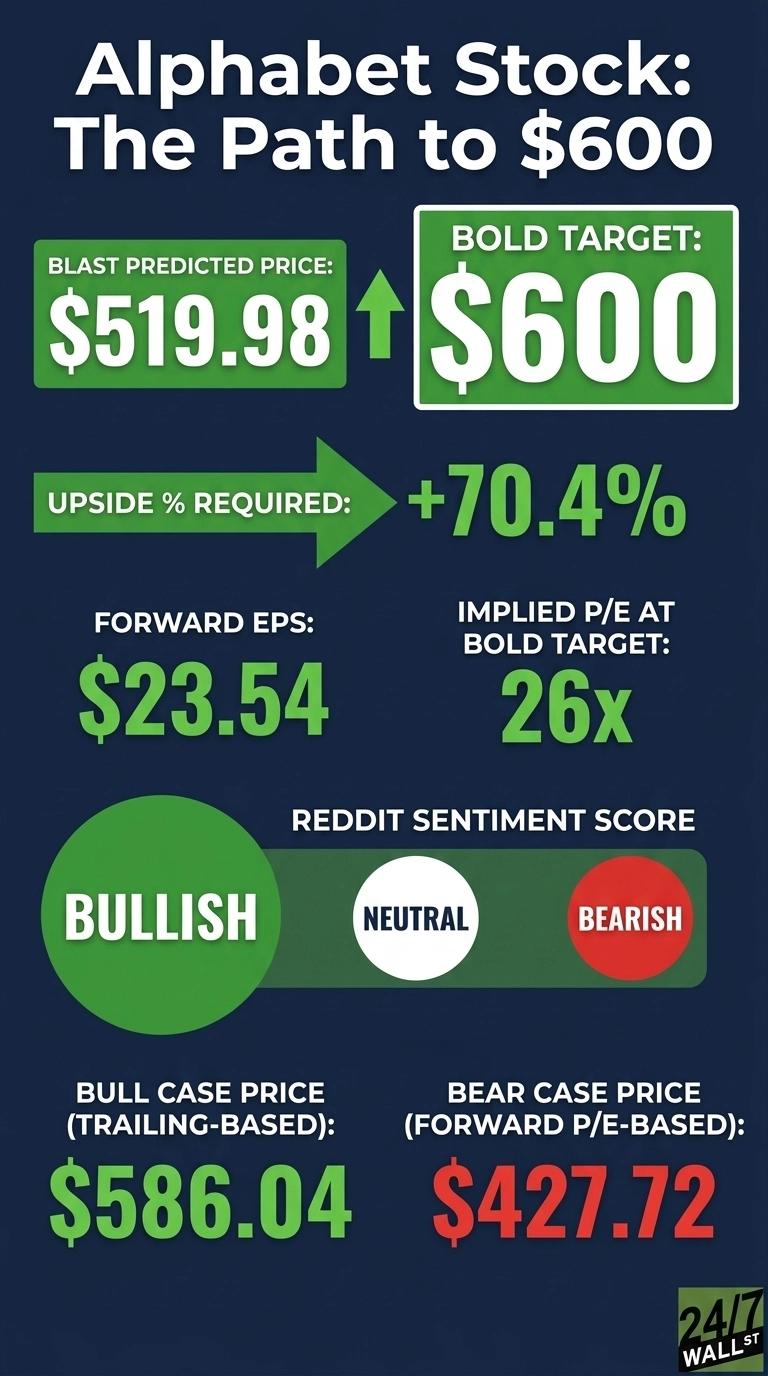
With forward EPS of $23.54, a price of $600 implies a forward P/E of 26x. My base case of $519.98 already implies 17x, meaning $600 requires roughly 8x of additional multiple expansion.

Cloud is compounding at 82% with 35.6% operating margins. Gemini processes 22 billion API tokens per minute and the Gemini App has 950 million monthly active users.
Pichai said “Our AI investments are redefining what’s possible across every part of our business.” As TPU system sales revenue arrives in 2027, EPS should reprice higher, letting the multiple expand without looking rich.
The primary risk: sustained negative free cash flow forces investors to discount the CapEx cycle harder than the market currently does.
Where Alphabet Trades Today Vs Its Earnings Power
At $352.20 against forward EPS of $23.54, GOOG trades at roughly 15x forward earnings. That is a discount to every mega-cap AI peer despite delivering an EPS surprise of 199.41% last quarter.
Shares sit between a 52-week low of $236.07 and high of $403.96, and have returned 821.83% over the past decade. Cheap growth compounding at scale is a rare setup.
Is $600 Realistic? My Verdict
Reaching $600 requires a 70.4% gain and a forward multiple of 26x. That is a stretch but achievable.
Three things need to go right: Cloud growth stays above 50%, the $514 billion backlog converts on schedule, and TPU system sales ramp meaningfully in 2027. A sharp deterioration in ad monetization from AI-answer cannibalization would derail it. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Google could reach $600 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.