Alphabet Has 50% Upside and the Cheapest Multiple of the Big Six
Alphabet trades at a multiple that would make sense for a company with no growth story, yet its Cloud backlog just hit half a trillion dollars. Something in that math is badly mispriced, and the window may not stay open…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Our Alphabet (NASDAQ:GOOG | GOOG Price Prediction) call is direct: shares are the cheapest in the Big Six and the setup into 2027 is unusually asymmetric.
With Google Cloud growing 82% year over year and a trailing P/E of just 17, the market is pricing Alphabet like a mature ad business while it operates like a hyperscaler. Our 24/7 Wall St. price target for Alphabet is $504.76, implying 50.47% upside from $341.33. Our confidence is high.
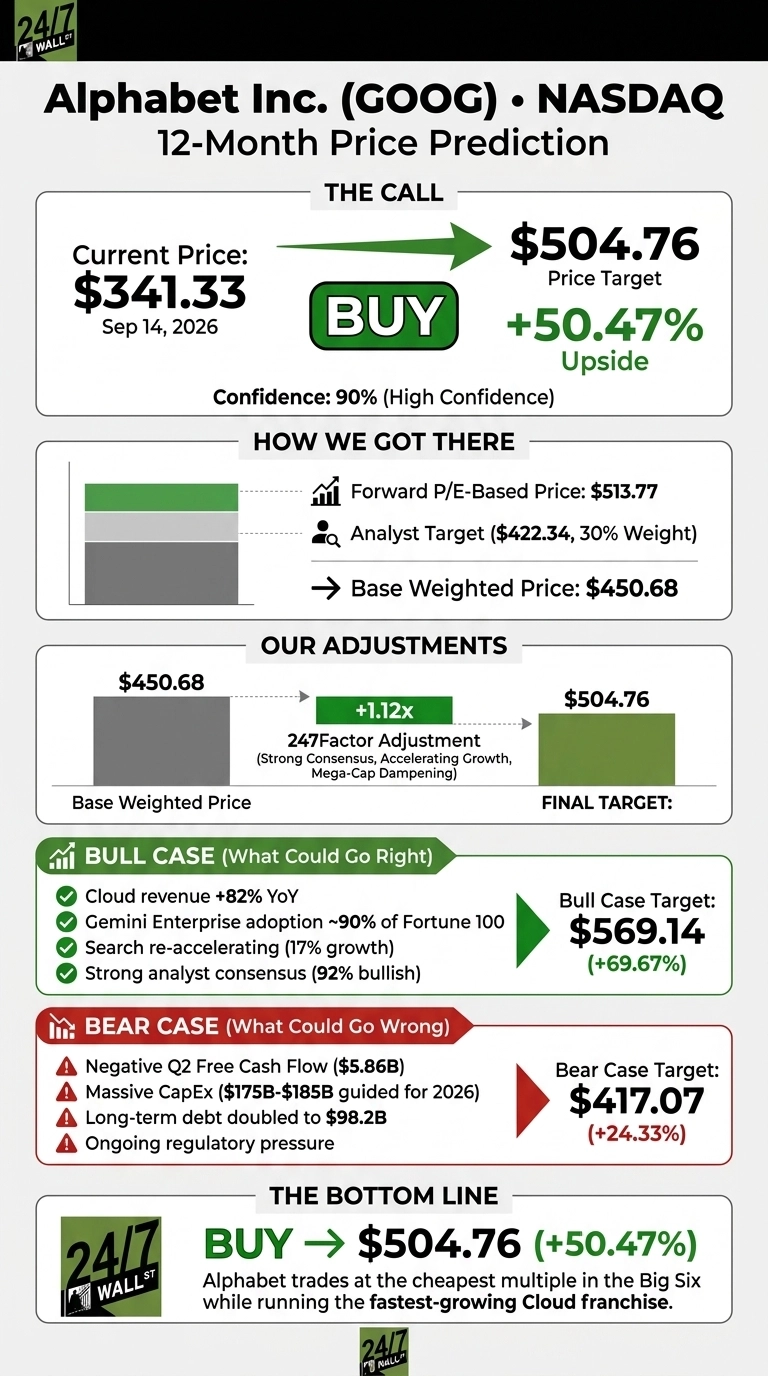
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $341.33 |
| 24/7 Wall St. Price Target | $504.76 |
| Upside | 50.47% |
| Recommendation | BUY |
| Confidence Level | 90% |

What Just Happened: A Blowout Quarter and a New AI Trade
Alphabet is up 42.13% over the past year and 8.99% year to date, with today’s move adding another 1.75% as investors rotated back into mega-cap AI beneficiaries on fresh capacity concerns across the sector (Barron’s, Sept. 14, 2026).
Q2 2026 delivered EPS of $9.11 versus $3.04 expected on revenue of $119.80 billion, up 24.2%. Search grew 17%, YouTube ads 13%, and Cloud accelerated to 82% with backlog swelling to $514 billion.

Why Bulls See a Breakout Ahead
The bull case starts with Cloud. Backlog of $514 billion is now roughly 50 billion higher sequentially, and management expects to recognize just over 50% as revenue within 24 months.
Gemini is entrenched: nearly 90% of Fortune 100 companies use Gemini Enterprise, and the Gemini app hit 950 million MAUs. Our bull scenario points to $569.14 within twelve months, a 69.67% return.
What Could Go Wrong
Alphabet burned negative $5.86 billion in Q2 free cash flow as CapEx hit $44.92 billion. Management guided 2026 CapEx to $175 billion to $185 billion, long-term debt more than doubled to $98.2 billion, and buybacks were suspended.
Bulls would counter that trailing-twelve-month operating cash flow of $185.7 billion comfortably funds this build, and management frames third-party capacity costs as ROI-positive over multiyear contracts. Our bear scenario still lands at $417.07, a positive 24.33% return.

Is Alphabet Cheaper Than Microsoft and Meta?
Microsoft (NASDAQ:MSFT) is the direct hyperscaler comp. Microsoft trades at a trailing P/E of 28 and forward P/E of 25, with quarterly revenue growth of 17.7%. Alphabet is growing faster (24.2%) at a multiple roughly 40% cheaper on a trailing basis.
Meta Platforms (NASDAQ:META) is the ad-market comp. Meta trades at a trailing P/E of 24 with quarterly earnings growth of -13.4%. Alphabet’s ROE of 35.7% tops Meta’s 29.8%. Across both comps, our $504.76 target looks conservative given the growth premium GOOG deserves.
| Company | Trailing P/E | Quarterly Revenue Growth |
|---|---|---|
| Alphabet | 17 | 24.2% |
| Microsoft | 28 | 17.7% |
| Meta | 24 | 28% |
Alphabet Price Prediction 2026-2030
Our 24/7 Wall St. price target of $504.76 implies a buy with 90% confidence. The tipping factor is simple: Alphabet trades at the lowest trailing multiple in the Big Six while running the fastest-growing Cloud franchise.
The setup strengthens further if Cloud maintains 60%+ growth into Q4 and TPU system sales ramp on schedule into 2027. The thesis weakens if free cash flow stays negative through year-end 2026 while regulatory rulings force structural remedies.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $504.76 |
| 2027 | $625 |
| 2028 | $755 |
| 2029 | $890 |
| 2030 | $1,031.89 |
These projections assume Alphabet continues executing its AI infrastructure build while Search and YouTube compound. The same data-center demand powering that build is lifting a whole tier of suppliers behind the scenes (we profiled seven of them, from power to cooling, in a free report). Meaningful upside or downside could result from Waymo commercialization or an adverse antitrust remedy.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.