Meta Price Targets Hiked to $900 as Analyst Cite AI Momentum, Revenue Growth Paths
Two major Wall Street firms just handed Meta dramatically higher price targets, and the reasoning goes well beyond advertising. The real question is whether Meta's AI spending spree is finally opening doors that could redefine its growth story.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Meta Platforms (NASDAQ:META | META Price Prediction) is drawing a fresh wave of bullish Wall Street revisions, with KeyBanc analyst Justin Patterson lifting his price target to $900 from $780 and Cantor Fitzgerald raising its target to $860 from $680, both keeping Overweight ratings.
Both firms cite momentum around Meta’s Muse AI assistant and multiple emerging revenue lanes. For long-term investors, the coordinated price target raised signals conviction that Meta’s AI spend is starting to translate into tangible growth paths.
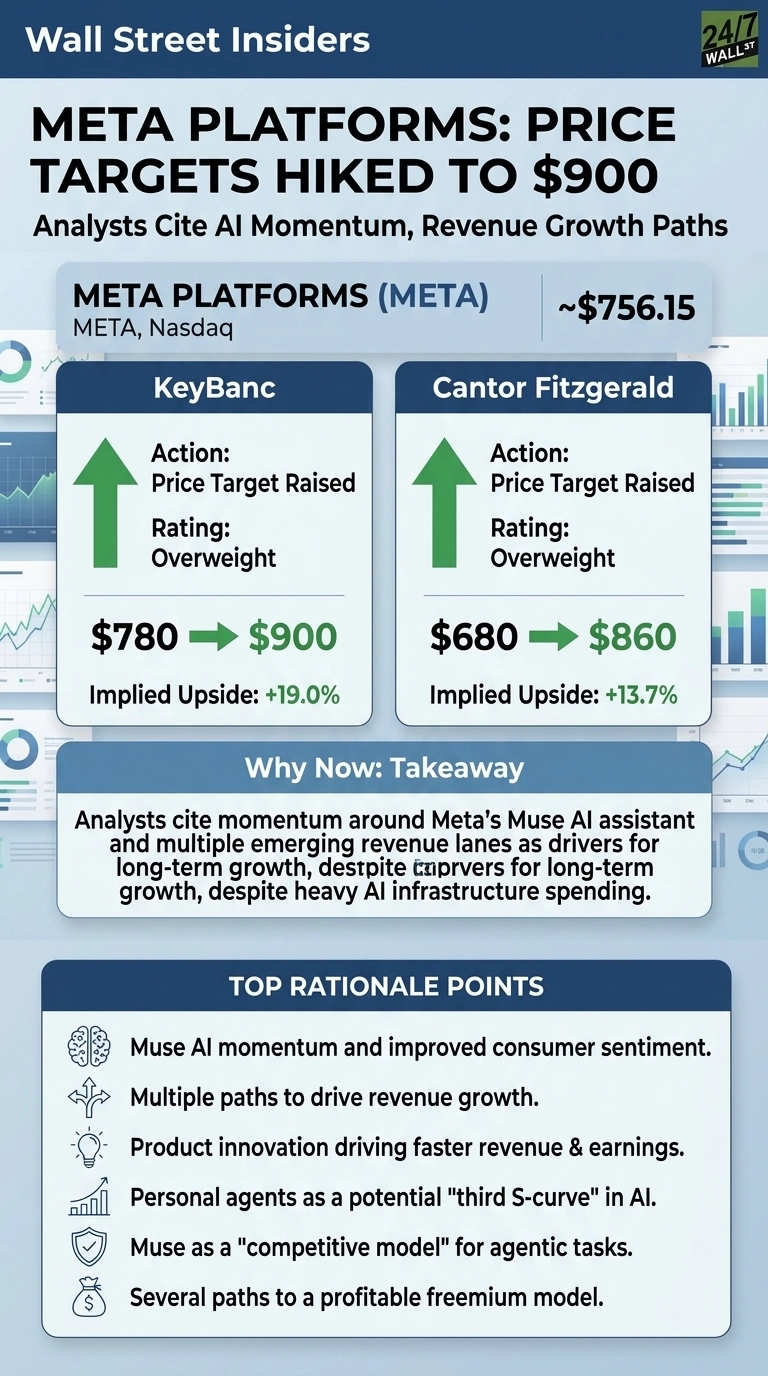

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| META | Meta Platforms | KeyBanc | Price target raised | Overweight | Overweight | $780 | $900 |
| META | Meta Platforms | Cantor Fitzgerald | Price target raised | Overweight | Overweight | $680 | $860 |
Analyst Case
KeyBanc’s Patterson argues that Muse’s momentum reinforces the view that sentiment around consumer AI is poised to improve, and that Meta now has “multiple paths to drive revenue growth.” The firm expects product innovation to drive faster medium-term revenue and earnings growth, supporting multiple expansion.
Cantor Fitzgerald frames personal agents as a potential “third S-curve” in AI, with Meta positioned as a leading beneficiary. Cantor calls Muse a “competitive model” trained to lead in agentic tasks and, while unit economics are currently subsidized, sees “several paths to a profitable freemium model.”

Company Snapshot
Meta carries a market cap near $1.67 trillion and trades around a P/E of 27. Q2 FY2026 revenue reached $60.80 billion, up 27.96% year over year, with advertising revenue of $59.36 billion (+27% YoY).
Diluted EPS came in at $6.18, missing the $7.22 consensus as costs jumped on $2.40B in legal charges and $1.18B in severance. Capex hit $31.1 billion in the quarter, and management guided FY2026 capex to $130 to $145 billion to fund AI infrastructure.

Why the Move Matters Now
Meta stock has ripped higher into these revisions, up 37.6% over the past month and 12.9% in the past week, trading near $756.15.
The 2026 consensus EPS sits at $31.4292, rising to $33.9428 for 2027, with revenue estimates of roughly $254 billion and $306 billion, respectively.
CEO Mark Zuckerberg said on the call that “on a dollar basis, our ads business is reporting faster year over year revenue growth than any other company’s reported ad business.” Reddit sentiment mirrors the tone, with the latest aggregate score at 72 (bullish).

What It Means for Your Portfolio
For retirement-focused investors, the case for Meta stock hinges on whether AI monetization, from ad ranking gains to Advantage Plus reaching over $75 billion in annual revenue run rate and business agents on WhatsApp, can outpace the heavy capex cycle.
With operating margin compressed to 31% from 43% YoY, execution on the “multiple paths” thesis will determine whether these higher targets prove justified.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.