PayPal Just Got a Meta Partnership. Here’s What It Could Mean for the Stock
PayPal just landed a checkout deal with Meta and another surprise partnership that sent shares jumping, but the stock is still down more than 20% over the past year and facing real headwinds that could define whether this rally sticks…


PayPal (NASDAQ:PYPL | PYPL Price Prediction) shareholders have reason to cheer the Meta partnership, but the real question is whether one-tap checkout on Facebook can move a stock grinding sideways through 2026.
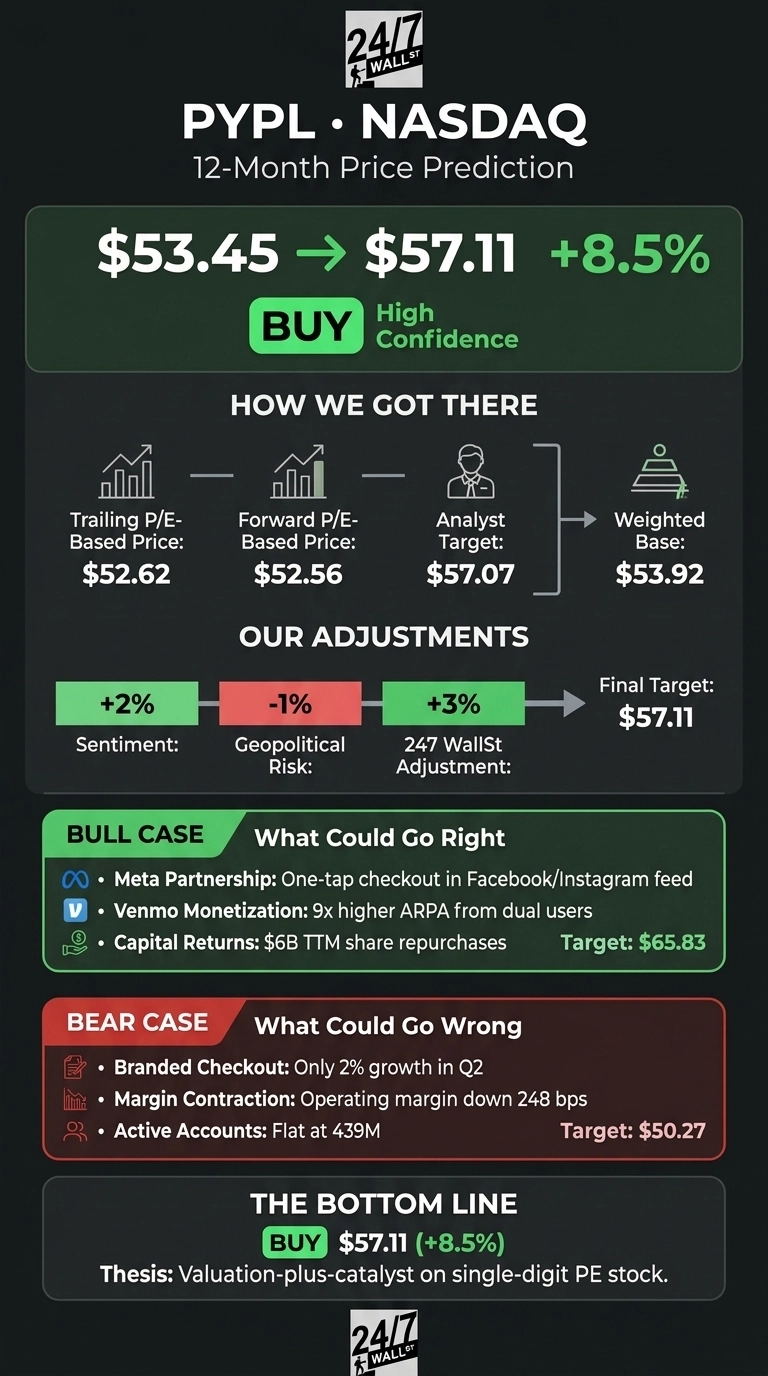
Our 24/7 Wall St. price target is $57.11, versus a current price of $53.45, implying roughly 8.5% upside over 12 months. The model rates this a buy with 90% confidence. This is a valuation-plus-catalyst call on a stock trading at single-digit earnings.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $53.45 |
| 24/7 Wall St. Price Target | $57.11 |
| Upside | 8.5% |
| Recommendation | BUY |
| Confidence Level | 90% |

A Rough Year Meets a Fresh Catalyst
PayPal shares are down 20.77% over the past year and 12.94% in the past month, well below the 52-week high of $78.34 but above the 52-week low of $38.12.
The Meta partnership, announced at Shoptalk 2026, enables one-tap checkout inside the Facebook feed and is expected to eventually extend to Instagram. Barron’s reported PayPal is partnering with Muse, sending shares higher.
Those catalysts land on top of a solid Q2 2026 earnings report. PayPal delivered non-GAAP EPS of $1.38 versus $1.28 expected on revenue of $8.68B (+4.75% YoY), with total payment volume of $486.4B and Venmo TPV up 14%. Management raised full-year non-GAAP EPS guidance to approximately $5.38.

Why Bulls See a Breakout Ahead
The bull case rests on three legs. First, checkout distribution: the Meta integration plus prior deals with Google, OpenAI, and Perplexity position PayPal as a default rail in social and AI-native commerce.
Second, Venmo monetization, where users of both Venmo debit and Pay with Venmo generate more than nine times higher ARPA than peer-to-peer-only users.
Third, capital return: PayPal repurchased $6 billion of stock on a trailing-12-month basis, shrinking the float into a depressed multiple.
The bull-case one-year price is $65.83, a 25% total return. The high-end 2027 EPS estimate of $6.08 supports a run toward $70 if the multiple re-rates modestly.

Risks Worth Watching
The bear thesis: branded checkout grew just 2% currency-neutral in Q2, operating margin contracted 248 basis points, and active accounts remain flat at 439M. A $120 to $140 million transformation charge is expected in H2 2026.
Bulls counter that margin compression reflects reinvestment in Venmo, BNPL, and AI, and free cash flow surged 156.5% YoY to $1.775B. Prediction markets assign only a 13.5% probability of acquisition before 2027. Our bear-case one-year price is $50.27.
How PayPal Compares to Visa and Block
Visa (NYSE:V) is the valuation-contrast peer, trading at a premium justified by Q3 FY2026 revenue of $11.63B (+14.4% YoY) and EPS of $3.32, roughly triple PayPal’s growth rate. PayPal’s forward P/E of 9 looks genuinely cheap, but the market is pricing PayPal’s slower growth accurately.
Block (NYSE:XYZ) is the closer comp, with a market cap of roughly $42B. It posted Q2 2026 gross profit of $3.17B, up 25% YoY, and guided to full-year adjusted EPS of $4.02. Block is growing faster; PayPal is more profitable and returns more cash.
| Company | Forward P/E | Market Cap |
|---|---|---|
| PayPal | 9 | ~$45.7B |
| Visa | Premium | $619B |
| Block | Growth-tier | $42B |
PayPal Price Prediction 2026 to 2030
The 24/7 Wall St. price target of $57.11 reflects a buy rating with 90% confidence. The key factor is the mismatch between a forward P/E of 9 and a company generating $1.8 billion in quarterly free cash flow while shrinking the float.
The bull thesis strengthens if branded checkout growth accelerates into the mid-single digits in Q4 and Venmo monetization continues compounding. The bear thesis reasserts itself if H2 transformation charges expand or Meta and Muse deals fail to translate into measurable TPV lift by early 2027.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $57.11 |
| 2027 | $61.41 |
| 2028 | $63.97 |
| 2029 | $68.86 |
| 2030 | $72.51 |
These projections assume PayPal continues executing on its transformation plan. Significant upside could come from agentic-commerce revenue materializing faster than expected, while downside risk centers on further branded-checkout erosion or a competitive response from Apple Pay and Stripe.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.