189%: The Year to Date Number That Pushed AMD Into the Trillion Dollar Club
AMD just crossed a threshold that only a handful of chip companies have ever reached, but the same rally that created a trillion dollar milestone may have put the stock in an uncomfortable position relative to where our model says…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
AMD (NASDAQ:AMD | AMD Price Prediction) just did something few semiconductor companies ever accomplish: it joined the trillion dollar club. Shares are up 187.87% year to date and 291.71% over the last twelve months, propelled by an AI accelerator ramp that has finally translated into hard numbers on the income statement.
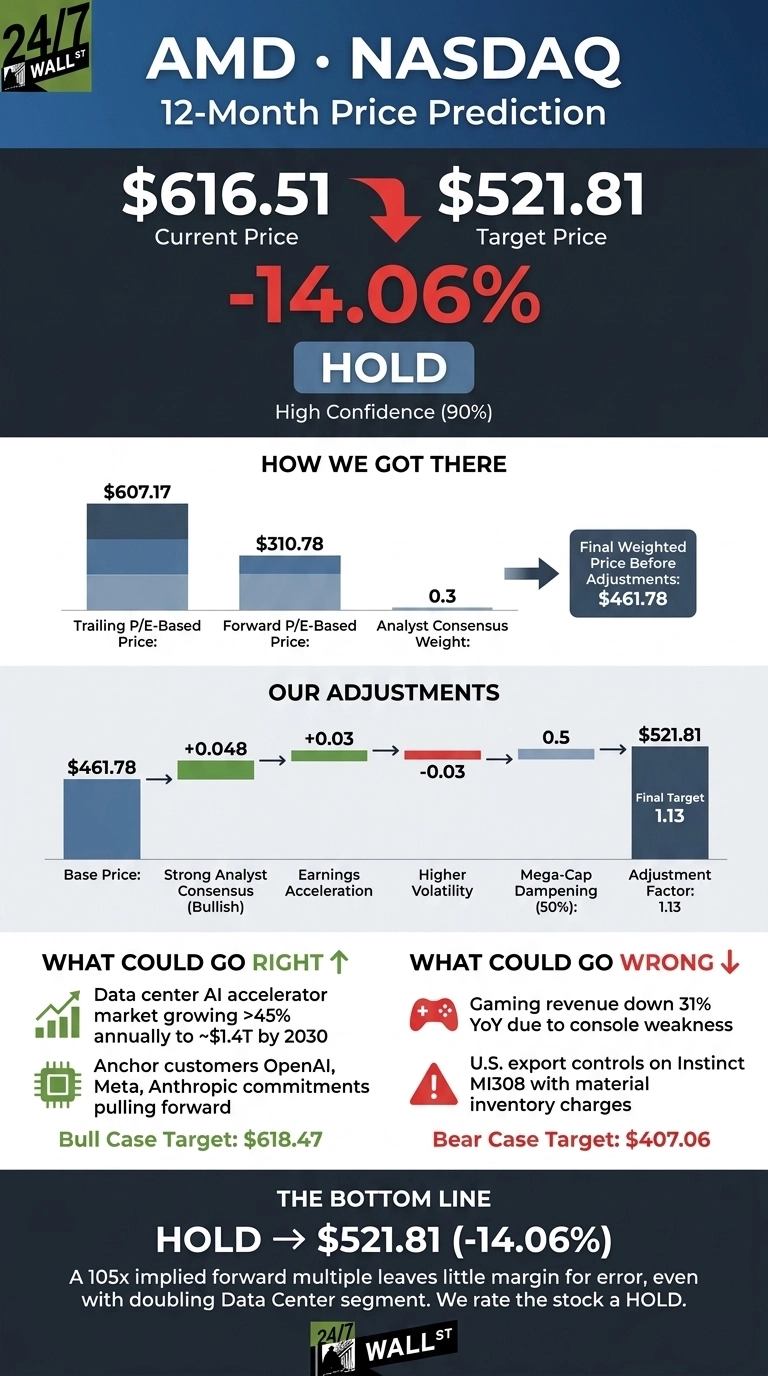
Our 24/7 Wall St. price target for AMD is $521.81 over the next 12 months, implying downside of roughly 14.06% from the current $616.51. We rate the stock a hold with high (90%) confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $616.51 |
| 24/7 Wall St. Price Target | $521.81 |
| Upside/Downside | -14.06% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Why We Could Be Wrong
Our 24/7 Wall St. price target sits below where AMD trades today. Real upside could come from the Helios rack-scale ramp exceeding expectations or from the OpenAI 6 GW and Meta 6 GW commitments pulling forward.
Trillion Dollar Milestone Powered by a Data Center Doubling
AMD gained 24.95% in the past week and 30.27% over the past month, hitting $1 trillion in market value for the first time.
Q2 FY26 revenue jumped 50% year-over-year to $11.5 billion, with Data Center revenue growing 107% to a record $6.7 billion and now representing 58% of total revenue. Non-GAAP EPS came in at $1.66, beating consensus by 3.06%. Q3 guidance calls for approximately $13 billion in revenue, up roughly 41% year-over-year.

Why Bulls See a Breakout Ahead
The bull case rests on a data center trajectory outrunning the model. CEO Lisa Su told analysts AMD is “still in the early innings of a multi-year AI adoption cycle” and sees the data center AI accelerator market growing more than 45% annually to approximately $1.4 trillion by 2030.
A market that size has to be powered, cooled, and networked by someone, and we profiled seven of those suppliers in a free AI infrastructure report.
AMD guided 2027 Data Center segment revenue to more than double, with server revenue growth of more than 70% for the full year. Anchor customers include OpenAI, Meta, and Anthropic. In the bull scenario, our model path reaches $618.47 in twelve months.

What Could Go Wrong
Gaming revenue fell 31% year-over-year on semi-custom console weakness. U.S. export controls on Instinct MI308 have produced material inventory charges. NVIDIA remains dominant in AI GPUs, and AMD trades at a trailing P/E of 232. Insider activity is currently net selling.
Bulls counter that margin dilution reflects heavy Helios investment and that the software stack is compounding, with open-source Rackham contributions up more than tenfold. Our bear-case path lands at $407.06.
How AMD Compares to NVIDIA, Broadcom, and Intel
NVIDIA (NASDAQ:NVDA) is the direct AI GPU competitor at a $5.52 trillion market cap, yet trades at just 46x trailing earnings versus AMD’s 232x, with a 60% operating margin. That gap makes AMD’s premium look aggressive on current profits.
Broadcom (NASDAQ:AVGO) posted AI semiconductor revenue of $16.7 billion, up 221% year-over-year, and guided Q4 AI revenue to $21.7 billion.
Intel (NASDAQ:INTC) is the value counterpoint, with a $641 billion market cap despite negative net margins. The peer set makes our target look reasonable.
| Company | Trailing P/E | Market Cap |
|---|---|---|
| AMD | 232 | $1.00T |
| NVIDIA | 46 | $5.52T |
| Broadcom | n/a | $1.73T |
AMD Price Prediction 2026-2030
My final call is hold at $521.81. A 105x implied forward multiple leaves little margin for error, even with a doubling Data Center segment.
We would grow more constructive if Helios shipments in Q4 exceed AMD’s own commentary and the MI500 timeline pulls forward. We would grow more cautious if gaming weakness spreads or China export headlines re-intensify.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $563.17 |
| 2027 | $524.85 |
| 2028 | $467.55 |
| 2029 | $477.72 |
| 2030 | $481.15 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.