Salesforce Is Cheap. ServiceNow Is Growing Faster. Here’s the Stock I’d Buy.
Two AI software giants both reported strong agentic bookings this summer, but they sit at opposite ends of the valuation spectrum. The case for buying the cheaper one is stronger than it looks, and the case against it is equally…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

ServiceNow (NYSE:NOW | NOW Price Prediction) and Salesforce (NYSE:CRM) both reported this summer with the same message: agentic AI is now showing up in bookings. They differ sharply on price.
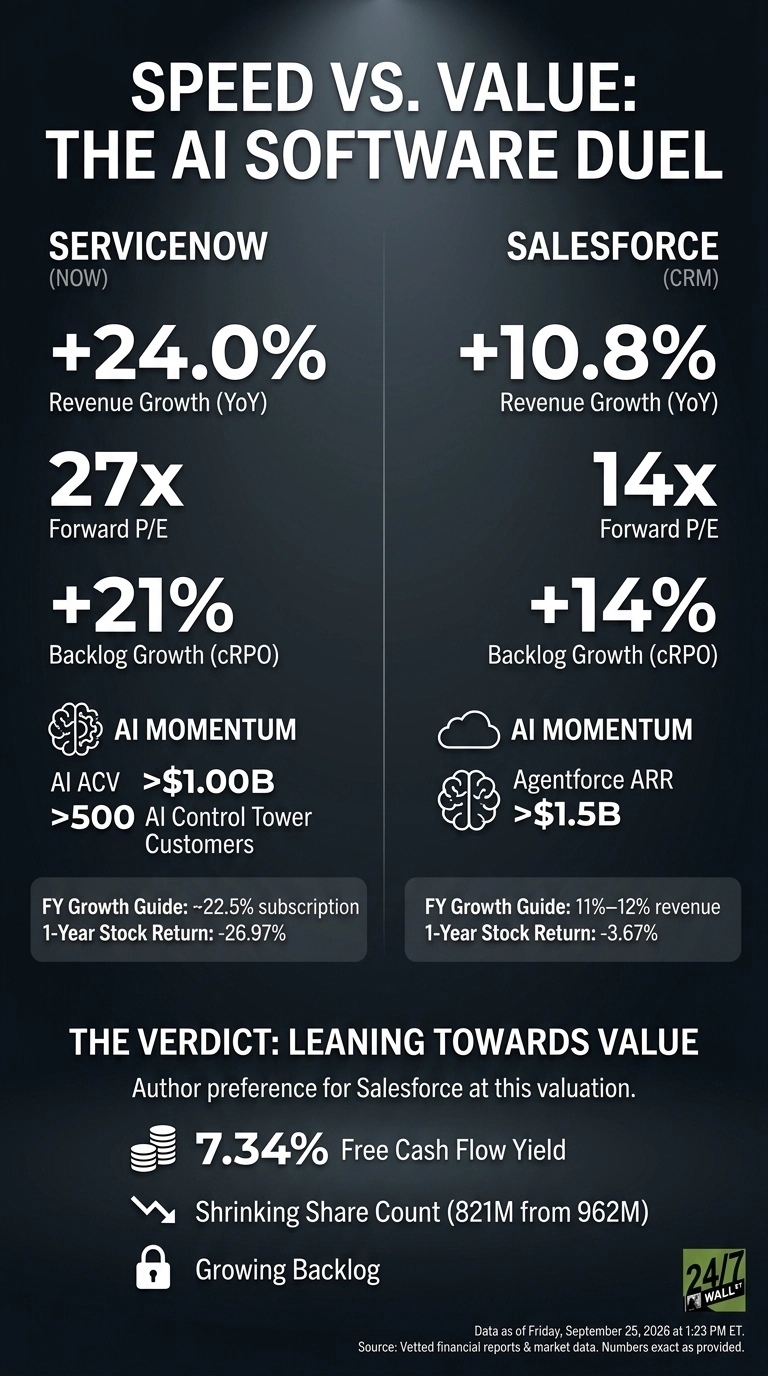
ServiceNow grew revenue 24% and trades at 27x forward earnings. Salesforce grew 10.8% at about 14x. So investors have to pick between speed and value.
Governance Sells at ServiceNow While Salesforce Customers Keep Refilling the Tank
ServiceNow’s subscription revenue reached $3.877B, up 24.5%. That is rare speed at this scale. Its AI annual contract value (ACV) passed $1B. More than 500 customers went live on AI Control Tower within six months.
That product manages AI agents across other vendors’ platforms, which puts ServiceNow in charge of everyone else’s AI. The CFO summed up the pitch: “Customers aren’t paying us for tokens, they’re paying for resolutions.” ServiceNow is also moving onto Salesforce’s territory.

Salesforce’s current remaining performance obligations (cRPO, or contracted revenue due within 12 months) rose 14%, up from 13% last quarter. The backlog is starting to speed up again. Agentforce annual recurring revenue exceeded $1.5B, and 50% of bookings came from customers buying more credits. That points to real usage beyond pilot projects.
I remain skeptical of the headline earnings, though. Non-GAAP EPS of $5.90 included about $2.53/share from investment profits. The Informatica acquisition also added $456M in revenue.

| Business Driver | ServiceNow | Salesforce |
|---|---|---|
| AI Engine | AI Control Tower, Now Assist | Agentforce, Data 360 |
| Backlog Growth | 21% | 14% |
| Newest Push | Cybersecurity via Armis, Veza | CloudForce with Anthropic |
One Wants to Govern Every Agent. One Wants to Own the Customer Record.
ServiceNow is buying its way into security. Its chief executive called cybersecurity “a massive tailwind”. The acquisitions carry a cost: GAAP subscription gross margin slipped to 73.5% from 80% because of amortization of acquired assets.

Salesforce leans on upselling and buybacks. Only 5% of sales and service users have upgraded to premium editions, which carry a 60% to 80% price premium. That leaves plenty of room to upsell. Its $25B accelerated buyback cut diluted shares to 821M from 962M.
| Lens | ServiceNow | Salesforce |
|---|---|---|
| Forward P/E | 27x | 14x |
| Full-Year Growth Guide | ~22.5% subscription | 11% to 12% revenue |
| One-Year Stock Return | -26.97% | -3.67% |
ServiceNow’s steeper fall has already narrowed its premium. It still costs about twice as much per dollar of forward earnings.

Q3 Reveals Whether ServiceNow’s Federal Pull-Forward Leaves a Gap
ServiceNow guided Q3 subscription growth to about 20.5%, partly because some U.S. federal revenue landed in Q2 instead of Q3. A key question is whether cRPO holds near the 20% guide.
Salesforce’s management expects organic growth to pick up in the second half. Dreamforce landed as a small success even as the stock fell, so investors want proof.
Why I Lean Toward Salesforce at 14 Times Earnings
I think ServiceNow has the better business. Its products are growing faster, and AI Control Tower gives it an unusual position. Still, I lean toward Salesforce at this valuation. A 7.34% free cash flow yield, a growing backlog and a shrinking share count give me several ways to make money.
Growth investors comfortable paying up will prefer ServiceNow. I would change my view if Salesforce’s organic growth stalls in Q3, or if ServiceNow shows the federal shift left no gap.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.