Tesla Is Running Their Old Announce And Delay Playbook With The Roadster
Tesla keeps setting bold product deadlines, and the stock keeps rallying on the reveal before the date quietly disappears. With several major 2026 targets now on the clock, investors face a question of whether this time is different or the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
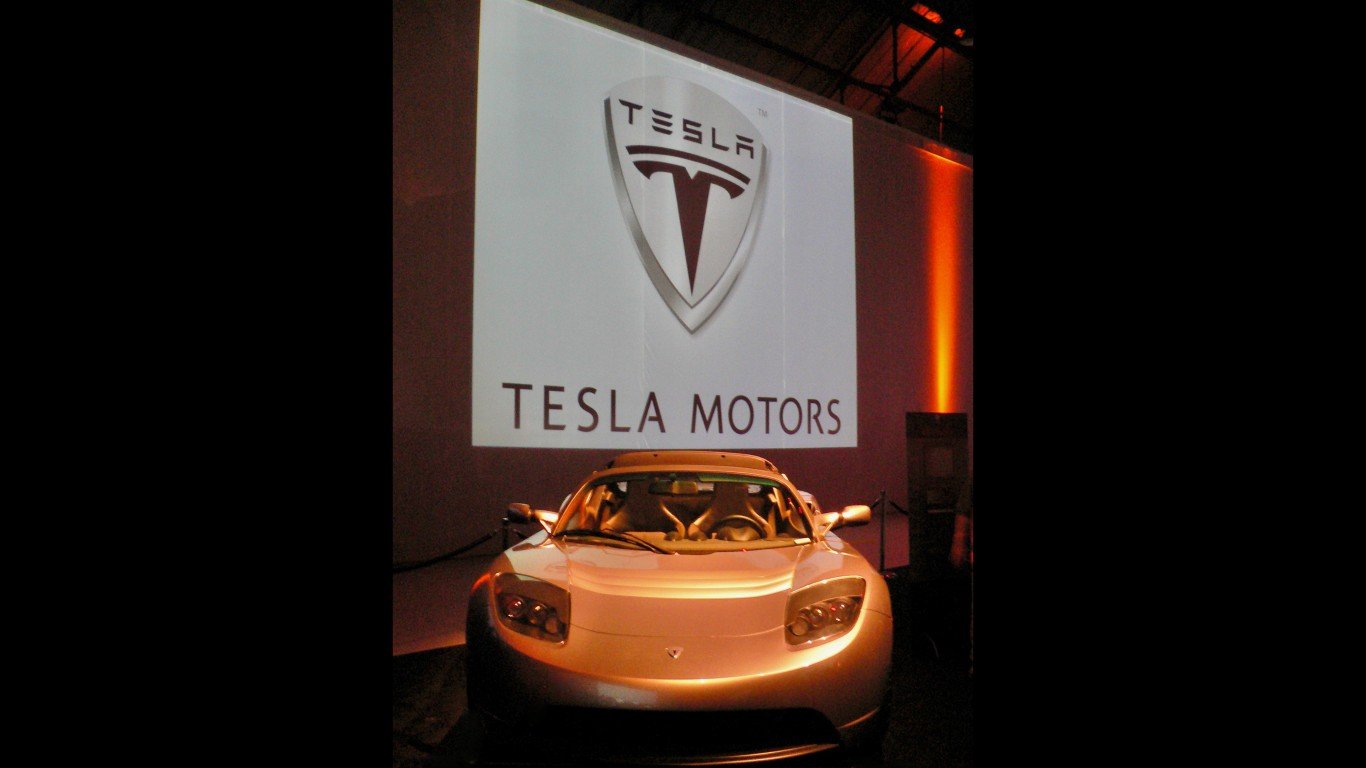
Tesla (NASDAQ:TSLA | TSLA Price Prediction) trades at $352.84, and the setup looks poor. The long-delayed Roadster shows a pattern: Tesla announces products faster than it ships them. Shares are down 21.54% this year as the market prices in that credibility gap.
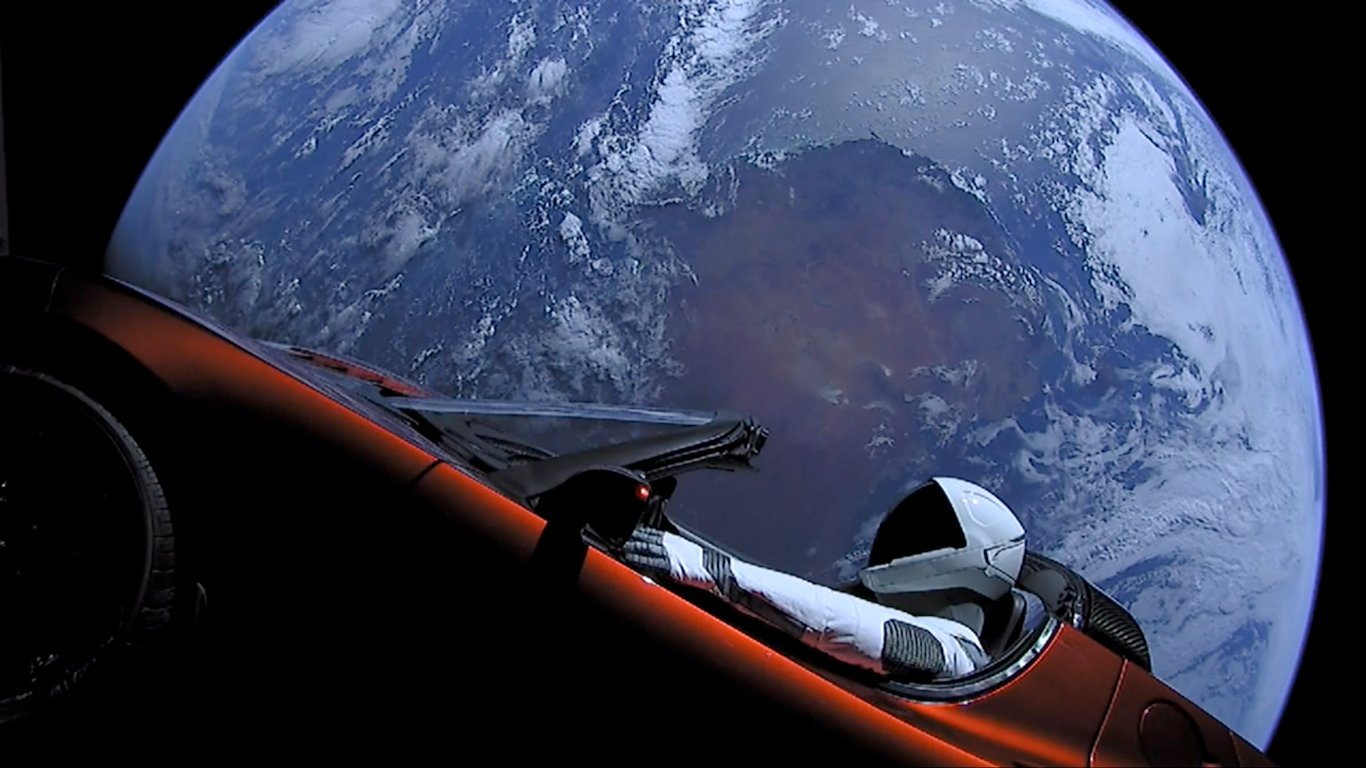
Tesla revealed the next-generation Roadster in 2017 and promised deliveries by 2020. Its latest annual filing still lists the car as “in design development” with no timeline. Cybertruck was promised for 2021 and arrived in late 2023. The Semi, also unveiled in 2017, is still listed as starting production in 2026.
Record Deliveries and a $43.5 Billion Cash Pile Power the Robotaxi Pitch
Second-quarter revenue rose 25.5% to $28.24 billion, beating estimates. Record deliveries reached 480,126 vehicles. Energy storage installations grew 41% to 13.5 GWh. FSD (Tesla’s paid driver-assistance software) rose to 1.48 million active subscriptions.
Robotaxi operates in seven U.S. markets after logging “more than 380,000 miles of unsupervised Robotaxi” with “zero notable incidents.” FSD also won approval in Croatia. With $43.5 billion in cash, Tesla can fund its AI ambitions for years.
A 344x Earnings Multiple Sits on Shrinking Profits
Tesla is priced at 344 times trailing earnings and 159 times forward earnings. Second-quarter EPS of $0.33 missed expectations of $0.54. Operating margin fell to 1.4%, and free cash flow came in at negative $1.09 billion.
Management expects 2026 capex above $25 billion and is lining up debt facilities of up to $30 billion. Energy gross margin dropped from 39.5% to 20.4%.
Optimus and Cybercab Deadlines Decide Whether Patience Pays
Tesla finished the quarter with its largest order backlog since 2023. The CEO described Optimus as “the hardest product to scale manufacturing that we’ve ever made at Tesla,” with an early ramp that will be “quite flat and long.” Whether Cybercab, Semi, and Megapack 3 reach volume production in 2026 as planned will determine which side wins.
Wall Street Sees Upside While Tesla Lags the Market Badly
The 46 analysts covering Tesla have an average target of $395.83, indicating 12.2% upside. Ratings break down as follows:
- Strong Buy: 6
- Buy: 16
- Hold: 19
- Sell: 3
- Strong Sell: 2
Over the past year, Tesla fell 20.39% while the S&P 500 gained 15.16%. The stock also trades below its 200-day moving average of $395.18.
Credibility Gap Weighs on Tesla Until Deadlines Turn Into Deliveries
The risk/reward looks poor at $352.84.
Tesla announces products with firm dates, the stock rallies on the reveal, and the deadline slips out of sight. The Roadster is the clearest case. Hype moves the price while promises keep falling through.
The biggest risk comes over the next few quarters. Tesla has several 2026 production targets due and capex that keeps growing. If Cybercab or Semi volumes slip into next year while margins stay near 1.4%, the multiple has room to compress. Operating expenses are also expected to keep growing.
Two things would force a rethink: free cash flow turning positive again and Semi shipping in real volume on schedule. Until either happens, watch the stock but stay skeptical of each new reveal.
At $352.84, Tesla’s valuation appears to price in more credibility than its delivery record has earned.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.