The Boring Tech Stock With an AI Tailwind Has 17% Upside
Cisco just posted its fifth straight earnings beat while AI infrastructure orders piled up faster than Wall Street expected, yet the stock sits nearly 18% below its 52-week high. Something does not add up, and the answer could mean serious…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Our 24/7 Wall St. price target for Cisco Systems (NASDAQ:CSCO | CSCO Price Prediction) is $125.42 over the next 12 months. That is 17.6% above today’s price, and our model rates the stock a buy.
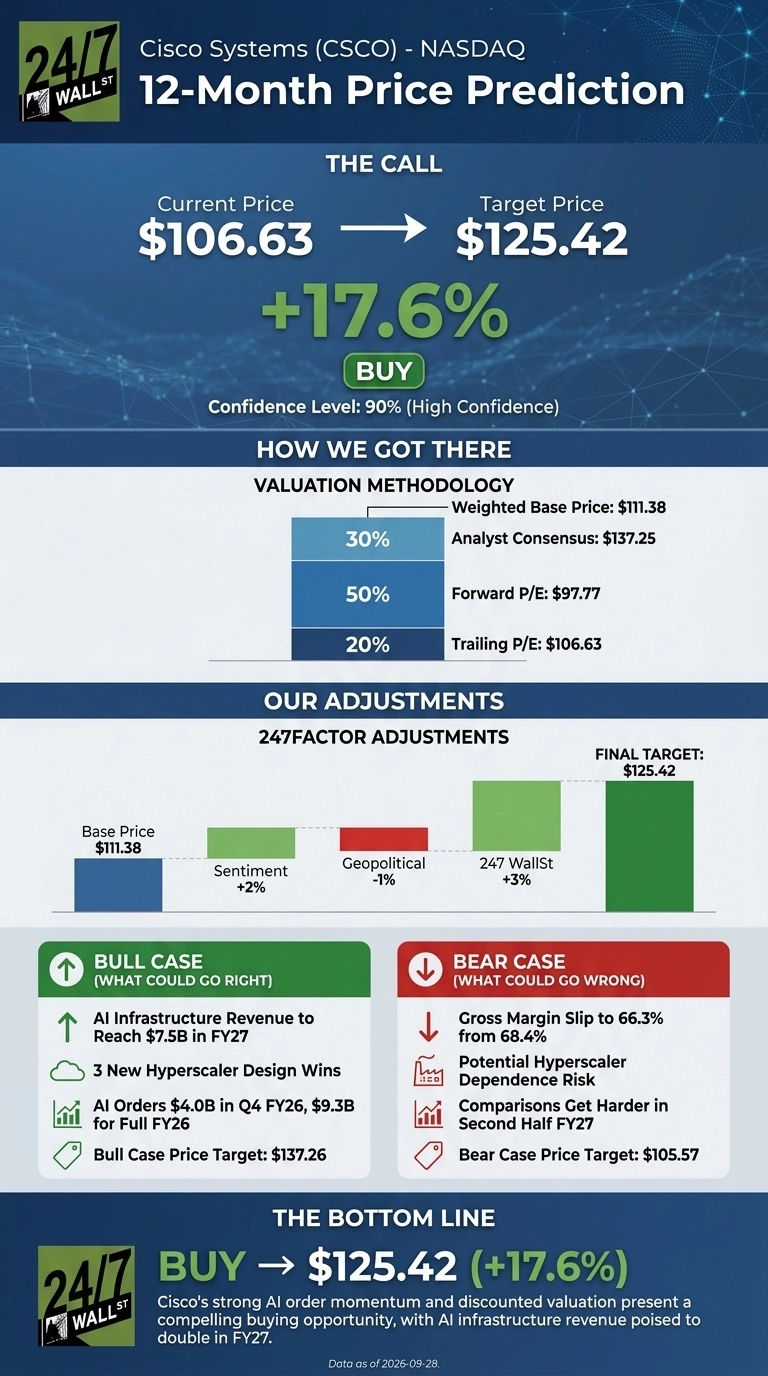

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $106.63 |
| Price Target from 24/7 Wall St. | $125.42 |
| Upside/Downside | 17.62% |
| Recommendation | BUY |
| Confidence Level | 90% |
For years, investors owned Cisco mainly for the dividend. Now the company is booking AI infrastructure orders fast enough to drive revenue growth into the high teens. The stock trades at about 21x forward earnings, well below pure-play AI networking stocks.
Record Earnings Collide With a September Pullback
Shares are up 40.98% year to date and 61.02% over the past year. They fell 2.25% over the past week and 4.73% over the past month, partly after Piper Sandler cut its price target (CNBC). The stock sits 17.9% below its 52-week high of $129.88.
The fundamentals point the other way. Fiscal fourth-quarter revenue came in at $17.25B, up 17.6% and ahead of the $16.83B consensus. Non-GAAP EPS of $1.22 exceeded the $1.17 estimate, Cisco’s fifth consecutive EPS beat.
AI infrastructure orders reached $4B in the quarter and $9.3B for the fiscal year. Management raised fiscal 2027 guidance to $72.2B–$73.4B in revenue and $5.05–$5.11 in non-GAAP EPS.

Why Bulls See $137 and Beyond
Management expects AI infrastructure revenue of about $7.5B in fiscal 2027, up from roughly $4B this year. Cisco also added three new hyperscaler design wins in the quarter. CEO Chuck Robbins said on the call, “We believe we’re only at the beginning of this super cycle.” CFO Mark Patterson added that orders should be “meaningfully higher” in fiscal 2027.

Wall Street agrees. Covering analysts count 5 Strong Buys, 14 Buys, 9 Holds and zero Sells. The bull case lands at $137.26.

Margin Squeeze and Hyperscaler Dependence Could Cap Gains
Non-GAAP gross margin slipped to 66.3% from 68.4% as the sales mix shifted toward AI hardware. Price increases added about five points to fourth-quarter growth. Management warned comparisons get harder in the second half of fiscal 2027. Our bear case is $105.57.
There is a counterpoint. Management says lower-margin hyperscaler hardware still earns attractive operating profits because it adds little extra expense. Guidance calls for an operating margin of about 35%, and $8.1B remains on the buyback authorization.
Cisco Trades at a Deep Discount to Faster-Growing Rivals
Arista Networks (NYSE:ANET) competes directly with Cisco in AI data center switching. Last quarter it grew revenue 37.69%, but the stock trades at 74x trailing earnings.
Hewlett Packard Enterprise (NYSE:HPE) now owns Juniper, and its networking revenue rose 74.9%. HPE guides to 16%-20% non-GAAP EPS growth in fiscal 2027, close to Cisco’s rate, but with much lower margins.
| Company | P/E | Latest Quarter Revenue Growth | Non-GAAP Operating Margin |
|---|---|---|---|
| Cisco | 21x forward | 17.6% | 35.9% |
| Arista | 74x trailing | 37.69% | 49.9% |
| HPE | Not meaningful | 32.72% | 16.2% |
Compared with these peers, our 24/7 Wall St. price target looks reasonable and arguably conservative.
Cisco’s AI Order Book Tips the Scale Toward Upside
My 24/7 Wall St. price target is $125.42, with a buy rating and 90% confidence. Cisco trades at a discount even though AI infrastructure revenue is on track to nearly double.
I would turn cautious if AI orders stall or gross margins keep sliding. On the evidence so far, the AI boost looks stronger than the market is giving it credit for.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $111.04 |
| 2027 | $125.42 |
| 2028 | $136.83 |
| 2029 | $149.28 |
| 2030 | $162.86 |
Cisco would need to keep executing its AI networking strategy for these projections to hold. A lasting cut in hyperscaler capital spending would be the biggest risk to that path. Cisco is one of several non-chip names riding the data-center expansion, and we covered seven of them, from power to networking, in a free report you can grab here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.