This AI Software Stock Could Surprise Investors by 2028
ServiceNow just crossed $1 billion in AI contract value while its stock sits near a multi-year low, and Wall Street's consensus price target barely scratches the surface of what our model projects for 2028.


ServiceNow (NYSE:NOW | NOW Price Prediction) says its AI business has passed $1 billion in annual contract value. Yet the stock is down 12.52% year to date. Subscription revenue reached $3.877 billion last quarter, up 24.5%.
CEO Bill McDermott said: “We are who we said we were: a defining company that is only just getting started.” Investors remain skeptical. Can ServiceNow shares hit $300 in 2028?

What’s Holding ServiceNow Back Right Now
Shares fell 4.81% last week and 9.45% over the past month, leaving them 27.19% below a year ago.
Operating income fell 54.75% year-over-year, and GAAP EPS of $0.31 missed the $0.4 estimate. GAAP subscription gross margin dropped to 73.5% from 80% due to acquisition amortization.
Management noted Q2 gained from U.S. federal deals pulled forward from Q3. Fear that AI agents will disrupt seat-based software compounds the pressure. The beta is 0.972, so this decline reflects company-specific weakness.
Wall Street Sees 8.2% Upside. Our Model Says 78.1%
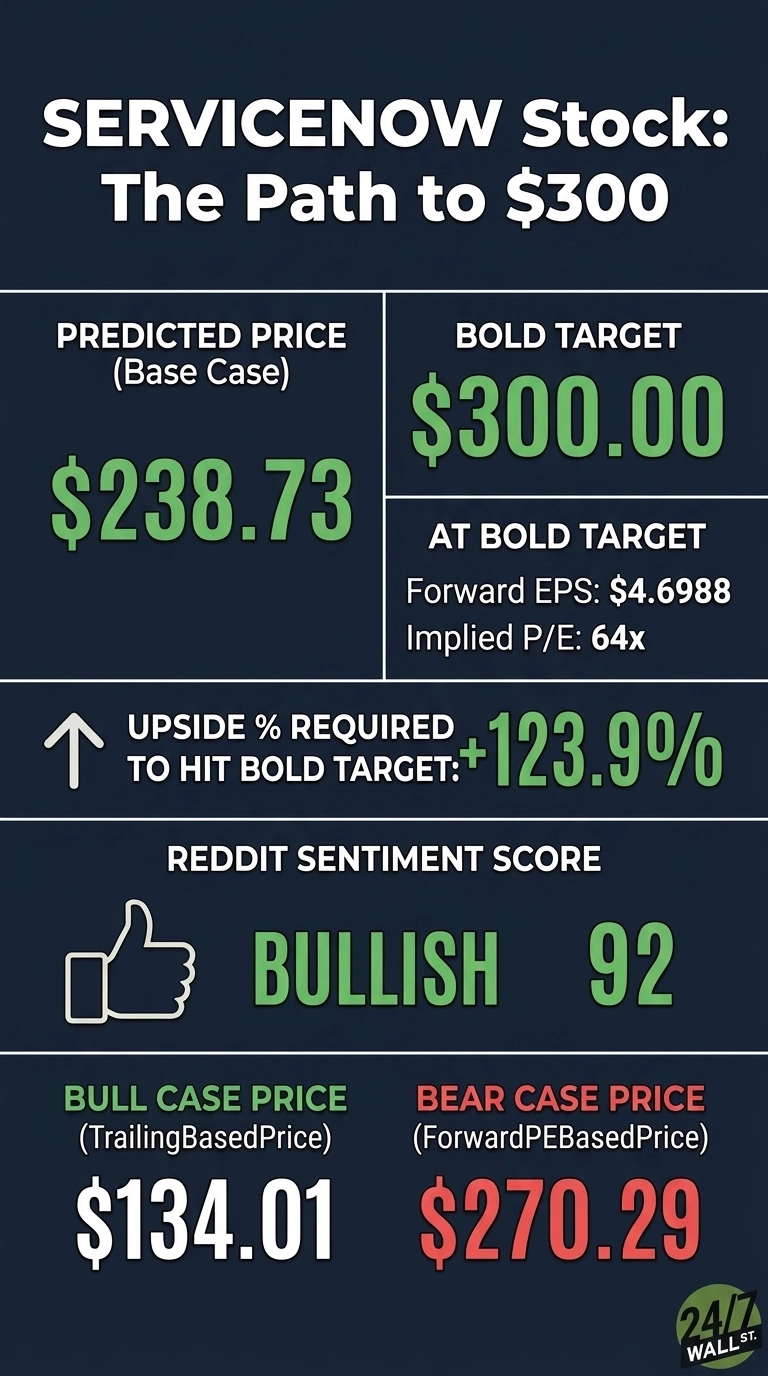
The consensus price target is $144.99, only 8.2% above the September 30 close of $134.01. Yet analyst ratings are 92% bullish. The base case is $238.73, implying 78.1% upside.
The range spans $189.05 (bear) to $264.44 (bull). Analysts fixate on the GAAP earnings drop, which subtracted 0.022 from our growth factor, mostly from deal costs. Free cash flow rose 20.53% and renewals held at 98%.
Here’s What It Takes for ServiceNow to Reach $300
A $300 price from today’s $134.01 means a 123.9% gain. At forward EPS of $4.6988, $300 implies a forward P/E of about 64x. The base case of $238.73 implies about 51x, so the $300 target needs another 13x of multiple expansion.

Our long-range base path reaches $290.54 by April 2028. The adjustment factor of 1.162 applies a technology sector multiplier of 1.15, offset by a 0.7 large-cap discount. Forward multiples will compress if EPS increases at the 24.54% consensus rate.
Management targets $30B+ in subscription revenues by 2030. Agentic AI deployments rose 9x in 9 months, with new AI-native SKUs driving 20-30% price increases. Management called the quarter “the foundation for a re-rating of ServiceNow.”
The main risk: AI computing costs squeeze gross margins longer than investors will bear.
Where ServiceNow Trades Today vs. Its Earnings Power
At $134.01, ServiceNow trades at about 29x forward earnings. Revenue increases 24% with a guided 35% free cash flow margin, making that multiple reasonable.
The 52-week range is $81.24 to $192.97. The 10-year return is 746.56%, but the five-year return is only 5.89%, suggesting valuation has adjusted lower.

Is $300 Realistic? Here’s My Verdict
A 123.9% gain to $300 is a stretch but possible.
Three things must line up: ServiceNow AI beats its $1.5 billion ACV target for 2026; margin pressure from Armis fades by FY2027; stock-based compensation falls toward the less than 10% of revenue goal for 2029. A sustained pullback in enterprise spending would undermine the thesis. Keep an eye on AI contract value and margin trends as the clearest signals of progress toward $300 in 2028.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.