Prediction: This AI Stock Could Be Much Bigger by 2028
ServiceNow's AI business is accelerating while its stock sits near a 52-week low, and that disconnect has our model flagging an opportunity most investors are pricing wrong.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Our 24/7 Wall St. price target for ServiceNow (NYSE:NOW | NOW Price Prediction) is $238.73 over the next 12 months. With shares at $135.85, that means 75.7% upside. Our model rates the stock a buy with high confidence.
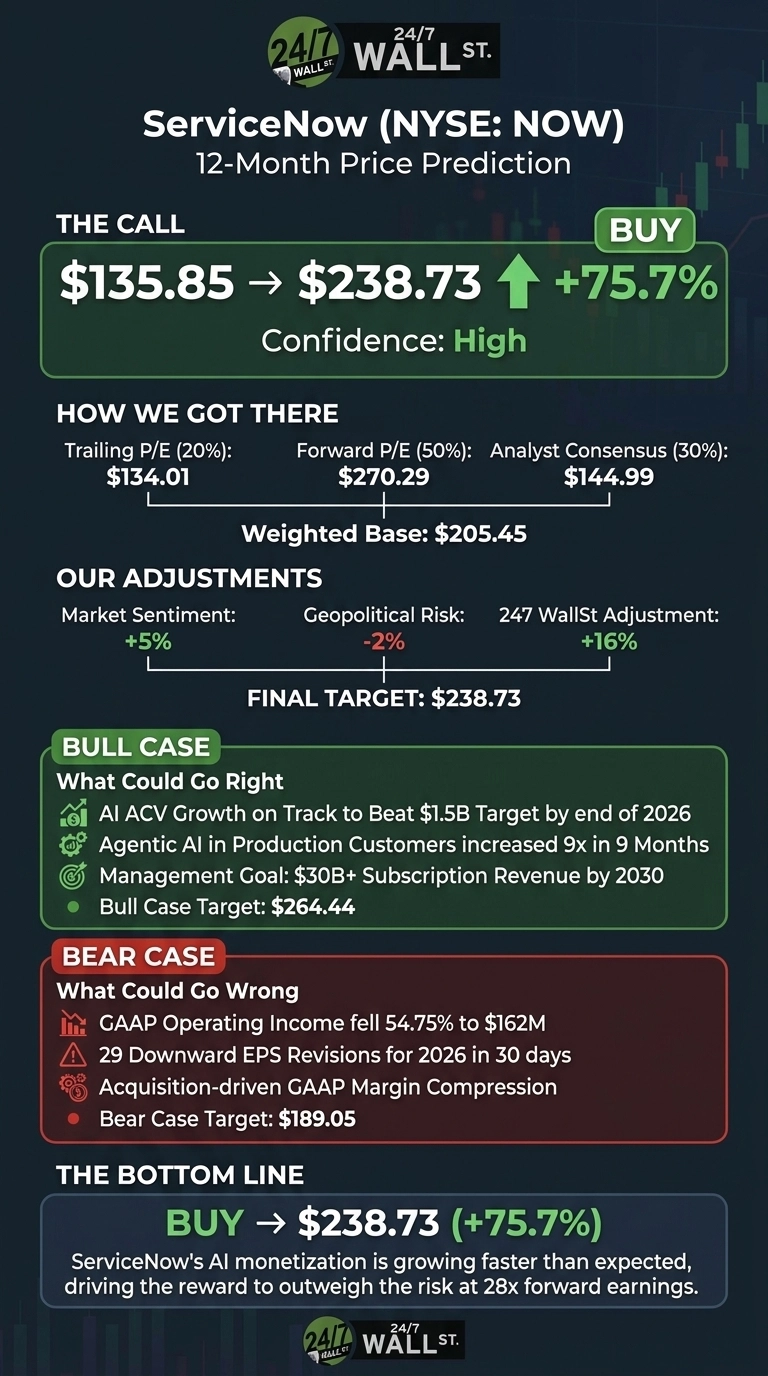
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $135.85 |
| Price Target from 24/7 Wall St. | $238.73 |
| Upside/Downside | 75.7% |
| Recommendation | BUY |
| Confidence Level | 90% |
The market has punished ServiceNow for acquisition-driven GAAP margin compression. Meanwhile, the AI business is speeding up.
ServiceNow AI passed $1B in annual contract value, and the stock trades at 28x forward earnings. Our model sees that gap closing, which is why ServiceNow could be a much bigger company by 2028.

A 26% One-Year Slide Has Reset ServiceNow’s Valuation
Shares are down 3.5% over the past week, 8.2% over the past month, 11.32% year to date and 26.19% over the past year. The stock sits 29.6% below its 52-week high of $192.97 and 67.2% from its low of $81.24.
Fundamentals keep improving even as the share price falls behind. Second-quarter non-GAAP EPS of $0.90 exceeded the $0.86 consensus.
Revenue rose 24% to $3.987B, and management raised full-year subscription guidance to $15.76B to $15.78B. MarketWatch this week named ServiceNow among the tech stocks that could lead the next leg of the AI trade.
Why Bulls See $264 Within a Year
The bull case lands at $264.44. Management said the company is on track to beat its $1.5 billion AI ACV target by end of 2026. Customers running agentic AI in production rose 9x in nine months. Deals above $1 million in net new ACV grew 40% to 123. Renewal rate held at 98%.
Management’s long-term goal is $30B+ in subscription revenue by 2030. CEO Bill McDermott called this “the foundation for a re-rating of ServiceNow.”
Of analysts covering the stock, 10 rate it a strong buy and 35 a buy, with a consensus target of $144.99.
Stifel analyst Brad Reback raised the firm’s price target on ServiceNow to $160 from $120 and keeps a buy rating on the shares while UBS raised the firm’s price target on the stock to $150 from $110 and keeps a Neutral rating on the shares.

What Could Derail the AI Re-Rating
GAAP operating income fell 54.75% to $162M, and GAAP subscription gross margin slipped to 73.5% from 80%. Over the past 30 days, analysts made 29 down revisions to 2026 EPS estimates versus 9 up.
Our bear case is $189.05. Most margin decline comes from amortization of acquired intangibles tied to Armis, expected to normalize in FY27. Free cash flow rose 20.53% to $634M.
Investors looking at ServiceNow’s AI monetization story often miss the companies providing the picks and shovels for the broader expansion (we rounded up seven of those non-chipmaker winners in a free report you can grab here).

ServiceNow Outgrows Salesforce and Workday
Salesforce (NYSE:CRM) competes directly for spending on agentic AI. The stock trades at 25x earnings, but its revenue grew only 10.83%. That earnings figure is also inflated by $2,613 million in gains on strategic investments.
Workday (NASDAQ:WDAY) is ServiceNow’s closest match in workflow software, and its revenue grew 12.82% at 54x earnings.
| Company | P/E | Latest Quarterly Revenue Growth |
|---|---|---|
| ServiceNow | 81x trailing / 28x forward | 24.0% |
| Salesforce | 25x | 10.83% |
| Workday | 54x | 12.82% |
ServiceNow’s revenue is growing about twice as fast as either peer’s, and its forward multiple sits close to Salesforce’s trailing one. Against that background, our target looks reasonable.
ServiceNow Price Prediction 2026-2030
The 24/7 Wall St. price target of $238.73 has a buy rating and 90% confidence. What tips the scale is AI monetization that is growing faster than expected.
The thesis strengthens if AI ACV tops $1.5 billion by year-end. It weakens if GAAP margins keep falling after FY27. At 28x forward earnings, the model sees reward outweighing risk.
Our model projects where ServiceNow could trade, assuming current growth trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $154.82 |
| 2027 | $238.73 |
| 2028 | $356.82 |
| 2029 | $434.78 |
| 2030 | $529.78 |
ServiceNow would need to keep executing on its AI and security strategy for these estimates to hold. Results could beat or miss these figures by a wide margin depending on how fast AI ACV grows and how smoothly the Armis integration goes.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.