Cerebras Systems Cratered by 20% This Year: It’s Going to Double in Price According to This Respected Wall Street Analyst
Cerebras lost more than half its value from its first-day close, insiders cashed out hundreds of millions, and then OpenAI handed a marquee speed workload to a rival. One top Wall Street analyst just raised his target anyway, and his…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
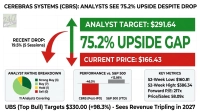
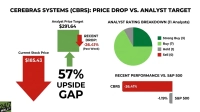
Cerebras Systems (NASDAQ:CBRS) currently trades at $146.62. The average analyst price target is $291.64, which means about 98.9% upside.
Cerebras makes wafer-scale AI chips and leases that compute out through its own inference cloud. Its pitch is speed, as an alternative to GPUs. Wall Street paid attention because of contracted demand: $25.4B in remaining performance obligations, backed by a multi-year OpenAI deal for 750 MW of inference compute.
A gap this wide on a company that just raised full-year guidance means one side is badly wrong. Either analysts are slow to react, or the market is overreacting to a handful of headlines.
OpenAI Hands a Speed Workload to NVIDIA and Cerebras Sinks Below Its IPO Price
The biggest blow: NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) won out, per a SemiAnalysis report that OpenAI will power the “Ultrafast” mode for GPT-6.1 Sol with NVIDIA GPUs instead of Cerebras hardware. Cerebras sells itself on fast inference, so losing a marquee speed workload hits at the core of its thesis. Shares are down 52.87% from the $311.07 first-day close. That is well past the 30% mark that separates a pullback from a collapse, and it leaves the stock below its $185 IPO price.
Supply made it worse. Up to 19.4 million shares held by insiders and employees unlocked, equal to 8% of total shares outstanding. CEO Andrew Feldman and CTO Sean Lie sold over $240 million of Class A shares under trading plans. The stock fell 19.24% over the past week, with 10.69% of that coming in the latest session.
The August earnings report had already shaken confidence. GAAP revenue of $180.11M missed the $193.55M consensus. GAAP EPS of -$2.98 missed the -$0.1801 estimate, mostly because of $377M in stock-based compensation.
UBS Holds a Street-High $330 Target as Estimates Keep Rising
Timothy Arcuri at UBS holds the top target, rating the stock Buy with a $330.00 target. That means about 125.1% upside. His thesis has three parts. First, disaggregated inference gains momentum as spending shifts from training to live inference. Second, capacity expansion gives multi-year revenue visibility. Third, he treats gross margin swings linked to short-term infrastructure rental reallocation costs as an accumulation window.
The company’s own numbers back parts of that view. Core revenue rose 103% to $209.87M, and full-year core revenue guidance went up to $880-$890M. Management called Q3 the low point for core gross margin and targets 60% plus over the long term. Feldman said Cerebras is “preparing for a massive 2027, 2028, and 2029 as we deliver on the $25 billion of RPO we currently have on our books.” Two near-term catalysts stand out: the AMD (NASDAQ:AMD) Helios disaggregated solution, expected to be deployed in Q4, and AWS Bedrock availability in Q1 2027.
Analysts are bullish:
- Strong Buy: 3
- Buy: 7
- Hold: 1
- Sell: 0
The 2027 EPS estimate has rose to $1.2737 from $0.9613 60 days ago, with 9 upward revisions and zero cuts in 30 days. Read that skeptically. The average has stayed flat since before the OpenAI report, so estimates have yet to account for it.
Cerebras Fell Alone While the Chip Giants Held Their Gains
Its peers never sold off with it. NVIDIA slipped 5.27% over the past week but is up 21.64% year to date. At $226.32 against a $328.72 target, it offers 45.2% potential upside, with analyst ratings of 10 Strong Buy, 49 Buy, 2 Hold and 1 Sell. The upside is smaller than Cerebras’, but it rests on a proven earnings base.
AMD fell 5.94% on the week and is still up 177.47% year to date. At $594.24 against a $636.21 target, it offers just 7.1% upside, with 5 Strong Buy, 39 Buy and 11 Hold ratings.
Cerebras carries the largest analyst-implied upside among these stocks by a wide margin. It also has the weakest stock. That combination points to a company-specific problem, and the sector itself looks healthy.
A 98.9% Target Gap While the S&P 500 Gains 14.1%
At $146.62, Cerebras would need to gain about 98.9% to reach the $291.64 consensus from 11 analysts. Shares are down 23.61% over the past month. Over the same stretch the S&P 500 gained 1.81%, and the index is up 14.1% year to date.
The stock still trades at a forward P/E of 217, so even after the drop it is far from cheap. Treat price targets as one data point, subject to change.
Backlog Justifies the Risk, but OpenAI Sets the Leash
The bull case strengthens if the AMD and AWS disaggregated products ship on schedule and the expected Q4 margin rebound shows up, which would prove that speed still wins workloads. Risk makes if OpenAI’s move to NVIDIA spreads to other workloads, because customer concentration in OpenAI, G42, MBZUAI, AWS leaves the backlog exposed.
With $6.74B in cash, near-term funding looks secure. The outlook are cautiously bullish. Still, the next earnings report needs to show where OpenAI revenue is headed before the UBS target looks reachable. For investors hunting the next oversized tech winner, we reverse-engineered what the biggest chip runs looked like early in a free playbook you can grab here.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.