Prediction: CoreWeave Could Be One of the Most Explosive AI Stocks of the Decade
CoreWeave sits on a backlog that dwarfs its closest rival, yet the stock has shed nearly 18% in a month and carries a debt load that would make most CFOs sweat. Whether that backlog actually converts into cash flow determines…

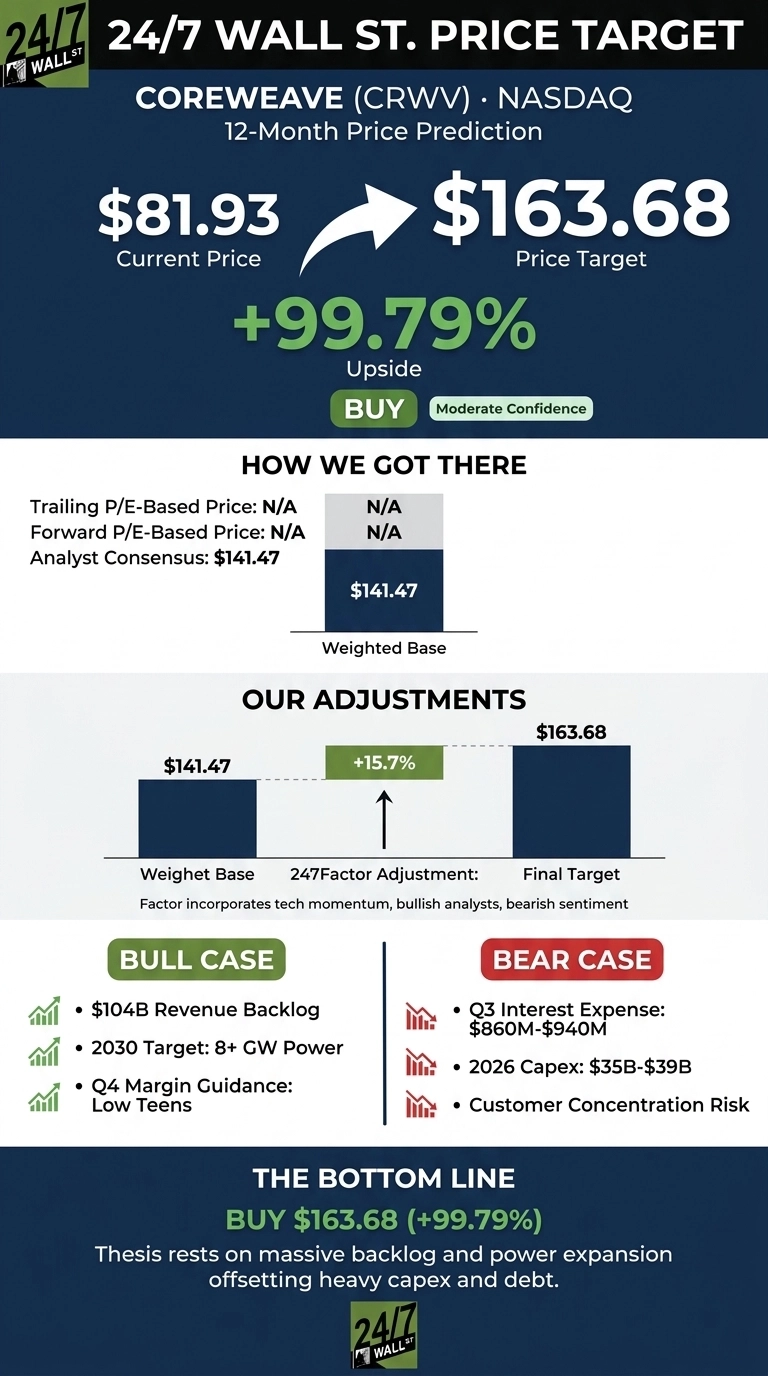
The 24/7 Wall St. price target for CoreWeave (NASDAQ:CRWV) is $163.68 over the next 12 months. The stock trades at $81.93, so the target implies 99.79% upside and carries a buy rating with moderate confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $81.93 |
| Price Target from 24/7 Wall St. | $163.68 |
| Upside/Downside | 99.79% |
| Recommendation | BUY |
| Confidence Level | 50% |
The thesis rests on a $104B revenue backlog and 2026 revenue guidance of $12.4 to $13.2 billion. Confidence remains moderate because of heavy losses, $640M in quarterly interest expense, and debt-to-equity of 8.94.
An OpenAI Scare Extends a Rough Month for CRWV
Shares fell 7.5% over the past week and 17.93% over the past month, but remain up 14.41% year to date. The stock trades 46.5% below its 52-week high of $153.20 and 35.3% above its $60.55 low.
On Thursday, Nvidia (NASDAQ:NVDA | NVDA Price Prediction) and Oracle (NYSE:ORCL) slipped too, as Nvidia, Oracle, CoreWeave and other AI stocks sank on an OpenAI revenue report, a sensitive headline given OpenAI commitments of roughly $22.4B.
Fundamentals look stronger. Q2 revenue reached $2.575B, up 112.3% and ahead of the $2.555B estimate. GAAP EPS of -$1.14 beat the -$1.447 consensus, and operating cash flow swung to $679M from -$251M.
How We Calculated $163.68
A proprietary model combining trailing P/E, forward P/E, and the consensus analyst target supports the 24/7 Wall St. price target. CoreWeave has no earnings to capitalize, so the model weighted the $141.47 analyst target fully. That consensus reflects 8 Strong Buy and 23 Buy ratings against 2 Sells and 1 Strong Sell.
We then applied our 247Factor of 1.157. Technology sector momentum and bullish analyst consensus raised the figure, while bearish retail sentiment cut 0.021 and a large-cap drag trimmed factor effects by 30%.
Why Bulls See $167 and Beyond
The upside scenario reaches $167.78. Q2 contracts carry contribution margins 5 to 10 percentage points above recent quarters, before an approximately 25% July price increase. More than $25 billion of new commitments landed in early Q3, outside the reported backlog.
Management targets low-teens adjusted operating margins in Q4 and at least 8 gigawatts by 2030 (we featured seven of the power, cooling, and networking suppliers riding that same expansion in a free AI infrastructure report). CEO Michael Intrator said: “We expect demand to meaningfully exceed supply for years.”
Debt and Capex Could Test Investor Patience
Our bear case stands at $130.92, though the 52-week low shows how hard sentiment can swing. Q2 net loss widened to $626 million from $290 million, Q3 interest expense is guided to $860 to $940 million, and 2026 capex should hit $35 to $39 billion.
Customer concentration and a pending securities class action add risk. Bulls would counter that CoreWeave cut its cost of debt by almost 300 basis points, worth roughly $1.1 billion in annualized savings.
How CoreWeave Compares to Nebius and Oracle
Nebius Group (NASDAQ:NBIS) is the closest pure-play GPU cloud rival. Q2 revenue jumped 454.04%, but its $37.5B in signed obligations trails CoreWeave’s backlog, giving CoreWeave greater revenue visibility.
Oracle competes for the same AI contracts at larger scale. Cloud infrastructure revenue grew 121%, yet free cash flow was -$5.4 billion, a sign that negative cash flow is common among large players during this expansion.
| Company | Latest Revenue Growth | Backlog/RPO |
|---|---|---|
| CoreWeave | 112.3% | $104B |
| Nebius | 454.04% | $37.5B |
| Oracle (IaaS) | 121% | $664B |
Against this group, CoreWeave pairs triple-digit growth with a backlog well ahead of Nebius.
Backlog Strength Tips CoreWeave to a BUY
The 24/7 Wall St. price target of $163.68 carries a buy rating at 50% confidence. The key factor is backlog converting into cash flow.
Upside strengthens if Q4 adjusted operating margins reach the guided low teens. Downside risk grows if interest costs exceed guidance or OpenAI demand weakens. The backlog offsets the balance-sheet risk.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $96.07 |
| 2027 | $163.68 |
| 2028 | $220.85 |
| 2029 | $297.98 |
| 2030 | $402.06 |
These projections assume CoreWeave keeps executing on its power and backlog plan. Financing costs or a pullback in AI spending could shift them significantly.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.